Carbon Capture, Utilization & Storage: A General Overview
英文原文与中文译文逐段对照 · English original with Chinese translation
Jun Fu · Dongxiao Zhang · Ming Lei Editors
傅军·张东晓·雷明 编辑
Climate Mitigation and Adaptation in China
中国的气候缓解与适应
Policy, Technology and Market
政策、技术与市场
2 Springer 冶金工业出版社
2 施普林格 冶金工业出版社
Metallurgical Industry Press
冶金工业出版社
Climate Mitigation and Adaptation in China Policy, Technology and Market
中国的气候缓解与适应:政策、技术与市场
“A superb book.”
“一本极好的书。”
-Ngaire Woods, Oxford University, Fellow of the British Academy of Social Sciences
-牛津大学的恩盖尔·伍兹,英国社会科学院院士
“Climate Mitigation and Adaptation in China is a sophisticated study of China’s efforts to decarbonize its economy, which is especially valuable for its sensitivity to global policy discussions and its awareness of the close connections between international commitments and domestic public policy choices.”
“《中国的气候缓解与适应》是对中国经济脱碳努力的深入研究,因其对全球政策讨论的敏感性以及对国际承诺与国内公共政策选择之间紧密联系的认识而尤为珍贵。”
-Robert O. Keohane, Princeton University, Member of the US National Academy of Sciences
-罗伯特·O·基欧汉,普林斯顿大学,美国国家科学院院士
“The role of China in tackling climate change will be critical to the success in facing up to the world’s greatest challenge. This book explores how policy, technology and markets need to work together to create the conditions to move to a green economy as a model for others to follow.”
“中国在应对气候变化方面的作用对于成功应对全球最大挑战至关重要。本书探讨了政策、技术和市场如何协同发挥作用,以创造条件迈向绿色经济,为其他国家树立榜样。”
-Philip Allmendinger, University of Cambridge, Fellow of the British Academy of Social Sciences
-菲利普·奥尔门丁格,剑桥大学,英国社会科学院院士
“This is a deep, up-to-date and rigorous analysis of China’s strategic, economic, and technological pathways towards carbon neutrality… An essential reading to understand the new role of China in the global governance of climate change.”
“这是对中国实现碳中和的战略、经济和技术路径的深入、最新且严谨的分析……是理解中国在全球气候变化治理中新角色的必读书籍。”
-Alberto Quadrio-Curzio, President, the International Balzan Prize Foundation, and President Emeritus, the National Academy of Lincei, Italy
-阿尔贝托·夸德里奥 - 库尔齐奥,国际巴尔赞奖基金会主席,意大利国家科学院名誉主席
“This book provides important insights into Chinese thinking and Chinese policy toward decarbonization. It will be of interest to anyone concerned about Chinese policies toward climate change—and, more broadly, to anyone concerned about the potential for successful action to mitigate climate change globally.”
“本书深入洞察了中国在脱碳问题上的思考与政策。对于任何关注中国气候变化政策的人——更广泛地说,对于任何关注全球成功采取行动缓解气候变化潜力的人来说,它都将是一本有价值的读物。”
—Jeffry Frieden, Harvard University, Member of the American Academy of Arts and Sciences
—杰弗里·弗里登,哈佛大学,美国艺术与科学学院院士
“As a major and growing economy, China’s role in meeting a global climate challenge is simply crucial. Professor Fu Jun and his colleagues have done a masterful job of laying out the parameters, policies and prospects of China’s path to sustainability. It should be essential reading, domestically and internationally.”
“作为一个不断发展的主要经济体,中国在应对全球气候挑战方面的作用至关重要。傅军教授及其同事出色地阐述了中国可持续发展道路的参数、政策和前景。这本书无论在国内还是国际都应是必读之作。”
-A. Michael Spence, Stanford University, Nobel Memorial Prize Laureate in Economic Sciences
-A. 迈克尔·斯宾塞,斯坦福大学,诺贝尔经济学奖获得者
Jun Fu $\cdot$ Dongxiao Zhang $\cdot$ Ming Lei Editors
傅军 $\cdot$ 张东晓 $\cdot$ 雷明 编辑
Climate Mitigation and Adaptation in China
中国的气候缓解与适应
Policy, Technology and Market
政策、技术与市场
Editors
编辑
Jun Fu Dongxiao Zhang
傅军 张东晓
National School of Development College of Engineering
国家发展研究院 工程学院
Peking University Peking University
北京大学 北京大学
Beijing, China Beijing, China
中国北京 中国北京
Ming Lei
雷鸣
Guanghua School of Management
光华管理学院
Peking University
北京大学
Beijing, China
中国北京
ISBN 978-981-16-4309-5 ISBN 978-981-16-4310-1 (eBook)
ISBN 978 - 981 - 16 - 4309 - 5 ISBN 978 - 981 - 16 - 4310 - 1(电子书)
https://doi.org/10.1007/978-981-16-4310-1
Jointly published with Metallurgical Industry Press, Beijing, China
与冶金工业出版社联合出版,中国北京
The print edition is not for sale in China (Mainland). Customers from China (Mainland) please order the print book from: Metallurgical Industry Press
印刷版不在中国(大陆)销售。中国大陆的客户请从冶金工业出版社订购印刷版图书
© Metallurgical Industry Press 2022, corrected publication 2023
©冶金工业出版社2022年,修订版2023年
This work is subject to copyright. All rights are solely and exclusively licensed by the Publisher, whether the whole or part of the material is concerned, specifically the rights of reprinting, reuse of illustrations, recitation, broadcasting, reproduction on microfilms or in any other physical way, and transmission or information storage and retrieval, electronic adaptation, computer software, or by similar or dissimilar methodology now known or hereafter developed.
本作品受版权保护。出版商独家授权所有权利,无论涉及全部或部分材料,特别是重印、重新使用插图、朗诵、广播、缩微胶片复制或以任何其他物理方式复制,以及传播或信息存储与检索、电子改编、计算机软件,或采用现在已知或此后开发的类似或不同方法。
The use of general descriptive names, registered names, trademarks, service marks, etc. in this publication does not imply, even in the absence of a specific statement, that such names are exempt from the relevant protective laws and regulations and therefore free for general use.
本出版物中使用的通用描述性名称、注册名称、商标、服务标记等,即使没有具体声明,也不意味着这些名称不受相关保护法律法规的约束,因此可以随意使用。
The publishers, the authors, and the editors are safe to assume that the advice and information in this book are believed to be true and accurate at the date of publication. Neither the publishers nor the authors or the editors give a warranty, express or implied, with respect to the material contained herein or for any errors or omissions that may have been made. The publishers remain neutral with regard to jurisdictional claims in published maps and institutional affiliations.
出版商、作者和编辑可以合理地假定,本书中的建议和信息在出版之日被认为是真实准确的。出版商、作者或编辑均不对本书所含材料或可能出现的任何错误或遗漏提供明示或暗示的保证。出版商在已出版地图的管辖权主张和机构隶属关系方面保持中立。
This Springer imprint is published by the registered company Springer Nature Singapore Pte Ltd. The registered company address is: 152 Beach Road, #21-01/04 Gateway East, Singapore 189721, Singapore
本施普林格印记由注册公司施普林格自然新加坡私人有限公司出版。注册公司地址为:新加坡滨海路152号,东大门大厦#21-01/04,邮编189721
Preface
前言
Climate change is a huge challenge facing humanity in the twenty-first century. The 2015 Paris Agreement represents a global consensus to keep global temperatures well below ${2}^{ \circ }\mathrm{C}$ above the pre-industrial levels and to pursue further efforts to limit the temperature increase within ${1.5}^{ \circ }\mathrm{C}$ . In 2018, the UN Intergovernmental Panel on Climate Change (IPCC) has further warned that the impact of above ${1.5}^{ \circ }\mathrm{C}$ of global warming will spell disasters to the ecosystem on Earth. As a response to the call for renewed efforts at mitigation and adaptation to climate change, in 2020, China has again pledged to the international community that it will peak ${\mathrm{{CO}}}_{2}$ (carbon dioxide) emissions prior to 2030 and try to achieve carbon neutrality by 2060-indeed a tall order to fulfill given China’s current stage of development.
气候变化是21世纪人类面临的巨大挑战。2015年的《巴黎协定》代表了全球共识,即把全球气温保持在比工业化前水平高出${2}^{ \circ }\mathrm{C}$以上,并进一步努力将升温限制在${1.5}^{ \circ }\mathrm{C}$以内。2018年,联合国政府间气候变化专门委员会(IPCC)进一步警告称,全球变暖超过${1.5}^{ \circ }\mathrm{C}$将给地球生态系统带来灾难。为响应加强气候变化缓解和适应努力的呼吁,2020年,中国再次向国际社会承诺,将在2030年前实现${\mathrm{{CO}}}_{2}$(二氧化碳)排放达峰,并力争在2060年前实现碳中和——鉴于中国目前的发展阶段,这确实是一项艰巨的任务。
Fight against climate change calls for concerted efforts by all walks of life, both domestic and international (e.g., if every individual in China were to reduce one ton of ${\mathrm{{CO}}}_{2}$ each year, it would amount to a total reduction of 1.4 billion tons of ${\mathrm{{CO}}}_{2}$ , which is roughly an equivalent of the yearly ${\mathrm{{CO}}}_{2}$ emissions by the Chinese steel or cement industry). Similarly, as reflected by the on-going research on climate change at Peking University, cross-disciplinary approach is highly desirable. Presented here is a book-length study organized through what one may call a triple helix of three schools at Peking University—the National School of Development, the College of Engineering, and the Guanghua School of Management. The scholars and experts associated with these three schools cover three domains of knowledge-policy, technology, and markets-that are essential in fight against climate change.
应对气候变化需要国内外各界齐心协力(例如,如果中国每个人每年减少一吨${\mathrm{{CO}}}_{2}$排放,总计将减少14亿吨${\mathrm{{CO}}}_{2}$,这大致相当于中国钢铁或水泥行业一年的${\mathrm{{CO}}}_{2}$排放量)。同样,正如北京大学正在进行 的气候变化研究所示,跨学科方法非常必要。本书是一项长篇研究,由北京大学的三所学院——国家发展研究院、工学院和光华管理学院——以所谓的“三螺旋”形式组织而成。与这三所学院相关的学者和专家涵盖了应对气候变化至关重要的三个知识领域——政策、技术和市场。
China is a large developing country with 1.4 billion people in the midst of industrialization and urbanization. GDP per capita in China in 1979 is about US$156; it is about US$ 10,000 in 2020; urbanization is 18% in 1979; it is close to 60% in 2020. Topping output of 220 of 500 major industrial products in the world in 2011, China became the world’s largest industrial country. As a consequence, currently China is the largest ${\mathrm{{CO}}}_{2}$ emitter in the world, and it contributes roughly a quarter of global ${\mathrm{{CO}}}_{2}$ emissions, although on per capita basis, China has remained moderate-about $7{\mathrm{{tCO}}}_{2}$ per year, as compared to ${16}{\mathrm{{tCO}}}_{2}$ for the U.S. and $5{\mathrm{{tCO}}}_{2}$ for the world average.
中国是一个拥有14亿人口的大型发展中国家,正处于工业化和城市化进程中。1979年中国的人均国内生产总值约为156美元;2020年约为10000美元;1979年的城市化率为18%;2020年接近60%。2011年,中国在500种主要工业产品中的220种产量位居世界第一,成为世界最大的工业国。因此,目前中国是世界上最大的${\mathrm{{CO}}}_{2}$排放国,约占全球${\mathrm{{CO}}}_{2}$排放量的四分之一,不过从人均来看,中国一直保持在适度水平——每年约$7{\mathrm{{tCO}}}_{2}$,而美国为${16}{\mathrm{{tCO}}}_{2}$,世界平均水平为$5{\mathrm{{tCO}}}_{2}$。
Take the iron/steel sector in China for instance. The sector has a total of some 500 firms with a total output of crude steel reaching 1.065 billion tons in 2020, accounting for over 57% of the world’s total. In terms of ${\mathrm{{CO}}}_{2}$ emissions, it accounts for over ${60}\%$ of total ${\mathrm{{CO}}}_{2}$ emissions from global steel production and about ${15}\%$ of total domestic industrial ${\mathrm{{CO}}}_{2}$ emissions, following the power (including heat) sector (about ${50}\%$ ) and above the cement sector (about ${12}\%$ ).
以中国的钢铁行业为例。该行业共有约500家企业,2020年粗钢总产量达10.65亿吨,占世界总产量的57%以上。在${\mathrm{{CO}}}_{2}$排放方面,它占全球钢铁生产${\mathrm{{CO}}}_{2}$排放总量的${60}\%$以上,约占国内工业${\mathrm{{CO}}}_{2}$排放总量的${15}\%$,仅次于电力(包括热力)行业(约${50}\%$),高于水泥行业(约${12}\%$)。
But China has been working hard at mitigation and adaptation to climate change and trying to de-couple economic growth from ${\mathrm{{CO}}}_{2}$ emissions at the earliest date possible. And the present study provides a prism through which to see China’s efforts and appreciate its magnitude. The study is organized around the three linchpins, i.e., Part I, Policy; Part II, Technology; and Part III, Market. This study ends with a projection to 2060 in Part IV, by which China has pledged to achieve carbon neutrality. China has to be an integral part of the global efforts in fight against climate change-the most consequential threat facing humanity. As the latest UN Intergovernmental Panel on Climate Change suggests, without concerted efforts, the dire situation will only get worse. Everyone must act now-with a sense of urgency-to address the crisis.
但中国一直在努力应对气候变化的缓解和适应问题,并试图尽早使经济增长与${\mathrm{{CO}}}_{2}$排放脱钩。本研究提供了一个视角,通过它可以看到中国的努力并认识到其规模。该研究围绕三个关键要素组织,即第一部分,政策;第二部分,技术;第三部分,市场。本研究在第四部分对2060年进行了预测,到那时中国已承诺实现碳中和。中国必须成为全球应对气候变化努力的一部分——这是人类面临的最重大威胁。正如联合国政府间气候变化专门委员会最新报告所指出的,如果不共同努力,严峻的形势只会变得更糟。每个人现在都必须带着紧迫感采取行动来应对这场危机。
What follows is a synopsis of the these principal building blocks-as well as the overall research design-of the study.
以下是本研究的这些主要组成部分以及总体研究设计的概述。
Part I Policy
第一部分 政策
At a fundamental level, climate change reflects the logic of negative externalities of what scholars have described as “the tragedy of the commons.” In order to prevent that tragedy from happening, public policy becomes indispensable. To understand China’s evolving policy framework to decarbonize its economy, a principal theme to watch is the dynamic interaction between China’s international commitments and domestic agenda setting with respect to climate change. At the risk of oversimplification, three sets of milestone international commitments can be identified for China’s efforts of mitigation and adaption to climate change.
从根本层面来看,气候变化反映了学者们所说的“公地悲剧”的负外部性逻辑。为防止这种悲剧发生,公共政策变得不可或缺。要理解中国不断演变的经济脱碳政策框架,一个主要的观察点是中国在气候变化方面的国际承诺与国内议程设定之间的动态互动。冒着过度简化的风险,可以为中国应对气候变化的缓解和适应努力确定三组具有里程碑意义的国际承诺。
Under the principle of “common and differentiated responsibilities” of the UNFCCC (UN Framework Convention for Climate Change), in 2009, China pledged to the international community to reduce carbon intensity per unit of GDP by 40-45% by 2020 from the level of 2015. In 2015, China pledged again to peak carbon emissions around 2030 and reduce carbon intensity by 60-65% by 2030 from the level of 2005. In 2020, building upon previous successes, China again pledged that it would peak carbon emissions prior to 2030 and try to achieve carbon neutrality by 2060. This pledge was particularly significant. Indeed, shifting from carbon equity toward carbon neutrality indicates a change of political philosophy from particular justice to general justice. (Note that China, about 157 ${\mathrm{{tCO}}}_{2}$ , was still below the world average, about ${209}{\mathrm{{tCO}}}_{2}$ , in terms of per capita accumulated ${\mathrm{{CO}}}_{2}$ emissions from 1900 to 2019. By comparison, it was about ${1218}{\mathrm{{tCO}}}_{2}$ for the U.S., ${930}{\mathrm{{tCO}}}_{2}$ for the U.K., and ${516}{\mathrm{{tCO}}}_{2}$ for France). These international commitments, in turn, have been successively factored into China’s 11th Five-Year Plan (FYP 2006-2010), 12th FYP 2011-2015, 13th FYP 2016- 2020, and 14th FYP 2021-2025, and together they have constituted an evolving policy framework, shaping the country’s efforts to decarbonize its developmental path.
根据《联合国气候变化框架公约》(UNFCCC)的“共同但有区别的责任”原则,2009年,中国向国际社会承诺,到2020年单位国内生产总值碳排放强度比2005年水平降低40%-45%。2015年,中国再次承诺到2030年左右实现碳排放达峰,并到2030年单位国内生产总值二氧化碳排放比2005年下降60%-65%。2020年,在以往成功的基础上,中国再次承诺将在2030年前实现碳排放达峰,并努力在2060年前实现碳中和。这一承诺尤为重要。事实上,从碳排放公平转向碳中和表明政治理念从特殊正义向普遍正义的转变。(请注意,从1900年到2019年,中国约157${\mathrm{{tCO}}}_{2}$的人均累计${\mathrm{{CO}}}_{2}$排放量仍低于世界平均水平约${209}{\mathrm{{tCO}}}_{2}$。相比之下,美国约为${1218}{\mathrm{{tCO}}}_{2}$,英国为${930}{\mathrm{{tCO}}}_{2}$,法国为${516}{\mathrm{{tCO}}}_{2}$)。这些国际承诺反过来又相继被纳入中国的第十一个五年规划(2006-2010年)、第十二个五年规划(2011-2015年)、第十三个五年规划(2016-2020年)和第十四个五年规划(2021-2025年),它们共同构成了一个不断演变的政策框架,塑造了中国努力使其发展道路脱碳的进程。
Initial evidence is compelling that China has taken these commitments seriously. In 2019, for instance, China has fulfilled its 2009 pledge one year ahead of schedule, with carbon intensity reduced by 48.1% from the 2005 level and non-fossil fuels raised to 15.3% as a share of energy structure. In 2016-2019, a total of 1.4 billion tons of ${\mathrm{{CO}}}_{2}$ emissions were reduced due to work at energy efficiency nation-wide. As evidenced in the steel sector, with both “sticks” and “carrots,” the Chinese government had aggressively pursued a low-carbon strategy, by way of reducing inefficient overcapacity and enhancing energy efficiency in the 13th FYP (2016-2020). And the steel sector has been planning for a super-low-carbon strategy for the 14th FYP (2021-2025). Arguably, the overall current approach seems to be more fiat than market. But the trend is increasingly market-oriented. Indeed, having gained experience from its eight $\left( {7 + 1}\right)$ regional ETS pilots, China operationally rolled out a national carbon market (or ETS) in 2021, which promised to become the largest in the world.
有令人信服的初步证据表明中国认真对待了这些承诺。例如,2019年,中国提前一年完成了2009年的承诺,碳排放强度比2005年水平降低了48.1%,非化石能源在能源结构中的占比提高到了15.3%。2016-2019年,由于全国范围内的能效工作,共减少了14亿吨${\mathrm{{CO}}}_{2}$排放。正如钢铁行业所证明的那样,中国政府通过“胡萝卜加大棒”的方式,在第十三个五年规划(2016-2020年)中积极推行低碳战略,减少低效产能并提高能源效率。钢铁行业也在为第十四个五年规划(2021-2025年)制定超低碳战略。可以说,目前总体的方法似乎更多是指令性而非市场化的。但趋势越来越朝着市场化方向发展。事实上,中国从其八个$\left( {7 + 1}\right)$区域碳排放交易体系试点中积累了经验,于2021年正式推出了全国碳市场(或碳排放交易体系),有望成为全球最大的碳市场。
The Paris Agreement set out a global action plan to keep the world on track by limiting global warming to well below ${2}^{ \circ }\mathrm{C}$ above pre-industrial levels in the long-term and urged contracting states to undertake rapid carbon emission reductions with best available technologies (BATs). As a contracting state to the Paris Agreement, China has been keen on BATs, as illustrated by its policies to encourage and shape the development of carbon capture, utilization, and storage (CCUS). Indeed, as a global fieldtrip would attest, in the last few years China has been catching up rapidly in this field and has become one of six leading countries (the USA, Canada, UK, Norway, Japan, China) in the world. Thus far, whereas most CCUS pilots and demonstrations in China are in the power sector (accounting for about ${50}\%$ of total industrial ${\mathrm{{CO}}}_{2}$ emissions), its steel sector (accounting for about 15% to total industrial ${\mathrm{{CO}}}_{2}$ emissions) seems increasingly posed to set up CCUS pilots as well in the 14th FYP (2021-2025).
《巴黎协定》制定了一项全球行动计划,旨在通过长期将全球变暖限制在远低于工业化前水平${2}^{ \circ }\mathrm{C}$以上,使世界走上正轨,并敦促缔约国利用现有最佳技术(BAT)迅速减少碳排放。作为《巴黎协定》的缔约国,中国一直热衷于采用最佳可用技术,其鼓励和推动碳捕获、利用与封存(CCUS)发展的政策就体现了这一点。事实上,正如一次全球实地考察所证明的那样,在过去几年里,中国在这一领域迅速追赶,已成为世界上六个领先国家(美国、加拿大、英国、挪威、日本、中国)之一。到目前为止,虽然中国的大多数CCUS试点和示范项目都在电力部门(约占工业${\mathrm{{CO}}}_{2}$总排放量的${50}\%$),但其钢铁部门(约占工业${\mathrm{{CO}}}_{2}$总排放量的15%)在“十四五”规划(2021 - 2025年)期间似乎也越来越有可能开展CCUS试点。
Part II Technology
第二部分 技术
Generally speaking, there are three broad categories of technologies of decarbonization, i.e., low carbon, zero carbon, and negative carbon. To illustrate, hydraulic, wind, and solar power are examples of zero-carbon technologies, but the caveat here is the supply incongruence or instability of wind and solar energy for the grid, unless battery technology has made hitherto unknown breakthroughs. Currently, however, only about 15% of China’s grid capacity is VRE (variable renewable energy) compatible for wind and solar power, the sources of which vary across different regions and are unstable by nature, although their cost, excluding storage, has come down dramatically in recent years. The challenge here is for the grid to move up to higher phases of VRE integration. Or an alternative strategy is to develop green (as opposed to grey) hydrogen. That is, to use wind or solar power to produce green hydrogen locally and then store and transport it cross-regionally. In this case, attendant technology for its storage and transport must also be developed on scale. Note as well, on the endless frontier of science to watch, nuclear fusion of deuterium and tritium, two hydrogen isotopes, if successful, would mean the ultimate clean energy that is almost boundless.
一般来说,脱碳技术大致可分为三大类,即低碳、零碳和负碳技术。例如,水力、风能和太阳能属于零碳技术,但这里需要注意的是,除非电池技术取得前所未有的突破,否则风能和太阳能对电网的供应不一致或不稳定。然而,目前中国电网容量中只有约15%与风能和太阳能等可变可再生能源(VRE)兼容,其来源因地区而异,本质上不稳定,尽管近年来其成本(不包括存储成本)已大幅下降。这里的挑战在于电网要提升到更高阶段的VRE整合。或者另一种策略是开发绿色(而非灰色)氢气。也就是说,利用风能或太阳能在当地生产绿色氢气,然后跨地区存储和运输。在这种情况下,其存储和运输的相关技术也必须大规模开发。同样需要注意的是,在无尽的科学前沿,氘和氚这两种氢同位素的核聚变如果成功,将意味着几乎无限的终极清洁能源。
Various techniques or methods of energy conservation and energy efficiency-aggressively pursued in China’s iron/steel sector thus far-typically embody low carbon technologies. By contrast, carbon capture, utilization, and storage (CCUS), including both onshore and offshore sequestration, represents negative carbon technology. Looking forward, a strategic pathway for China to move toward carbon neutrality by 2060 is likely to feature a dynamic mix in different proportions of all three categories of technologies.
中国钢铁行业迄今积极推行的各种节能和提高能效的技术或方法,通常体现为低碳技术。相比之下,碳捕获、利用与封存(CCUS),包括陆上和海上封存,则代表负碳技术。展望未来,中国到2060年实现碳中和的战略路径可能会以不同比例动态混合这三类技术为特征。
To cut into the web of green technologies, our research strategy is to address the most complex and still evolving one head on, i.e., CCUS, believing that, having done the most difficult, the rest-e.g., hydraulic, wind, and solar power, etc.- would be relatively easier to piece together. After all, much research has already been done on the latter part of the picture, the basic contour is clear, and we do not have to start from scratch. Accordingly, lending credence to the strategic roadmap based on simulation for the future deployment of CCUS in the Chinese steel sector in the previous chapter, Part II of this study takes an in-depth look at CCUS as an emerging strategic reserve technology on industrial scale for direct abatement of ${\mathrm{{CO}}}_{2}$ emissions. Under country-specific engineering conditions, the study begins by methodically going through a typical iron/steel plant in China. In the process, it provides a systematic analysis of the appropriate options as well as potential pitfalls of ${\mathrm{{CO}}}_{2}$ capture technologies-physical or chemical or both—in steel-making processes, including options for ${\mathrm{{CO}}}_{2}$ transport and storage. In addition, cost estimates, together with tech-performance, of a full-chain CCUS are also provided to assist planners or decision-makers in identifying most cost-effective pathways.
为切入绿色技术网络,我们的研究策略是直接应对最复杂且仍在不断发展的技术,即CCUS,相信在攻克最困难的部分后,其余部分(如水力、风能和太阳能等)相对更容易整合。毕竟,对于后者已经进行了大量研究,基本轮廓清晰,我们不必从头开始。因此,基于上一章对中国钢铁行业CCUS未来部署的模拟战略路线图,本研究的第二部分深入探讨CCUS作为一种新兴的工业规模战略储备技术,用于直接减少${\mathrm{{CO}}}_{2}$排放。在特定国家的工程条件下,该研究首先有条不紊地考察中国一家典型的钢铁厂。在此过程中,它对炼钢过程中${\mathrm{{CO}}}_{2}$捕获技术(物理或化学或两者兼有)的合适选项以及潜在陷阱进行了系统分析,包括${\mathrm{{CO}}}_{2}$运输和存储选项。此外,还提供了全链CCUS的成本估算以及技术性能,以协助规划者或决策者确定最具成本效益的途径。
For example, integrated infrastructural outlays involving optimal ${\mathrm{{CO}}}_{2}$ source-sink matching can presumably reduce unit cost of a CCUS-retrofitted plant operating in a hub-spoke cluster. In light of the source-sink matching and the maturity of various CCUS technologies for ${\mathrm{{CO}}}_{2}$ emission reduction in the near, medium, and long term, there is evidence to suggest that the steel sector should adopt the strategy linking enhanced oil recovery (EOR) and enhanced coal bed methane recovery (ECBM) technologies as the near- and medium-term utilization and storage solution and storage in deep saline aquifers as the long-term storage solution. At present, EOR and ECBM in China, experimentally or otherwise, account for only a few million tons of ${\mathrm{{CO}}}_{2}$ used annually-indeed a tiny part of the 10.4 billion tons of ${\mathrm{{CO}}}_{2}$ that China emitted in 2020. Beyond the steel sector and for considerations of scale economy and public good, it also makes sense for the government to plan, design, and invest in the basic infrastructure of hub-spoke transport clusters to facilitate or speed up the deployment of integrated full-chain CCUS projects.
例如,涉及优化${\mathrm{{CO}}}_{2}$源汇匹配的综合基础设施支出可能会降低在枢纽 - 辐条集群中运行的CCUS改造工厂的单位成本。鉴于源汇匹配以及近期、中期和长期用于减少${\mathrm{{CO}}}_{2}$排放的各种CCUS技术的成熟度,有证据表明钢铁行业应采用将提高石油采收率(EOR)和提高煤层气采收率(ECBM)技术作为近期和中期利用与存储解决方案,以及将深层盐水含水层存储作为长期存储解决方案的策略。目前,中国的EOR和ECBM,无论是实验性的还是其他方式,每年仅使用几百万 吨${\mathrm{{CO}}}_{2}$——确实只是中国2020年排放的104亿吨${\mathrm{{CO}}}_{2}$中的一小部分。除了钢铁行业,出于规模经济和公共利益的考虑,政府规划、设计和投资枢纽 - 辐条运输集群的基础设施也有意义,以促进或加速全链CCUS综合项目的部署。
Currently, however, while slow progress on CCUS pilots or demonstrations has been under way in China and overseas, huge initial investment and lack of viable business models for cost considerations are seen as the main obstacle to rapid development of CCUS, globally. The International Energy Agency (IEA) has warned that CCUS is not on track for Paris Agreement targets and picking up the pace of CCUS deployment is urgent. In China, currently CCUS pilots are mostly in coal-fired power plant and none has captured ${\mathrm{{CO}}}_{2}$ emissions in the steel and the cement sector. But as China revs up efforts to achieve carbon neutrality by 2060, it is expected that the deployment of CCUS would quicken steps in fossil fuels-intensive industries, including in the iron/steel sector. Indeed, if the rapid unfolding of the fast-speed railway network in recent years is any indication, China would also be particularly good at building multiple ${\mathrm{{CO}}}_{2}$ source-sink clusters for CCUS to scale up. And one would anticipate that work is likely to start during the 15th FYP (2026-2030), if not earlier. And if it does, it would be better to pilot first rather than big-bang approach, because CCUS has remained complex, costly, and uncertain in the nexus of all green technologies thus far. As such, in strategic sequencing, it makes sense to see CCUS as a reserve technology or “the lender of last resort”, so to speak, to borrow a term from finance.
然而,目前虽然中国和海外的碳捕集、利用与封存(CCUS)试点或示范项目进展缓慢,但巨大的初始投资以及出于成本考虑缺乏可行的商业模式被视为全球CCUS快速发展的主要障碍。国际能源署(IEA)警告称,CCUS未朝着《巴黎协定》目标迈进,加快CCUS部署的步伐迫在眉睫。在中国,目前CCUS试点大多集中在燃煤电厂,钢铁和水泥行业尚无捕集${\mathrm{{CO}}}_{2}$排放的项目。但随着中国加快努力在2060年前实现碳中和,预计CCUS在包括钢铁行业在内的化石燃料密集型行业的部署将加快步伐。事实上,如果以近年来快速铁路网的迅速发展为例,中国在建设多个用于CCUS扩大规模的${\mathrm{{CO}}}_{2}$源汇集群方面也会特别出色。预计这项工作可能在“十四五”规划期间(2021-2025年)开始,如果不是更早的话。如果是这样,最好先进行试点而不是采取大爆炸式方法,因为到目前为止,在所有绿色技术领域,CCUS仍然复杂、成本高昂且不确定。因此,在战略排序上,可以将CCUS视为一种备用技术,或者可以说,借用金融领域的一个术语,是“最后贷款人”。
Part III Market
第三部分 市场
Right sequencing is a critical component of a successful strategy-a lesson that China has learned from its own experience of reforms and opening-up in the past 40 years. This logic seems to have applied to the development of carbon market in China as well. That is, “testing it out before scaling it up,” so to speak. On the heels of the previous part on technology, lest one forget, markets as humanly-made institutional arrangements are institutional technologies, the design of which has to deal with both politics and economics and as such can either speed up or slow down the rate of production of ideas, products and services. Fundamentally, markets and the rule of law, as is often said, are the two sides of the same coin. In building carbon market, in 2013, after two years of preparations, China rolled out seven regional ETS (emission-trading system) pilots (i.e., in Beijing, Chongqing, Guangdong, Hubei, Shanghai, Shenzhen, and Tianjin) as a first step. The vision was-if these regional ETS pilots were successful-to build a unified national ETS starting in 2017, which eventually would become the largest ETS in the world, covering well over 6 billion tons of ${\mathrm{{CO}}}_{2}$ emissions, or more than half of China’s total ${\mathrm{{CO}}}_{2}$ emissions.
正确的顺序是成功战略的关键组成部分——这是中国从过去40年改革开放的经验中学到的一课。这种逻辑似乎也适用于中国碳市场的发展。也就是说,可以说是“先试点再推广”。紧接上一部分关于技术的内容,需要记住的是,市场作为人为构建的制度安排,是制度技术,其设计必须兼顾政治和经济,因此可以加快或减缓思想、产品和服务的生产速度。从根本上说,正如人们常说的,市场和法治是同一枚硬币的两面。在建设碳市场方面,经过两年的筹备,中国于2013年迈出第一步,推出了七个区域碳排放交易体系(ETS)试点(即北京、重庆、广东、湖北、上海、深圳和天津)。设想是,如果这些区域ETS试点成功,从2017年开始建立统一的全国性ETS,最终将成为世界上最大的ETS,覆盖超过60亿吨的${\mathrm{{CO}}}_{2}$排放,即超过中国${\mathrm{{CO}}}_{2}$排放总量的一半。
Theoretically speaking, ETS built on the theme of “cap and trade” can reduce ${\mathrm{{CO}}}_{2}$ emissions at a lower cost than direct government regulations such as mandated technologies and performance standards. Thus far, the theoretical proposition has been validated by the experience in the USA and the European Union. Are the regional ETS pilots really working in the Chinese context of regional disparities? To assess their validity in terms of behavioral changes on the part of polluting firms toward de-carbonization is thus the focus of Part III. For the sake of analytical rigor, the present study has made efforts to go beyond mere descriptive statistics by deploying the method of synthetic control in evaluating the efficacy of these regional ETS pilots.
从理论上讲,以“总量控制与交易”为主题构建的ETS能够以比直接的政府监管(如强制技术和性能标准)更低的成本减少${\mathrm{{CO}}}_{2}$排放。到目前为止,这一理论命题已在美国和欧盟的经验中得到验证。在中国区域差异的背景下,区域ETS试点真的有效吗?因此,从污染企业脱碳行为变化的角度评估其有效性是第三部分的重点。为了分析严谨,本研究通过运用合成控制法来评估这些区域ETS试点的有效性,努力超越单纯的描述性统计。
Going beyond a prima facie case, the main findings of the investigation are as follows. First, even at this early stage, except Tianjin and Chongqing, there is evidence of varying degrees that these regional ETS pilots have contributed to the reduction of ${\mathrm{{CO}}}_{2}$ emissions, with Hubei ETS pilot being the most salient case. Second, the early success is nevertheless uneven across different regions in China, suggesting that caution is needed when considering scaling up regional ETS pilots to a unified national carbon market after 2017. Given the varying industrial structures in different regions across China for historical reasons, strategically a gradual rather than a big bang approach—with different phase-in periods for various sectors-to the construction of the national ETS would seem appropriate. Or, one could run the risk of making rich regions richer and poor regions poorer.
除了表面情况,调查的主要结果如下。第一,即使在这个早期阶段,除了天津和重庆,有证据表明这些区域ETS试点在不同程度上有助于减少${\mathrm{{CO}}}_{2}$排放,湖北ETS试点最为显著。第二,然而,中国不同地区的早期成功并不均衡,这表明在考虑2017年后将区域ETS试点扩大到统一的全国碳市场时需要谨慎。由于中国不同地区历史原因导致产业结构各异,从战略上讲,对全国ETS的建设采取渐进而非一蹴而就的方法——不同部门有不同的逐步实施阶段——似乎是合适的。否则,可能会有让富裕地区更富、贫困地区更穷的风险。
Third, as information and transparency is essential for market operations, a robust MRV system (monitoring, reporting, and verification) is critical, as China moves further ahead with the construction of the unified national carbon market, as well as with green financing. According to the People’s Bank of China (PBOC), by 2030 China will need to invest about RMB 2.2 trillion on a yearly basis to decarbonize its economy, and the amount will further increase to about RMB 3.9 trillion from 2030 to 2060. To meet the need, both public and private funds must be mobilized.
第三,由于信息和透明度对市场运作至关重要,随着中国进一步推进统一全国碳市场以及绿色融资的建设,强大的MRV系统(监测、报告和核查)至关重要。根据中国人民银行(PBOC)的数据,到2030年,中国每年需要投资约2.2万亿元人民币来实现经济脱碳,从2030年到2060年这一金额将进一步增至约3.9万亿元人民币。为满足这一需求,必须调动公共和私人资金。
By 2020, all of China’s regional ETS pilots had covered a total of some 3000 firms and accumulated a ${\mathrm{{CO}}}_{2}$ trade volume of some 430 million tons, or about RMB 10 billion. Yet the current carbon price of these regional ETS pilots, averaging about RMB ${30}/{\mathrm{{tCO}}}_{2}$ , seemed too low to spur serious strategic shifts in terms of investment in new technologies such as CCUS. In principle, carbon price must reflect environmental cost, and, here, China still has a long way to go. By international comparison, carbon price in the USA and EU was about US$ 15-16/ton in 2018. Globally, unless carbon price increases dramatically in the years to come, say over US$ 70/tCO2, to galvanize a more robust path to decarbonization, it would be difficult to achieve the goal of the 2015 Paris Agreement, i.e., keeping global temperatures well below $2{}^{ \circ }\mathrm{C}$ above the pre-industrial levels.
到2020年,中国所有区域ETS试点共覆盖了约3000家企业,累计${\mathrm{{CO}}}_{2}$交易量约4.3亿吨,或约100亿元人民币。然而,这些区域ETS试点目前的碳价平均约为人民币${30}/{\mathrm{{tCO}}}_{2}$ ,似乎过低,无法促使在诸如碳捕集、利用与封存(CCUS)等新技术投资方面发生重大战略转变。原则上,碳价必须反映环境成本,而在这方面,中国仍有很长的路要走。通过国际比较,2018年美国和欧盟的碳价约为15 - 16美元/吨。在全球范围内,除非未来几年碳价大幅上涨,比如超过70美元/吨二氧化碳,以推动更有力的脱碳路径,否则将难以实现2015年《巴黎协定》的目标,即把全球气温保持在比工业化前水平高$2{}^{ \circ }\mathrm{C}$ 以上。
In this connection, Part III also explores various design options of ETS on how best to incentivize CCUS from the perspective of a business model, for investment decisions with respect to green technologies (not necessarily CCUS) are ultimately made at the firm level, and sensitive to public policy and institutional environment. Take it as a brain teaser to think further ahead, now that China has rolled out a national ETS in 2021, bringing the world’s largest ETS online after three years of preparation on the basis of its experience of eight regional ETS pilots. As a first step, the national ETS now regulates some 2,200 firms from the power sector (including combined heat and power, as well as captive power plants of other sectors), and its scope is expected to expand further in the future, to cover refining and petrochemicals, chemicals, building materials, steel, nonferrous metals, paper, and aviation as well. If and when the national ETS expands to cover all eight sectors, it will cover well over 60% of China’s total emissions down the road.
就此而言,第三部分还从商业模式的角度探讨了排放交易体系(ETS)在如何最好地激励碳捕获、利用与封存(CCUS)方面的各种设计选项,因为关于绿色技术(不一定是CCUS)的投资决策最终是在企业层面做出的,并且对公共政策和制度环境敏感。不妨把这当作一个脑筋急转弯来进一步思考,鉴于中国已于2021年推出了全国碳排放交易体系,在经历了八年区域碳排放交易体系试点经验的基础上,经过三年筹备,将全球最大的碳排放交易体系上线运行。作为第一步,全国碳排放交易体系目前监管电力行业约2200家企业(包括热电联产企业以及其他行业的自备电厂),其覆盖范围预计未来还会进一步扩大,涵盖炼油、石化、化工、建材、钢铁、有色金属、造纸和航空等行业。如果全国碳排放交易体系扩大到覆盖所有这八个行业,那么未来它将覆盖中国总排放量的60%以上。
Part IV Projection
第四部分 预测
Taking stock and looking forward, in 2020, China has pledged to the world that it would peak carbon emissions prior to 2030 and try to achieve carbon neutrality by 2060. The task is daunting. Put in international perspective, China’s deadline is very tight. Whereas most advanced economies have planned to spend 50-70 years from carbon peak to carbon neutrality, China has only given itself a 30-year transition period. Thus, in the years ahead, China must move aggressively to decarbonize its economy, and in the process, transitional risks can be enormous, especially for resource-intensive and fossil fuel-intensive industries. In 2020, China emitted about 10.4 billion ${\mathrm{{tCO}}}_{2}$ -or about 7.4 ${\mathrm{{tCO}}}_{2}/\mathrm{{per}}$ capita-about ${92}\%$ of which comes from the burning of coal (about 7.4 billion ${\mathrm{{tCO}}}_{2}$ ), oil (1.5 billion ${\mathrm{{tCO}}}_{2}$ ), and natural gas (0.6 billion ${\mathrm{{tCO}}}_{2}$ ). As can be imagined, the challenge for China to de-carbonize its economy within the next 40 years can be mind-boggling.
总结过往并展望未来,2020年中国向世界承诺,将在2030年前实现碳排放达峰,并力争在2060年前实现碳中和。这项任务艰巨。从国际视角看,中国设定的期限非常紧迫。大多数发达经济体计划从碳达峰到碳中和需耗时50 - 70年,而中国给自己的过渡期只有30年。因此,在未来几年,中国必须积极推动经济脱碳,在此过程中,转型风险可能巨大,尤其是对资源密集型和化石燃料密集型产业而言。2020年,中国排放了约104亿吨${\mathrm{{tCO}}}_{2}$,即人均约7.4吨${\mathrm{{tCO}}}_{2}/\mathrm{{per}}$,其中约${92}\%$来自煤炭燃烧(约74亿吨${\mathrm{{tCO}}}_{2}$)、石油(15亿吨${\mathrm{{tCO}}}_{2}$)和天然气(6亿吨${\mathrm{{tCO}}}_{2}$)。可想而知,中国在未来40年内实现经济脱碳面临的挑战令人难以置信。
Be that as it may, there are basically four general approaches for China trying to meet the challenge lying ahead, i.e., public policy approach (PPA), market-based approach (MBA), carbon capture and storage (CCS), and nature-based solutions (NBS), such as forest sink. Based the conceptual framework of PPA+MBA+CCS+NBS (or PMCN model for short), a big part of Part IV represents efforts to project forward by way of disciplined exercises of simulation of various scenarios, such that one can see more clearly what lies ahead and reckon how best to respond. On the basis of these simulations or projections, the main takeaways are as follows:
尽管如此,中国应对未来挑战基本有四种通用方法,即公共政策方法(PPA)、基于市场的方法(MBA)、碳捕获与封存(CCS)以及基于自然的解决方案(NBS),比如森林碳汇。基于PPA + MBA + CCS + NBS概念框架(简称PMCN模型),第四部分很大篇幅通过严谨模拟各种情景来进行预测,以便更清晰地看清未来并思考最佳应对方式。基于这些模拟或预测,主要结论如下:
First, as was true during the so-called new normal period, when growth rate of Chinese heavy industry (i.e., energy, cement, steel, automobiles, shipbuilding, construction, etc.) dropped dramatically from above 10% in 2008-2011 to 6% in 2015, generally economic slowdowns have lessened the steep upward trend of ${\mathrm{{CO}}}_{2}$ emissions, thus helping China peak ${\mathrm{{CO}}}_{2}$ emissions by 2030. Conversely, the simulation exercises also show that all the strategies of carbon emission reduction, including ETS, come at the cost of GDP loss, with modest declines in employment, investment, and consumption. That said, a better calibrated mix of policy instruments will take smaller costs of economic loss. In this context, in the various PPA+MBA combinations, high carbon price rather than low energy enhancement is a preferred option. In longer terms, market approach is a preferred choice over administrative fiat.
首先,在所谓的新常态时期,中国重工业(即能源、水泥、钢铁、汽车、造船、建筑等行业)增长率从2008 - 2011年的10%以上大幅降至2015年的6%,经济放缓总体上减缓了${\mathrm{{CO}}}_{2}$排放的急剧上升趋势,从而助力中国在2030年前实现${\mathrm{{CO}}}_{2}$排放达峰。相反,模拟结果还表明,所有碳排放减少策略,包括排放权交易体系(ETS),都以GDP损失为代价,就业、投资和消费会有适度下降。也就是说,校准得更好的政策工具组合将带来较小的经济损失成本。在这种背景下,在各种PPA + MBA组合中,高碳价而非低能源增强是更优选择。从长远来看,市场方法比行政指令更具优势。
Second, to peak ${\mathrm{{CO}}}_{2}$ emissions before 2030 and achieve carbon neutrality by 2060, along the spectrum of PPA+MBA+CCS+NBS, all the instruments currently available (e.g., improvement in energy efficiency, cost reduction in renewable energy, and carbon pricing) are all necessary, but not enough even in a full combination of all above instruments. New instruments, especially for a more powerful shift from fossil to no-fossil fuels, are needed to achieve the carbon neutral goal in time. Here, carbon tax and green finance, including green loans, green bonds, and green projects, are important areas that need further explorations. Lying between PPA and MBA, carbon tax and green finance could be a potent tool to facilitate technology shifting or even leapfrogging from fossil to non-fossil fuels. And just as in ETS, to develop a robust, sophisticated and standardized MRV system, not just domestically but also internationally, including good metrics or protocols of ESG to avoid “green washing” or reduce moral hazards, is also critical in green finance, if only for the sake of risk assessment, e.g., green assets vis-à-vis brown assets. The issue of moral hazards would arise, where people’s interest and risk are not well aligned so they may have incentives to take on greater risk than they would if no one else effectively contributed insurance. Here, we must encourage international cooperation and create the right incentive structures, with respect to risks, rewards, and responsibilities.
其次,要在2030年前实现${\mathrm{{CO}}}_{2}$排放达峰并在2060年前实现碳中和,在PPA + MBA + CCS + NBS范围内,目前所有可用手段(如提高能源效率、降低可再生能源成本和碳定价)都是必要的,但即便将上述所有手段充分结合也还不够。需要新的手段,尤其是能更有力推动从化石燃料向非化石燃料转变的手段,才能及时实现碳中和目标。在此,碳税和绿色金融,包括绿色贷款、绿色债券和绿色项目,是需要进一步探索的重要领域。介于PPA和MBA之间,碳税和绿色金融可能是促进从化石燃料向非化石燃料技术转变甚至跨越的有力工具。就像在排放权交易体系(ETS)中一样,建立一个强大、完善和标准化的监测、报告与核查(MRV)体系,不仅在国内,而且在国际上,包括良好的环境、社会和治理(ESG)指标或协议,以避免“漂绿”或降低道德风险,在绿色金融中也至关重要,哪怕只是为了风险评估,比如区分绿色资产和棕色资产。当人们的利益和风险未得到良好协调时,就会出现道德风险问题,他们可能会有动机承担比无人有效提供保险时更大的风险。在此,我们必须鼓励国际合作,并针对风险、回报和责任建立正确的激励机制。
Finally, combined rather than separate PPA aiming at de-carbonization will reshape the future structure of energy demand most powerfully. Specifically, renewable energy will be on the rise, whereas fossil fuels, especially coal, will decrease. Yet a caveat is in order. Even in the most comprehensive of all PPA scenarios available today, by 2060, renewable energy will only account for less than 80% of energy structure, whereas fossil fuels still account for more than 20%. In this light, introducing carbon tax and promoting the electric vehicle sector and other forms of electrification are important for further reductions in fossil energy, but the prerequisite is that the sources of electricity have to be clean (Currently, however, fossil-fuels power plants account for roughly 70%, the rest is non-fossil-hydraulic roughly ${15}\%$ , wind $7\%$ , nuclear $5\%$ , and solar 3%). And hopefully, variables exogenous to the current parameters of the simulation model-e.g., dramatic expansions of green finance, technology breakthroughs, including additional PPA instruments—may come along the way, thus increasing the chance that China achieve carbon neutrality in time.
最后,旨在脱碳的联合而非单独的电力购买协议(PPA)将最有力地重塑未来的能源需求结构。具体而言,可再生能源将呈上升趋势,而化石燃料,尤其是煤炭,将减少。然而,需要提醒的是。即使在当今所有可用的最全面的PPA情景中,到2060年,可再生能源在能源结构中所占比例仍将不到80%,而化石燃料仍将占20%以上。有鉴于此,引入碳税、推动电动汽车行业及其他形式的电气化对于进一步减少化石能源很重要,但前提是电力来源必须是清洁的(然而目前,化石燃料发电厂约占70%,其余是非化石水力发电约${15}\%$,风能$7\%$,核能$5\%$,太阳能3%)。希望在模拟模型当前参数之外的外部变量,例如绿色金融的大幅扩张、技术突破,包括额外的PPA工具,可能会出现,从而增加中国及时实现碳中和的机会。
Admittedly, accurate and trustworthy predictions are difficult, even when people do their best to model everything relevant. The inputs and assumptions that enter any particular model might significantly affect a conclusion. It is therefore critical to be straightforward about uncertainties if a prediction is to have any value. Note as well, there is a difference between simulation and emulation. Whereas the former is basically linear in thinking, the latter is characterized by both deductive and inductive tinkering, constantly searching for order out of complexity and even chaos. Fundamentally humans are good at emulation. Indeed, facing uncertainties and unknowns, one has to stand ready to adjust and adapt as circumstances change. Accordingly, as a research strategy for such a complex issue as climate crisis threatening humanity, one ought to conceptualize like a “philosophy-king”, straddling different disciplines of knowledge for a broad and yet logically consistent vision, and act like an academic “foot soldier”, who is well armed with the “state-of-the-art” tools or techniques of rigorous analysis and investigation. After all, philosophical views could affect the conceptual framework one deploys to describe predictions, even though not the predictions themselves. And indeed, it is at least in this spirit that the current book is orchestrated and written, leaving ample room for adding details and making corrections down the road, as contingency preparedness by way of both deductive and inductive tinkering increases resilience in transition. Our hope is to provide a rough map rather than the actual driving itself, as we move towards the middle of the 21st century.
诚然,即使人们尽力对所有相关因素进行建模,准确和可靠的预测也很困难。进入任何特定模型的输入和假设可能会显著影响结论。因此,如果预测要有任何价值,坦率地说明不确定性至关重要。还要注意,模拟和仿真之间存在差异。前者在思维上基本是线性的,而后者的特点是既有演绎又有归纳的调整,不断从复杂性甚至混乱中寻找秩序。从根本上说,人类擅长仿真。的确,面对不确定性和未知因素,人们必须随时准备根据情况变化进行调整和适应。因此,作为应对威胁人类的气候危机这样一个复杂问题的研究策略,人们应该像“哲学王”一样进行概念化,跨越不同的知识学科,以获得广泛而逻辑一致的视野,并像学术“步兵”一样行动,充分掌握严谨分析和调查的“最先进”工具或技术。毕竟,哲学观点可能会影响人们用来描述预测的概念框架,尽管不会影响预测本身。事实上,至少本着这种精神编写了本书,随着通过演绎和归纳调整来增加转型中的复原力,为日后补充细节和进行修正留出了足够的空间。我们希望在迈向21世纪中叶的过程中,提供的是一张粗略的地图,而不是实际的驾驶指南。
To sum up, to peak carbon emissions prior to 2030 and achieve carbon neutrality by 2060 is a very tall order, fraught with uncertainties and unknowns down the road. What is certain is that China has to undergo a veritable green revolution -from what the Chinese would say “Gongye Wenming” (industrial civilization) to “Shengtai Wenming” (eco-civilization), which, broadly speaking, would also include protecting biodiversity and healing geo-environmental degradation - both are relevant topics but nevertheless beyond the scope of this study. In the process, as the world is intrinsically interconnected, none of us will be spared the harsh realities of ecological crisis, which means we are all in this together—“Tongzhou Gongji” (all in the same boat).
总之,要在2030年前实现碳排放达峰并在2060年实现碳中和是一项非常艰巨的任务,未来充满不确定性和未知因素。可以确定的是,中国必须经历一场名副其实的绿色革命——用中国人的话说,就是从“工业文明”到“生态文明”,广义而言,这也包括保护生物多样性和修复地球环境退化——这两个都是相关话题,但超出了本研究的范围。在此过程中,由于世界本质上是相互联系的,我们没有人能幸免于生态危机的严峻现实,这意味着我们同舟共济——“同舟共济”。
Acknowledgements
致谢
Initial research included in this book was financially supported by BHP through a project-based grant to Peking University which began in 2017 through 2020 with a focus on carbon capture, utilization and storage (CCUS) in the steel sector. Follow-up research and editing of the book in 2021 through its publication was financially supported by the Leo Koguan Foundation and the Deloitte Touche Tohmatsu CPA Ltd. through their educational and CSR programs. On behalf of our colleagues involved in this cross-disciplinary study, the editors of this book-who have led the research teams on climate change from the National School of Development, the College of Engineering, and the Guanghua School of Management at Peking University—gratefully acknowledge the generous support.
本书纳入的初步研究由必和必拓提供资金支持,通过一个基于项目的赠款给予北京大学,该项目于2017年至2020年开展,重点关注钢铁行业的碳捕获、利用与封存(CCUS)。本书2021年从后续研究到出版的编辑工作由利奥·科关基金会和德勤华永会计师事务所有限公司通过其教育和企业社会责任项目提供资金支持。本书编辑代表参与这项跨学科研究的同事——他们领导了来自北京大学国家发展研究院、工程学院和光华管理学院的气候变化研究团队——在此衷心感谢各方的慷慨支持。
For logistic support, we would like to thank Peking University Public Policy Forum International, which has hosted many stimulating workshops and seminars on climate change, among others. We are also grateful to Yin Jianhong, Zhao Ting, and Hu Weiyi for administrative support.
对于后勤支持,我们要感谢北京大学国际公共政策论坛,它举办了许多关于气候变化等方面的精彩研讨会。我们还要感谢尹建宏、赵婷和胡唯一提供的行政支持。
Contents
目录
Part I Policy
第一部分 政策
1 Mitigation & Adaptation-China’s Evolving Policy Framework 3
1 减缓与适应——中国不断演变的政策框架 3
Jun Fu, Qiang Zhou, Ruqiang Zou, and Dandan Zhang
傅军、周强、邹如强、张丹丹
2 Drawing Strategic Roadmap of Decarbonization for the Steel Sector 35
2 绘制钢铁行业脱碳战略路线图 35
Jun Fu, Min Wang, and Qimin Cai
傅军、王敏、蔡启民
Part II Technology
第二部分 技术
3 Carbon Capture, Utilization & Storage: A General Overview 61
3 碳捕集、利用与封存:概述 61
Dongxiao Zhang, Ruqiang Zou, Xidong Wang, Jin Liu, and Fanyang Mo
张东晓、邹如强、王西东、刘进、莫凡洋
4 CCUS: What is It? How Does It Cost? Techno-Economic Analysis 109
4 碳捕集、利用与封存:是什么?成本如何?技术经济分析 109
Qianguo Lin, Xi Liang, Ming Lei, Y. M. Zhang, Y. R. Pan, and N. Wang
林乾国、梁希、雷明、张义民、潘耀荣、王娜
Part III Market
第三部分 市场
5 Building Carbon Market in China: Take Stock and Look Ahead . 183
5 中国碳市场建设:总结与展望 183
Jun Fu, Xing Chen, and Jintao Xu
傅军、陈星、徐金涛
6 Design Options of ETS: How to Incentivize CCUS 219
6 排放交易体系的设计选项:如何激励碳捕集、利用与封存 219
Mengfei Jiang, Xi Liang, Ming Lei, Francisco Ascui, Qianguo Lin, Muxin Liu, and Li Wang
蒋梦飞、梁希、雷明、弗朗西斯科·阿斯库伊、林乾国、刘慕鑫、王莉
Part IV Projection
第四部分 预测
7 Achieving Carbon Neutrality by 2060: What (More) Has to Be Done? 249
7 到2060年实现碳中和:还需做些什么?249
Jun Fu, Jintao Xu, Yu Liu, Lunyu Xie, and Shilei Liu
付军、徐锦涛、刘钰、谢伦钰、刘石磊
Correction to: Climate Mitigation and Adaptation in China C1
《中国气候减缓与适应》的更正 C1
Jun Fu, Dongxiao Zhang, and Ming Lei
付军、张东晓、雷明
Index 277
索引 277
About the Editors
关于编辑人员
Jun Fu, Esq., is Professor of Political Economy and Public Policy at the National School of Development, Peking University. He received his Master’s degree and Ph.D. from Harvard University and is the first Chinese to have been elected Foreign Academician of the Bologna Academy of Sciences in its long history. He is the author of Institutions and Investments (Studies in International Economics, the University of Michigan Press), and The Dao of the Wealth of Nations (Peking University Press). Previously, he held faculty positions at the School of Economics and Management, the School of Public Policy and Management, Tsinghua University, and the School of Government, Peking University. He has served, among others, as Member of the Listing Committee of Shenzhen Stock Exchange, Vice Chair of the World Economic Forum’s Global Agenda Council on New Growth Models, and Advisor to Chairman of the Executive Council of UNESCO. As a globally known thought leader, he was twice featured in the Outlook on the Global Agenda (World Economic Forum). Appointed by its Governing Board, he has also served on Visiting Committee for International and Area Studies across Harvard University.
傅军先生是北京大学国家发展研究院政治经济学与公共政策教授。他在哈佛大学获得硕士学位和博士学位,是博洛尼亚科学院悠久历史上首位当选的中国籍外籍院士。他著有《制度与投资》(密歇根大学出版社《国际经济学研究》)以及《国富论之道》(北京大学出版社)。此前,他曾在清华大学经济管理学院、公共政策与管理学院以及北京大学政府管理学院任教。他还曾担任深圳证券交易所上市委员会委员、世界经济论坛全球新增长模式议程理事会副主席以及联合国教科文组织执行局主席顾问。作为全球知名的思想领袖,他两次登上《全球议程展望》(世界经济论坛)。应其理事会任命,他还曾在哈佛大学国际与地区研究访问委员会任职。
Dongxiao Zhang is Chair Professor at College of Engineering, Peking University. An internationally well-known expert in unconventional oil and gas production, groundwater hydrology, and geological carbon sequestration, he had held positions as Senior Scientist at Los Alamos National Laboratory, Miller Chair Professor at the Department of Petroleum and Geological Engineering at the University of Oklahoma, Chair Professor at the University of Southern California, and Executive Dean of Graduate School and Dean of College of Engineering at Peking University. He has published over 220 peer-reviewed papers and authored 2 books, Stochastic Methods for Flow in Porous Media: Coping with Uncertainties (Academic Press), and Theory, Modeling and Field Investigation in Hydrogeology (Geological Society of America). He earned both his Master’s degree and Ph.D. in hydrology and water resources in 1992 and 1993, respectively, from the University of Arizona. He is Member of the U.S. National Academy of Engineering, Honorary Member of Society of Petroleum Engineers, and Fellow of Geological Society of America.
张东晓是北京大学工学院讲席教授。他是国际知名的非常规油气生产、地下水水文学和地质碳封存专家,曾在洛斯阿拉莫斯国家实验室担任高级科学家、俄克拉荷马大学石油与地质工程系米勒讲席教授、南加州大学讲席教授,以及北京大学研究生院执行院长和工学院院长。他发表了220多篇同行评议论文,并著有两本书,《多孔介质中流动的随机方法:应对不确定性》(学术出版社)以及《水文地质学的理论、建模与现场调查》(美国地质学会)。他分别于1992年和1993年在亚利桑那大学获得水文与水资源硕士学位和博士学位。他是美国国家工程院院士、石油工程师协会荣誉会员以及美国地质学会会士。
Ming Lei is Full Professor at Guanghua School of Management, Peking University. He is the author of Green Input-output Accounting: Theory and Application, Green Accounting of China (1992-2002) and Integrated Analysis of China’s Natural Resources-Economy-Environment (1992-2002) (Peking University Press, 2000/2010/2011). He was Associate Professor of Donated Chair by KENSAI Power of Japan, Graduated School of Energy Science, Kyoto University, Japan in 1998, and has held numerous honorary and academic positions, including President elect of Asia Pacific DSI, Senior Expert of Chinese National Green GDP Accounting Project, Fellow of International Sustainable Energy Association (ISEA), Fellow of Chinese Environmental Science Society, Fellow of Chinese Operation Research Society, Fellow of Chinese Environmental and Culture Society, Fellow of Chinese National Accounting Society, and Fellow of Chinese Energy Society. A Member of the Editorial Broad of Economic Science, he is Dean of the Institute on Poverty Research at Peking University and Honorary Professor of the University of Edinburgh.
雷明是北京大学光华管理学院全职教授。他著有《绿色投入产出核算:理论与应用》《中国绿色核算(1992 - 2002)》以及《中国自然资源 - 经济 - 环境综合分析(1992 - 2002)》(北京大学出版社,2000/2010/2011)。1998年,他是日本关西电力捐赠讲席副教授,日本京都大学能源科学研究生院。他担任过众多荣誉和学术职务,包括亚太数据科学学会候任主席、中国国家绿色GDP核算项目高级专家、国际可持续能源协会会士、中国环境科学学会会士、中国运筹学会会士、中国环境与文化学会会士、中国国民经济学会会士以及中国能源学会会士。他是《经济科学》编辑委员会成员,北京大学贫困研究学院院长以及爱丁堡大学荣誉教授。
Abbreviations
缩写
AAUs Assigned Amount Units
AAUs 分配数量单位
BATs Best available technologies
BATs 最佳可用技术
BECCS Bio-Energy CCS
BECCS 生物能源与碳捕获与封存
BFG Blast furnace gas
BFG 高炉煤气
BFs Blast furnaces steelmaking
BFs 高炉炼钢
BOF Basic oxygen furnace
BOF 碱性氧气转炉
CAMU China Association of Metal Scrap Utilization
CAMU 中国金属再生资源协会
CCER China certified emission reduction
CCER 中国核证自愿减排量
CCS Carbon capture and storage
CCS 碳捕获与封存
CCUS Carbon capture, utilization, and storage
CCUS 碳捕获、利用与封存
CCX Chicago Climate Exchange
CCX 芝加哥气候交易所
CDM Clean Development Mechanism
CDM 清洁发展机制
CERs Certified emission reductions
CERs 核证减排量
CNPC China National Petroleum Corporation
CNPC 中国石油天然气集团公司
${\mathrm{{CO}}}_{2}$ Carbon dioxide
${\mathrm{{CO}}}_{2}$ 二氧化碳
${\mathrm{{CO}}}_{2}\mathrm{e}$ Carbon dioxide equivalent
${\mathrm{{CO}}}_{2}\mathrm{e}$二氧化碳当量
${\mathrm{{CO}}}_{2}$ -EOR Enhanced oil recovery
${\mathrm{{CO}}}_{2}$ - 提高采收率的强化采油
CSLF Carbon Sequestration Leadership Forum
碳捕集领导论坛
DAC Direct air capture
直接空气捕获
DICE Dynamic integrated model of climate and the economy
气候与经济动态综合模型
DRI Direct reduce ion
直接还原铁
EAF Electric arc furnace
电弧炉
EC European Commission
欧盟委员会
ECBM Enhanced coal bed methane
强化煤层气
EIA Environmental Impact Assessment
环境影响评估
EIB European Investment Bank
欧洲投资银行
EOR Enhance oil recovery
提高采收率
ERUs Emission reduction units
减排单位
ESA Electric Swing Adsorption
电吸附
ETG Emissions Trading Group
排放交易集团
ETS Emission trading system
排放交易体系
EU ETS EU Emissions Trading System
欧盟排放交易体系(EU ETS)
EU European Union
欧盟(EU)
FFCER Fujian Forestry Certified Emission Reduction
福建林业核证减排量(FFCER)
FYP Five-Year Plan
五年计划(FYP)
GCCSI Global Carbon Capture and Storage Institute
全球碳捕集与封存研究所(GCCSI)
GDP Gross domestic product
国内生产总值(GDP)
GHG Greenhouse gas
温室气体(GHG)
HBFG Hot blast furnace gas
高炉煤气(HBFG)
IEA International Energy Agency
国际能源署(IEA)
IET International Emission Trading
国际排放交易(IET)
IPCC Intergovernmental Panel on Climate Change
政府间气候变化专门委员会(IPCC)
IUCN The International Union for the Conservation of Nature
国际自然保护联盟(IUCN)
JI Joint implementation
联合履行(JI)
KPI Key Performance Indicators
关键绩效指标(KPI)
LDG Linz-Donawitz gas
林茨-多纳维茨煤气(LDG)
LSIPs Large-scale integrated projects
大型综合项目(LSIPs)
MAF Electric arc furnace
MAF 电弧炉
MBA Market-based approach
MBA 基于市场的方法
MEA Mono Ethanol Amine
MEA 单乙醇胺
MEE Ministry of Ecology and Environment
MEE 生态环境部
MEP Ministry of environmental protection
MEP 环境保护部
MIIT Ministry of Industry and Information Technology
MIIT 工业和信息化部
MIRV Monitoring, Reporting and Verification
MIRV 监测、报告与核查
MNR Ministry of Natural Resources
MNR 自然资源部
MOF Ministry of Finance
MOF 财政部
MOST Ministry of Science and Technology
MOST 科学技术部
MOT Ministry of Transport
MOT 交通运输部
MSPE Mean Square Percent Error
MSPE 均方百分比误差
MTCE Million tons of coal equivalent
MTCE 百万吨煤当量
NAP National Allocation Plans
NAP 国家分配计划
NBS Nature-based solutions
NBS 基于自然的解决方案
NCSC National Center for Climate Strategy and International Cooperation
NCSC 国家气候战略与国际合作中心
NDC Nationally determined contributions
国家自主贡献
NDRC National Development and Reform Commission
国家发展和改革委员会
NPC National People’s Congress
全国人民代表大会
NRA National Railway Administration
国家铁路局
NSW National Trust of Australia
澳大利亚国家信托
NTCC National Technical Committee on Carbon Management
全国碳管理标准化技术委员会
PHCER Pu Hui Certified Emission Reduction
普惠制核证减排量
PPA Public Policy Approach
公共政策方法
PSA Pressure Swing Adsorption
变压吸附
RICE Regional dynamic integrated model of climate and the economy
区域气候与经济动态综合模型
SAC Standardization Administration of China
中国国家标准化管理委员会
SACC Strategy Analysis of Climate in China
中国气候战略分析
SFA State Forestry Administration
国家林业局
${\mathrm{{SO}}}_{2}$ Sulphur dioxide
${\mathrm{{SO}}}_{2}$ 二氧化硫
TCE Ton of coal equivalent
吨煤当量
TGRBF Top Gas Recycle of Blast Furnace
高炉炉顶煤气回收
TRT Top Gas Pressure Recovery Turbine
TRT 高炉煤气余压透平发电装置
TSA Temperature Swing Adsorption
TSA 变温吸附
UNFCCC United Nations Framework Convention on Climate Change
UNFCCC 《联合国气候变化框架公约》
VPSA Vacuum Pressure Swing Adsorption
VPSA 真空变压吸附
WTO World Trade Organization
WTO 世界贸易组织
List of Figures
图目录
Chapter 1
第1章
Fig. 1 Output of total economy and industry sector (RMB trillion). Source China Statistical Yearbooks 6
图1 总经济产出和工业部门产出(万亿元人民币)。数据来源:《中国统计年鉴》第6期
Fig. 2 Output of crude steel (million tons). Source Statistical Abstract of China 7
图2 粗钢产量(百万吨)。数据来源:《中国统计摘要》第7期
Fig. 3 Energy consumption in China (coal equivalent, billion tons). Source IEA (2020) 8
图3 中国能源消耗(亿吨标准煤)。数据来源:国际能源署(2020年)第8期
Fig. 4 ${\mathrm{{CO}}}_{2}$ Emissions in China (billion tons). Source Shan et al. (2018, 2020) 8
图4 中国${\mathrm{{CO}}}_{2}$排放(十亿吨)。数据来源:Shan等人(2018年,2020年)第8期
Chapter 2
第2章
Fig. 1 Total Production of Crude Steel (billion tons), 1996-2020 37
图1 1996 - 2020年粗钢总产量(十亿吨)37
Fig. 2 Steel Use (crude steel equivalent, billion tons), 1996-2019 39
图2 1996 - 2019年钢铁使用量(粗钢当量,十亿吨)39
Fig. 3 Energy consumption of Steel in China (Kgce/t), 2000- 2019 (data source China Steel Industry Yearbook) 44
图3 2000 - 2019年中国钢铁能源消耗(千克标准煤/吨)(数据来源:《中国钢铁工业年鉴》)44
Fig. 4 Framework of the SACC model 46
图4 SACC模型框架46
Fig. 5 CO2 Emission Reduction Model for the Steel Sector. Source NCSC 47
图5 钢铁行业二氧化碳减排模型。数据来源:国家气候战略中心47
Fig. 6 Forecasts of ${\mathrm{{CO}}}_{2}$ Reduced by CCUS in China (mtCO2). Sources ADB, Study of China’s Carbon Capture and Storage Demonstration and Promotion Roadmap, 2015; IEA, WEO 2015 Special Report on Energy and Climate Change, 2015; Nie Ligong et al., A Study of the Path to Global Commercialization of CCS Technology, 2016; OECD/IEA, Energy Technology Analysis-Prospects for ${\mathrm{{CO}}}_{2}$ Capture and Storage,2004 52
图6 中国通过碳捕集、利用与封存(CCUS)减少${\mathrm{{CO}}}_{2}$的预测(百万吨二氧化碳)。数据来源:亚洲开发银行,《中国碳捕集与封存示范及推广路线图研究》,2015年;国际能源署,《2015年能源与气候变化特别报告》,2015年;聂立功等人,《碳捕集与封存技术全球商业化路径研究》,2016年;经合组织/国际能源署,《能源技术分析 - ${\mathrm{{CO}}}_{2}$捕集与封存前景》,2004年52
Fig. 7 A phased CCUS Policy Roadmap for Steel Sector 54
图7 钢铁行业分阶段碳捕集、利用与封存(CCUS)政策路线图54
Chapter 3
第3章
Fig. 1 Main technological processes in producing steel 62
图1 钢铁生产的主要工艺流程62
Fig. 2 Cost and capacity for transportation alternatives at ${250}\mathrm{\;{km}}$ (Sevensson et al., 2004) 83
图2 ${250}\mathrm{\;{km}}$(Sevensson等人,2004年)的运输替代方案成本和容量 83
Fig. 3 The ${\mathrm{{CO}}}_{2}$ transport chain (Modified from Aspelund & Jordal, 2007) 86
图3 ${\mathrm{{CO}}}_{2}$运输链(改编自Aspelund和Jordal,2007年) 86
Fig. 4 Construction costs for pipelines from various information sources. Costs exclude booster stations (Metz, 2005) 86
图4 来自各种信息源的管道建设成本。成本不包括增压站(Metz,2005年) 86
Fig. 5 Levelized cost of pipeline transport from various information sources (Metz, 2005) 88
图5 来自各种信息源的管道运输平准化成本(Metz,2005年) 88
Fig. 6 Comparison of costs of onshore and offshore pipelines, and ship transport (Metz, 2005) 89
图6 陆上和海上管道成本与船舶运输成本的比较(Metz,2005年) 89
Fig. 7 Trapping mechanisms evolution with time (Modified from Metz et al., 2005) 91
图7 捕集机制随时间的演变(改编自Metz等人,2005年) 91
Fig. 8 Different kinds of appropriate ${\mathrm{{CO}}}_{2}$ storage sites (Modified from Benson & Cole, 2008) 93
图8 不同类型的合适${\mathrm{{CO}}}_{2}$储存地点(改编自Benson和Cole,2008年) 93
Chapter 4
第4章
Fig. 1 Coke oven gas purification system 113
图1 焦炉煤气净化系统 113
Fig. 2 Principle of chemical absorption method 121
图2 化学吸收法原理 121
Fig. 3 Schematic principle of membrane separation ${\mathrm{{CO}}}_{2}$ 124
图3 膜分离${\mathrm{{CO}}}_{2}$的原理图 124
Chapter 5
第5章
Fig. 1 ETS Pilots in China: Transaction Threshold and Reporting Threshold. Note 1. Data. Source Websites of local DRC in 7 regional ETS pilots; 2. Reporting emissions of Chongqing is unavailable 189
图1 中国的碳排放交易体系试点:交易门槛和报告门槛。注1.数据来源为7个区域碳排放交易体系试点的当地发改委网站;2.重庆的报告排放量不可用 189
Fig. 2 Share of trading volume/trading turnover. Data source http://k.tanjiaoyi.com/ 196
图2 交易量/交易成交额份额。数据来源http://k.tanjiaoyi.com/ 196
Fig. 3 Trends of emission permit trading in China. Data source http://k.tanjiaoyi.com/ 197
图3 中国排放许可交易趋势。数据来源http://k.tanjiaoyi.com/ 197
Fig. 4 ${\mathrm{{CO}}}_{2}$ emissions between Hubei and synthetic Hubei 204
图4 湖北与合成湖北之间的${\mathrm{{CO}}}_{2}$排放 204
Fig. 5 ${\mathrm{{CO}}}_{2}$ emissions of polluting industries between Hubei and synthetic Hubei 205
图5 205年湖北与合成湖北之间污染行业的${\mathrm{{CO}}}_{2}$排放
Fig. 6 ${\mathrm{{CO}}}_{2}$ emissions between Guangdong and synthetic Guangdong 206
图6 广东与合成广东之间的${\mathrm{{CO}}}_{2}$排放 206
Fig. 7 ${\mathrm{{CO}}}_{2}$ Emissions between Tianjin and synthetic Tianjin 206
图7 天津与合成天津之间的${\mathrm{{CO}}}_{2}$排放 206
Fig. 8 ${\mathrm{{CO}}}_{2}$ emissions between Beijing and synthetic Beijing 207
图8 北京与合成北京之间的${\mathrm{{CO}}}_{2}$排放 207
Fig. 9 ${\mathrm{{CO}}}_{2}$ emissions between Shanghai and synthetic Shanghai 208
图9 上海与合成上海之间的${\mathrm{{CO}}}_{2}$排放 208
Fig. 10 Placebo test 209
图10 安慰剂检验 209
Fig. 11 ${\mathrm{{CO}}}_{2}$ emissions between Chongqing and synthetic Chongqing 215
图11 重庆与合成重庆之间的${\mathrm{{CO}}}_{2}$排放 215
Chapter 6
第6章
Fig. 1 Operation mechanism of ETS 221
图1 碳排放交易体系的运行机制 221
Chapter 7
第7章
Fig. 1 Energy intensity: China, Germany, US, Japan and India (1990-2015). Source World Bank. Unit: MJ/$2011 PPP GDP 257
图1 能源强度:中国、德国、美国、日本和印度(1990 - 2015年)。数据来源:世界银行。单位:兆焦/2011年购买力平价美元GDP 257
Fig. 2 Share of Renewable Energy: China, Germany, US, Japan and India (1990-2015). Source World Bank Unit: % 257
图2 可再生能源占比:中国、德国、美国、日本和印度(1990 - 2015年)。数据来源:世界银行。单位:% 257
Fig. 3 ${\mathrm{{CO}}}_{2}$ emissions in China (2020-2060) by various scenarios of energy efficiency improvement (Unit: 0.1 billion tons) Note: A1 energy efficiency increase by 0.5%/year, A2 energy efficiency increase by 1%/year, A3 energy efficiency increase by 1.5%/year, A4 energy efficiency increase by $2\% /$ year, A5 energy efficiency increase by ${2.5}\% /$ year, A6 energy efficiency increase by $3\% /$ year 265
图3 中国在不同能源效率提升情景下的${\mathrm{{CO}}}_{2}$排放(2020 - 2060年)(单位:0.1亿吨) 注:A1能源效率每年提升0.5%,A2能源效率每年提升1%,A3能源效率每年提升1.5%,A4能源效率每年提升$2\% /$,A5能源效率每年提升${2.5}\% /$,A6能源效率每年提升$3\% /$ 265
Fig. 4 ${\mathrm{{CO}}}_{2}$ Emissions in China (2020-2060) by various scenarios of renewable energy cost reduction (Unit: 0.1 billion tons) Note: R1 Cost of renewable energy decreases rapidly, R2 Cost of renewable energy decreases slowly 265
图4 中国在不同可再生能源成本降低情景下的${\mathrm{{CO}}}_{2}$排放(2020 - 2060年)(单位:0.1亿吨) 注:R1可再生能源成本快速下降,R2可再生能源成本缓慢下降 265
Fig. 5 ${\mathrm{{CO}}}_{2}$ Emissions in China (2020-2060) by various scenarios of carbon pricing (Unit: 0.1 billion tons). Note T1 $100/tCO2 in 2060, T2 $200/tCO2 in 2060, T3 $300/tCO2 in 2060, T4 $400/tCO2 in 2060, T5 $500/tCO2 in 2060, and T6 $600/tCO2 in 2060 266
图5 中国在不同碳定价情景下的${\mathrm{{CO}}}_{2}$排放(2020 - 2060年)(单位:0.1亿吨)。注:T1 2060年为100美元/吨二氧化碳,T2 2060年为200美元/吨二氧化碳,T3 2060年为300美元/吨二氧化碳,T4 2060年为400美元/吨二氧化碳,T5 2060年为500美元/吨二氧化碳,T6 2060年为600美元/吨二氧化碳 266
Fig. 6 ${\mathrm{{CO}}}_{2}$ Emissions in China (2020-2060) by various scenarios of policy portfolios (Unit: 0.1 billion tons). Note As an example, R1A6T6 indicates a combination of policy R1, A6 and T6 267
图6 中国在不同政策组合情景下的${\mathrm{{CO}}}_{2}$排放(2020 - 2060年)(单位:0.1亿吨)。注:例如,R1A6T6表示政策R1、A6和T6的组合 267
Fig. 7 Energy Structure in China in 2060 by various scenarios of policy portfolios (Unit: %) 268
图7 2060年中国在不同政策组合情景下的能源结构(单位:%) 268
Fig. 8 Tradeoff between ${\mathrm{{CO}}}_{2}$ Emission and GDP Loss in China in 2060, by various scenarios of policy portfolios Note Blue dot represents some one policy portfolio 268
图8 2060年中国在不同政策组合情景下${\mathrm{{CO}}}_{2}$排放与GDP损失之间的权衡 注:蓝点代表某一种政策组合 268
Fig. 9 Impact of policy portfolios on macroeconomic variables in China in 2060 269
图9 政策组合对2060年中国宏观经济变量的影响 269
List of Tables
表格列表
Chapter 1
第1章
Key elements of climate policy framework in China 10
中国气候政策框架的关键要素10
Table 2 Key targets of FYPs 14
表2 五年规划的主要目标14
Table 3 CCUS Regulatory Framework in Major region/countries 24
表3 主要地区/国家的碳捕集、利用与封存(CCUS)监管框架24
Table 4 Policy Framework for CCUS development in China 27
表4 中国CCUS发展的政策框架27
Chapter 2
第2章
Table 1 Forecasts of ${\mathrm{{CO}}}_{2}$ reduced by CCUS in China (mtCO2) 50
表1 中国通过CCUS减少的${\mathrm{{CO}}}_{2}$预测(百万吨二氧化碳)50
Table 2 ${\mathrm{{CO}}}_{2}$ Reduction potential of CCUS in the steel sector 51
表2 钢铁行业CCUS的${\mathrm{{CO}}}_{2}$减排潜力51
Chapter 3
第3章
Table 1 Transportation of global large-scale CCS project in operation. Adapted from GCCSI (2017b) 85
表1 全球运行中的大型碳捕集与封存(CCS)项目运输情况。改编自全球碳捕集与封存协会(GCCSI,2017b)85
Table 2 Primary capture and storage type of global large-scale CCS project in operation. Adapted from GCCSI (2017b) 98
表2 全球运行中的大型CCS项目的主要捕集和封存类型。改编自全球碳捕集与封存协会(GCCSI,2017b)98
Chapter 4
第4章
Table 1 Flue gas composition of #4 Lime Kiln in Shougang Jingtang 112
表1 首钢京唐4号石灰窑的烟气成分112
Table 2 Composition of typical coke oven gas 113
表2 典型焦炉煤气的成分113
Table 3 Operating condition at TRT inlet and outlet 114
表3 透平式余热回收装置(TRT)进出口运行条件114
Table 4 BFG composition of typical iron/steel plant in China 115
表4中国典型钢铁厂的高炉煤气成分115
Table 5 Composition of typical LDG 117
表5典型转炉煤气成分117
Table 6 Composition of typical hot blast furnace flue gas 118
表6典型热风炉烟气成分118
Table 7 Characteristics of ${\mathrm{{CO}}}_{2}$ separation technologies 127
表7 ${\mathrm{{CO}}}_{2}$分离技术的特点127
Table 8 Composition of typical blast furnace gas in China 130
表8中国典型高炉煤气成分130
Table 9 Technical applicability of technologies for industrial grade ${\mathrm{{CO}}}_{2}$ from BFG prior to TRT 133
表9 TRT之前从高炉煤气中获取工业级${\mathrm{{CO}}}_{2}$的技术的技术适用性133
Table 10 Technical applicability of technologies for storage Grade ${\mathrm{{CO}}}_{2}$ from BFG prior to TRT 135
表10 TRT之前从高炉煤气中获取储存级${\mathrm{{CO}}}_{2}$的技术的技术适用性135
Table 11 Economic performance of technologies for industrial grade above ${\mathrm{{CO}}}_{2}$ capture from BFG before TRT (at capture rate of ${90}\%$ ) 137
表11 TRT之前从高炉煤气中捕获高于${\mathrm{{CO}}}_{2}$的工业级的技术的经济性能(捕获率为${90}\%$)137
Table 12 Economic performance of capture ${\mathrm{{CO}}}_{2}$ of storage grade from BFG before TRT (at 90% capture rate) 138
表12 TRT之前从高炉煤气中捕获储存级${\mathrm{{CO}}}_{2}$的经济性能(捕获率为90%)138
Economic performance of technologies for industrial grade ${\mathrm{{CO}}}_{2}$ capture from BFG after TRT (capture rate of 90%) 144
TRT之后从高炉煤气中捕获工业级${\mathrm{{CO}}}_{2}$的技术的经济性能(捕获率为90%)144
Economic of capture ${\mathrm{{CO}}}_{2}$ of storage grade from BFG before TRT (90% capture rate) 146
TRT之前从高炉煤气中捕获储存级${\mathrm{{CO}}}_{2}$的经济性(捕获率为90%)146
Caloric value benefit of ${\mathrm{{CO}}}_{2}$ capture from BFG under different capture rate 149
不同捕获率下从高炉煤气中捕获${\mathrm{{CO}}}_{2}$的热值效益149
Technical performance of capture methods for industrial grade ${\mathrm{{CO}}}_{2}$ from LKFG 150
从转炉煤气中捕获工业级${\mathrm{{CO}}}_{2}$的捕获方法的技术性能150
Technical performance of capture methods for storage grade ${\mathrm{{CO}}}_{2}$ from LKFG 153
从转炉煤气中捕获储存级${\mathrm{{CO}}}_{2}$的捕获方法的技术性能153
Economic performance of technologies for industrial grade from LKFG (at capture rate of 90%) 155
从转炉煤气中获取工业级的技术经济性能(捕获率为90%)155
Economic performance of technologies for storage grade from LKFG (at capture rate of 90%) 156
从转炉煤气中获取储存级的技术经济性能(捕获率为90%)156
Composition of typical hot blast furnace flue gas in China 157
中国典型热风炉烟气成分157
Technical performance of technologies for hot blast furnace flue gas 159
热风炉烟气处理技术的技术性能159
Economic performance of technologies for industrial grade from hot blast furnace flue gas (at capture rate of 90%) 161
工业级热风炉烟气处理技术的经济性能(捕集率90%)161
Table 23 Economic performance of technologies for storage grade from hot blast furnace flue gas (at capture rate of 90%) 162
表23 储存级热风炉烟气处理技术的经济性能(捕集率90%)162
Table 24 le 24 Technical performance of technologies for Linz-Donawitz gas before cabinet 165
表24 转炉煤气柜前转炉煤气处理技术的技术性能165
List of Tables
表格列表
Technical performance of technologies for industry grade ${\mathrm{{CO}}}_{2}$ from Linz-Donawitz gas after cabinet 166
转炉煤气柜后工业级${\mathrm{{CO}}}_{2}$转炉煤气处理技术的技术性能166
Table 26 Technical performance of technologies for storage grade ${\mathrm{{CO}}}_{2}$ from Linz-Donawitz Gas after cabinet 168
表26 转炉煤气柜后储存级${\mathrm{{CO}}}_{2}$转炉煤气处理技术的技术性能168
Table 27 Economic performance of technologies for industrial grade ${\mathrm{{CO}}}_{2}$ from Linz-Donawitz gas after cabinet (at capture rate of 90%) 171
表27 转炉煤气柜后工业级${\mathrm{{CO}}}_{2}$转炉煤气处理技术的经济性能(捕集率90%)171
Table 28 Economic performance of capture ${\mathrm{{CO}}}_{2}$ of storage grade after Linz-Donawitz Gas after cabinet (90% capture rate) 172
表28 转炉煤气柜后储存级${\mathrm{{CO}}}_{2}$转炉煤气捕集的经济性能(捕集率90%)172
Chapter 5
第5章
Table 1 Policy framework of regional ETS pilots in China 187
表1 中国区域碳排放交易体系试点政策框架187
Table 2 China’s regional ETS pilots in operation 190
表2 中国已运行的区域碳排放交易体系试点190
Table 3 ETS Pilots: trading indicators 195
表3 碳排放交易体系试点:交易指标195
Table 4 Economic features of real pilots versuss synthetic pilots 201
表4 真实试点与模拟试点的经济特征201
Table 5 Synthetic weight for synthetic pilots 202
表5 模拟试点的模拟权重202
Chapter 6
第6章
Table 1 Sectoral coverage of pilot ETSs (2018) 223
表1 试点碳排放交易体系的行业覆盖范围(2018年)223
Table 2 Offsets regulations in China’s pilot ETSs 226
表2 中国试点碳排放交易体系中的抵消规定226
Table 3 Comparison of 3 design options of ETS 238
表3 碳排放交易体系三种设计方案的比较238
Table A1: GHG accounting guidelines for iron/steel industry in China (NDRC, 2013a) 240
表A1:中国钢铁行业温室气体核算指南(国家发展和改革委员会,2013a)240
Chapter 7
第7章
Table 1 Single PPA scenarios 262
表1 单一购电协议情景262
Table 2 Composite PPA Scenarios 263
表2 复合购电协议情景263
Part I
第一部分
Policy
政策
Mitigation & Adaptation-China’s Evolving Policy Framework
减缓与适应——中国不断演变的政策框架
Jun Fu, Qiang Zhou, Ruqiang Zou, and Dandan Zhang
傅军、周强、邹如强、张丹丹
Climate change caused by anthropogenic greenhouse gas (GHG) ${}^{1}$ emissions from industrialization is a global challenge. The 2015 Paris Agreement represents a global action plan to set the world on track to avoid dangerous climate change by limiting global warming to well below $2{}^{ \circ }\mathrm{C}$ above pre-industrial levels in the long-term, and to pursue best efforts to limit the increase in warming to ${1.5}{}^{ \circ }\mathrm{C}$ . To achieve the goal, the Paris Agreement underscored the need for global GHG emissions to peak as soon as possible and for the contracting states to the Agreement to undertake rapid carbon emission reductions with best available technologies (BATs).
工业化过程中人为温室气体(GHG)${}^{1}$排放导致的气候变化是一项全球性挑战。《2015年巴黎协定》是一项全球行动计划,旨在让世界走上正轨,通过将全球变暖长期限制在远低于工业化前水平$2{}^{ \circ }\mathrm{C}$以上,来避免危险的气候变化,并尽最大努力将升温幅度限制在${1.5}{}^{ \circ }\mathrm{C}$以内。为实现这一目标,《巴黎协定》强调全球温室气体排放需尽快达峰,协定缔约国需采用最佳可用技术(BATs)迅速减少碳排放。
${}^{1}$ Gases that trap heat in the atmosphere are called greenhouse gases. Global GHG emissions due to human activities primarily consist of Carbon dioxide $\left( {\mathrm{{CO}}}_{2}\right)$ , Methane $\left( {\mathrm{{CH}}}_{4}\right)$ , and Nitrous oxide $\left( {{\mathrm{N}}_{2}\mathrm{O}}\right)$ . These three types of gases represent ${76}\% ,{16}\%$ and $6\%$ of total global GHG emissions respectively. In 2017, for example, global GHG emissions was 50.9 gigatons in ${\mathrm{{CO}}}_{2}$ equivalent. See U.S. Environmental Protection Agency and PBL Netherlands Environmental Assessment Agency.
${}^{1}$在大气中捕获热量的气体被称为温室气体。人类活动产生的全球温室气体排放主要包括二氧化碳$\left( {\mathrm{{CO}}}_{2}\right)$、甲烷$\left( {\mathrm{{CH}}}_{4}\right)$和一氧化二氮$\left( {{\mathrm{N}}_{2}\mathrm{O}}\right)$。这三种气体分别占全球温室气体排放总量的${76}\% ,{16}\%$和$6\%$。例如,2017年,全球温室气体排放总量为509亿吨${\mathrm{{CO}}}_{2}$当量。见美国环境保护局和荷兰环境评估局(PBL)。
The original version of this chapter was revised: A sentence has been added on page 29. The correction to this chapter can be found at https://doi.org/10.1007/978-981-16-4310-1_8.
本章的原始版本已修订:第29页新增了一句话。本章的勘误可在https://doi.org/10.1007/978-981-16-4310-1_8查询。
J. Fu $\left( \infty \right) \cdot$ D. Zhang
傅军$\left( \infty \right) \cdot$张丹丹
National School of Development, Peking University, Beijing, China
中国北京北京大学国家发展研究院
Q. Zhou
周强
School of Government, Peking University, Beijing, China
中国北京北京大学政府管理学院
R. Zou
邹如强
College of Engineering, Peking University, Beijing, China
中国北京北京大学工学院
Due to its large population (1.4 billion people) and rapid economic growth in the midst of industrialization, currently China is the largest ${\mathrm{{CO}}}_{2}$ emitter in the world, contributing more than a quarter of global carbon emissions. But China has been working hard at mitigation and adaptation to climate change with its increasingly progressive international commitments to reduce ${\mathrm{{CO}}}_{2}$ emissions, which in turn have facilitated its domestic agenda setting for developing a low-carbon and green economy. In the past two decades, there have been three milestone announcements of China’s green pledge to the international community. In 2009, during the Copenhagen Climate Change Conference, China pledged to cut ${\mathrm{{CO}}}_{2}$ emissions per unit of GDP by 40-45% by 2020 from the 2005 level-a commitment that China has achieved by the end of 2019. ${}^{2}$ In 2015, during the Paris Climate Change Conference, China again committed to peak carbon emissions around 2030 and reduced carbon intensity of GDP by 60-65% by 2030 from the 2005 level. In 2020, at the General Debate of the 75th Session of the UN General Assembly, Chinese President Xi Jinping pledged again that China will peak its carbon emissions prior to [emphasis added] 2030, ${}^{3}$ and become carbon neutral by 2060.
由于人口众多(14亿)且处于工业化进程中的经济快速增长,目前中国是世界上最大的${\mathrm{{CO}}}_{2}$排放国,贡献了超过全球四分之一的碳排放。但中国一直在努力减缓与适应气候变化,其对减少${\mathrm{{CO}}}_{2}$排放的国际承诺日益进步,这反过来也推动了其国内发展低碳绿色经济的议程设定。在过去二十年里,中国向国际社会做出了三次具有里程碑意义的绿色承诺。2009年,在哥本哈根气候变化大会期间,中国承诺到2020年单位GDP的${\mathrm{{CO}}}_{2}$排放比2005年水平降低40 - 45%,中国已于2019年底实现了这一承诺。${}^{2}$2015年,在巴黎气候变化大会期间,中国再次承诺到2030年左右实现碳排放达峰,并到2030年将GDP的碳强度比2005年水平降低60 - 65%。2020年,在联合国大会第75届会议一般性辩论上,中国国家主席习近平再次承诺,中国将在2030年前[重点添加]实现碳排放达峰,${}^{3}$并在2060年前实现碳中和。
The aim of this chapter is to outline the evolution of China’s policy or regulatory framework to de-carbonize its economy. It does so through the prism of the steel sector and with a special attention to the emerging technology of carbon capture, utilization and storage (CCUS). Where relevant, international comparisons are also made so that we have a sense of where China stands now in terms of both policy and technology for green growth.
本章旨在概述中国使经济脱碳的政策或监管框架的演变。通过钢铁行业这一视角进行阐述,并特别关注碳捕获、利用与封存(CCUS)这一新兴技术。在相关情况下,还会进行国际比较,以便我们了解中国在绿色增长的政策和技术方面目前所处的位置。
The rest of this chapter is organized as follows: Section 1 presents a brief overview of China’s industrial growth, including the steel sector, in the past 2-3 decades, in terms of growth trends, energy consumption and carbon emissions. Section 2 discusses China’s policy framework to decarbonize the industry. In the process, we will identify the key government departments tasked with shaping the country’s strategy for sustainable economic and social development. Section 3 puts China in international perspective in connection with CCUS—an emerging technology increasingly recognized as having great potentials for direct abatement of ${\mathrm{{CO}}}_{2}$ emissions (Global CCS Institute,2015). Section 4 concludes by a brief review on China’s CCUS developments in terms of both policy and practice.
本章其余部分的结构如下:第1节简要概述了中国过去二三十年的工业增长情况,包括钢铁行业,涉及增长趋势、能源消耗和碳排放。第2节讨论了中国工业脱碳的政策框架。在此过程中,我们将确定负责制定国家可持续经济和社会发展战略的关键政府部门。第3节将中国置于与碳捕集、利用与封存(CCUS)相关的国际视角下——这是一种日益被认为在直接减排${\mathrm{{CO}}}_{2}$排放方面具有巨大潜力的新兴技术(全球CCS研究所,2015年)。第4节通过对中国CCUS在政策和实践方面的发展进行简要回顾来得出结论。
${}^{2}$ By the end of 2019, the reduction was 48.1%, and non-fossil fuels as a share of energy structure reached 15.3%.
${}^{2}$ 到2019年底,降幅为48.1%,非化石能源在能源结构中的占比达到15.3%。
${}^{3}$ To achieve this goal, it means that carbon intensity has to go down by 60-65%, non-fossil fuels as a share of energy structure have to go up to ${20}\%$ ; and forest sink has to increase by 4.5 billion square meters from the 2005 level.
${}^{3}$ 为实现这一目标,这意味着碳强度必须下降60 - 65%,非化石能源在能源结构中的占比必须提高到${20}\%$;森林碳汇必须比2005年水平增加45亿平方米。
1 Section 1
1 第1节
1.1 Chinese Industrial Sectors
1.1 中国工业部门
Since economic reforms and opening-up initiated in 1978, China has been growing at almost double-digit rates for many years, which was fueled by the fast growth of the industrial sector. By 2011, the China’s total output of over 220 industrial products among 500 major ones were in the first place of the world. That would make China the world’s largest industrial country. In terms of the industrial structure, the second industry had long been in the dominate position before it was overtaken by the tertiary industry in 2012. During China’s 11th Five-Year Plan (FYP) (2006-2010), the ratio of heavy to light industries was 7:3, significantly higher than the current level and even surpass the highest level of many developed countries. ${}^{4}$
自1978年改革开放以来,中国多年来一直保持着近两位数的增长速度,这得益于工业部门的快速发展。到2011年,中国500种主要工业产品中的220多种产品的总产量位居世界第一。这使中国成为世界上最大的工业国家。在产业结构方面,第二产业在2012年被第三产业超越之前长期占据主导地位。在中国“十一五”规划(2006 - 2010年)期间,重工业与轻工业的比例为7:3,显著高于当前水平,甚至超过了许多发达国家的最高水平。${}^{4}$
The secondary industry of China has been fueled by the rapid urbanization process in China. The urbanization rate of China was about ${18}\%$ in the late 1970s, it has reached 64% in 2020. Since the mid-1990s, heavy industries-automobiles, petrochemicals, and heavy-duty equipment, etc. -received massive government support at both the national and the local levels, reflecting China’s industrial policy at that time. After the worldwide financial crisis in 2008, however, the Chinese economy has been slowing down, and eventually entered a new period of which Chinese President Xi Jinping called the “New Normal”. ${}^{5}$ With the “New Normal”, real GDP growth rate of China has dropped dramatically-from an average of 10.76% in 2003-2011 to 7.2% in 2012-2017 (National Bureau of Statistics, 2018). Despite the growth of industrial value added has slow down, the industrial sector has remained its original scale in China. In 2020, the value added of the secondary industry was RMB 38,404 billion, accounting for 37.8% of China’s GDP (Fig. 1).
中国的第二产业受到中国快速城市化进程的推动。中国的城市化率在20世纪70年代末约为${18}\%$,到2020年已达到64%。自20世纪90年代中期以来,重工业——汽车、石化和重型设备等——在国家和地方层面都获得了大量政府支持,这反映了当时中国的产业政策。然而,2008年全球金融危机之后,中国经济开始放缓,并最终进入了中国国家主席习近平所称的“新常态”的新阶段。${}^{5}$ 随着“新常态”的到来,中国实际国内生产总值增长率大幅下降——从2003 - 2011年的平均10.76%降至2012 - 2017年的7.2%(国家统计局,2018)。尽管工业增加值的增长有所放缓,但中国工业部门的规模仍保持不变。2020年,第二产业增加值为38.404万亿元,占中国国内生产总值的37.8%(图1)。
${}^{4}$ Starting in 2013, the National Bureau of Statistics (NBS) of China no longer uses light industries or heavy industries categorization. Instead, NBS uses a classification system that conforms to ISIC. See http://www.stats.gov.cn/tjsj/zxfb/201402/t20140224_514970.html.
${}^{4}$ 从2013年开始,中国国家统计局不再使用轻工业或重工业分类。相反,国家统计局采用了符合国际标准产业分类(ISIC)的分类系统。见http://www.stats.gov.cn/tjsj/zxfb/201402/t20140224_514970.html。
${}^{5}$ The term “new normal” first came to public discourse during President Xi Jinping’s visit to Henan in May 2014. Under the “new normal”, the importance of growth speed is eclipsed by immensely complex structural reforms to transform the economy to one that relies more on the services sector, domestic spending and innovation, than manufacturing and exports. http://www.aisixiang.com/zhuanti/175.html.
${}^{5}$ “新常态”一词首次出现在公众话语中是在2014年5月习近平主席访问河南期间。在“新常态”下,增长速度的重要性被极其复杂的结构改革所掩盖,这些改革旨在将经济转变为更多依赖服务业、国内消费和创新,而非制造业和出口的经济。http://www.aisixiang.com/zhuanti/175.html。
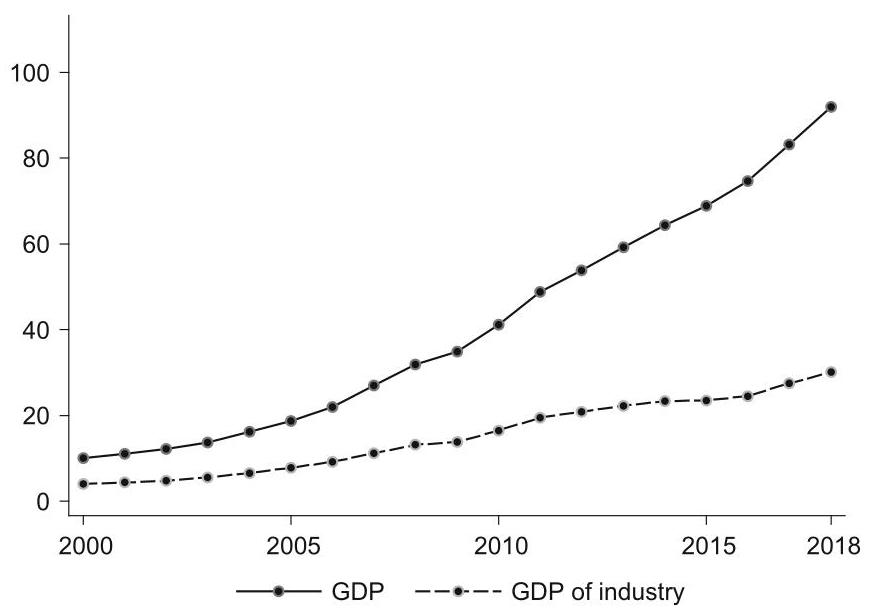
Fig. 1 Output of total economy and industry sector (RMB trillion). Source China Statistical Yearbooks
图1 经济总量和工业部门产出(万亿元人民币)。来源:《中国统计年鉴》
1.2 The Steel Sector
1.2 钢铁行业
The steel sector plays an important role in the Chinese economy. China has been the world’s largest iron and steel producer since 1996. Crude steel production was 1.6 million tons in 1949 (when the People’s Republic of China was established), it surged to 804 million tons in 2015; on per capita basis, China reached ${586}\mathrm{\;{kg}}$ of steel production, about 2.6 times the world’s average, next only to South Korea. In the fleet of China’s iron and steel plants, huge disparities existed in production capacity, energy-saving technology, and product structure. Yet long-process iron/steel production remains the mainstream, whereas short-process steelmaking accounts for only about ${10}\% {.}^{6}$ Compared with the United States, the share of electric arc furnaces (EAF)—a short-process steel production—was 68% in 2018. ${}^{7}$ (Fig. 2).
钢铁行业在中国经济中发挥着重要作用。自1996年以来,中国一直是世界上最大的钢铁生产国。1949年(中华人民共和国成立时)粗钢产量为160万吨,到2015年激增至8.04亿吨;按人均计算,中国的钢铁产量达到${586}\mathrm{\;{kg}}$,约为世界平均水平的2.6倍,仅次于韩国。在中国的钢铁厂中,产能、节能技术和产品结构存在巨大差异。然而,长流程钢铁生产仍然是主流,而短流程炼钢仅占约${10}\% {.}^{6}$。与美国相比,2018年短流程钢铁生产——电弧炉(EAF)的占比为68%。${}^{7}$(图2)。
The impact of the “New Normal” was tremendous on the China’s industrial sector, in particular on the steel sector-a topic that we will pick up and discuss further in Chapter 2. We emphasize here that the steel sector had confronted severe overcapacity issues. Capacity utilization rate in the steel sector fell from 88.7% in in 2006 to 64.8% in 2015. Since then, like many other resource- and energy-intensive industries, e.g., power and cement, the steel sector has been pushed hard to shift towards a quality-over-quantity and a low-carbon development path. Initial upgrading results were remarkable. Energy consumption per ton of crude steel produced decreased significantly from 605 to 527 kgce (kilograms of coal equivalent) during the 12th FYP (2011-2015), indicating a great improvement in terms of energy efficiency.
“新常态” 对中国工业部门产生了巨大影响,尤其是对钢铁行业——我们将在第二章进一步探讨这个话题。我们在此强调,钢铁行业曾面临严重的产能过剩问题。钢铁行业的产能利用率从2006年的88.7%降至2015年的64.8%。自那时起,与许多其他资源和能源密集型行业(如电力和水泥)一样,钢铁行业被大力推动转向质量优先和低碳发展道路。初步升级成果显著。在第十二个五年规划(2011 - 2015年)期间,每吨粗钢的能源消耗从605千克标准煤大幅降至527千克标准煤,这表明能源效率有了很大提高。
${}^{6}$ There are two processes in iron and steel production: a long process and a short process. The main difference is that the long process takes iron ore and coke as the main raw materials, melts them and then converts them to steel; while the short process uses scrap steel as a raw material to melt steel. More on iron/steel making will be discussed in Chapters 3 and 4 of this study.
${}^{6}$钢铁生产有两种工艺:长流程和短流程。主要区别在于,长流程以铁矿石和焦炭为主要原料,将它们熔化后再转化为钢;而短流程则以废钢为原料来熔化钢。本研究的第3章和第4章将进一步讨论钢铁制造。
7 World Steel in Figs. 2019, World Steel Association.
7 2019年《世界钢铁数据》,世界钢铁协会。
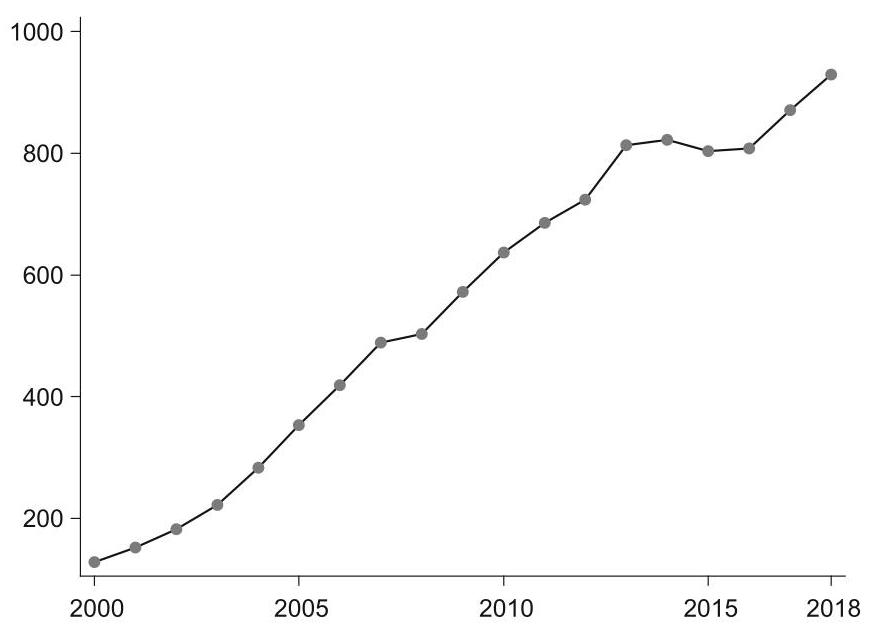
Fig. 2 Output of crude steel (million tons). Source Statistical Abstract of China
图2粗钢产量(百万吨)。来源:《中国统计摘要》
1.3 Energy Consumption and ${\mathrm{{CO}}}_{2}$ Emissions
1.3 能源消耗与${\mathrm{{CO}}}_{2}$排放
In China, fossil fuels are still the primary source for energy and raw material supply utilized in the industrial sector such as power, cement, steel, petrochemicals, and etc.. Among various industrial activities, the iron/steel sector is one of the most energy- and coal-intensive sectors and emits a large amount of ${\mathrm{{CO}}}_{2}$ into the atmosphere, accounting for about ${15}\%$ of total industrial ${\mathrm{{CO}}}_{2}$ emissions in China, and about 60% of carbon emissions from global steel industries. When further breaking iron/steel sector down to detailed sectors, the power, steel and cement sectors in total represent over 75% of carbon emissions in China, generating ${45}\% ,{15}\%$ , and ${15}\%$ carbon emissions, respectively.
在中国,化石燃料仍是工业部门(如电力、水泥、钢铁、石化等)能源和原材料供应的主要来源。在各类工业活动中,钢铁行业是能源和煤炭密集度最高的行业之一,向大气中排放大量的${\mathrm{{CO}}}_{2}$,约占中国工业${\mathrm{{CO}}}_{2}$排放总量的${15}\%$,占全球钢铁行业碳排放的60%左右。将钢铁行业进一步细分为具体行业时,电力、钢铁和水泥行业的碳排放总量占中国碳排放总量的75%以上,分别产生${45}\% ,{15}\%$和${15}\%$的碳排放。
The increasing trends of energy consumption in China for the total economy, the industrial sector, and the steel sector are shown in Fig. 3.
图3展示了中国经济总体、工业部门和钢铁部门能源消耗的增长趋势。
Additionally, Fig. 4 depicts the trends of ${\mathrm{{CO}}}_{2}$ emissions in China for the total economy, the industrial sector and the steel sector.
此外,图4描绘了中国经济总体、工业部门和钢铁部门的${\mathrm{{CO}}}_{2}$排放趋势。
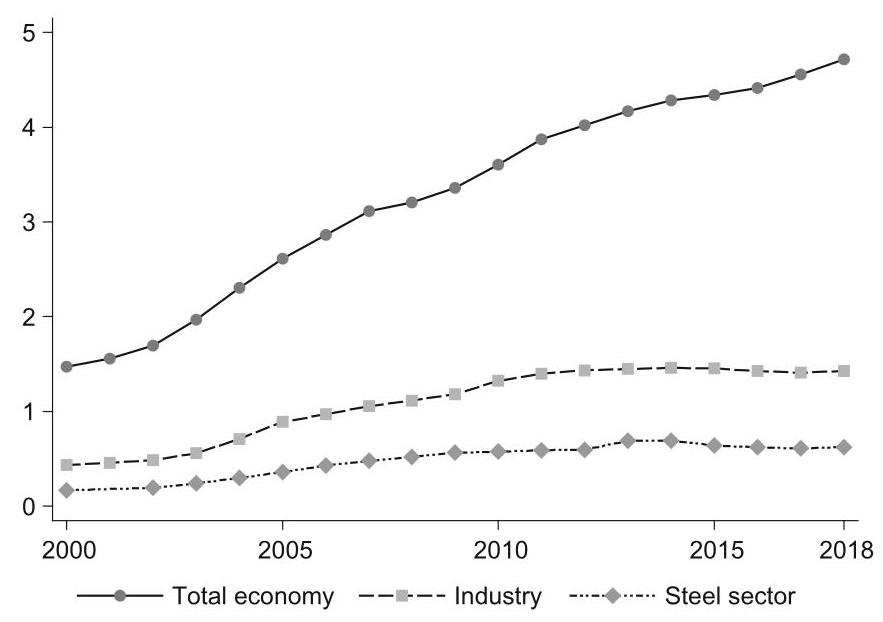
Fig. 3 Energy consumption in China (coal equivalent, billion tons). Source IEA (2020)
图3 中国的能源消耗(亿吨标准煤)。来源:国际能源署(2020年)
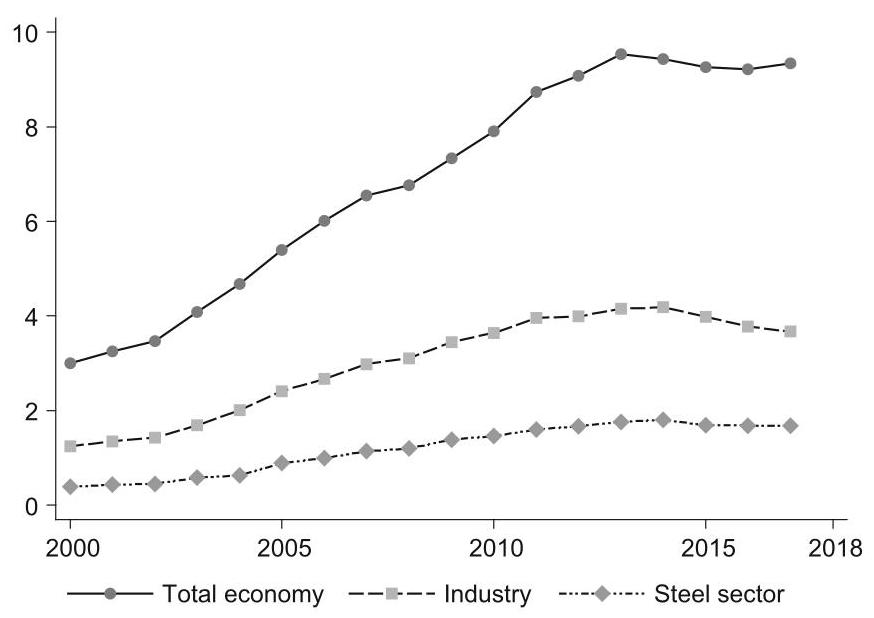
Fig. 4 ${\mathrm{{CO}}}_{2}$ Emissions in China (billion tons). Source Shan et al. (2018,2020)
图4 中国的${\mathrm{{CO}}}_{2}$排放(亿吨)。来源:单等人(2018年、2020年)
During China’s 13th FYP (2016-2020), “low carbon” and “green” growth has been emphasized as a crucial policy goal, and a series of policy tools were launched to urge industrial firms to take action in saving their energy and cutting ${\mathrm{{CO}}}_{2}$ emissions. For the steel sector in particular, the de-carbonization strategy consists of following three paths: (1) optimization of processes, (2) phasing-out of inefficient capacities, and (3) deploying new technologies at energy conservation and emission reductions.
在中国“十三五”规划(2016 - 2020年)期间,“低碳”和“绿色”增长被强调为关键政策目标,并推出了一系列政策工具,以敦促工业企业采取节能和减少${\mathrm{{CO}}}_{2}$排放的行动。特别是对于钢铁行业,脱碳战略包括以下三条路径:(1)工艺优化,(2)淘汰低效产能,(3)部署节能减排新技术。
2 Section 2
2 第2节
2.1 Climate Policy in China: An Evolving Framework
2.1 中国的气候政策:一个不断演变的框架
China has made remarkable progress in mitigation and adaptation to climate change in the past decade. The 12th Five Year Plan (FYP) (2011-2015) has identified the low-carbon and green growth as a strategic pathway towards sustainable growth since. The policy framework, however, was not put into place overnight. It has been an evolving process. Indeed, a salient feature of that process was “testing it out before scaling it up” with a mixture of pilots, (special) policies, regulations, and economic incentives. In other words, the policy framework consists of both “sticks” and “carrots” (see Table 1).
在过去十年里,中国在应对气候变化的减缓与适应方面取得了显著进展。自第十二个五年规划(2011 - 2015年)以来,已将低碳和绿色增长确定为实现可持续增长的战略途径。然而,政策框架并非一蹴而就,而是一个不断演变的过程。事实上,该过程的一个显著特点是通过试点、(特殊)政策、法规和经济激励措施的组合,进行“先试点再推广”。换句话说,政策框架包括“大棒”和“胡萝卜”(见表1)。
Given the complexity of a country’s institution of political economy, reform policies have been involving and will continue to involve in various government departments, both hierarchical and horizontal. The top level often provides guidance, either ex ante or ex post. Action takes place at the bottom level. Successful stories, often not explicitly authorized by the government a priori, could provide basis for formulating new policies ex post. Here, the same logic seems to have applied to the formulation of policies for developing a low-carbon and green economy. The need for inter-agency coordination has been particularly salient.
鉴于一个国家政治经济体制的复杂性,改革政策一直涉及并将继续涉及各级和各部门的政府部门。顶层通常会事前或事后提供指导,行动则在基层进行。成功案例往往事先未得到政府明确授权,但可为事后制定新政策提供依据。在这里,同样的逻辑似乎也适用于制定低碳和绿色经济政策。机构间协调的必要性尤为突出。
For instance, to launch CCUS pilots would involve multiple authorities, including the National Development and Reform Commission (NDRC), the Ministry of Science and Technology (MOST), the Ministry of Industry and Information Technology (MIIT), the Ministry of Natural Resources (MNR), etc., each with its own distinctive focus. Whereas MOST may focus on the R&D aspects of CCUS, NDRC may be more concerned from the perspective of energy security and economic and social impact from mitigation. And a new ministry, the Ministry of Ecology and Environment (MEE), has been established in 2018 to better respond to challenges posed by climate change.
例如,开展碳捕集、利用与封存(CCUS)试点将涉及多个部门,包括国家发展和改革委员会(NDRC)、科学技术部(MOST)、工业和信息化部(MIIT)、自然资源部(MNR)等,每个部门都有其独特的关注点。科学技术部可能侧重于CCUS的研发方面,国家发展和改革委员会可能更关注能源安全以及减排对经济和社会的影响。2018年成立了一个新的部,即生态环境部(MEE),以更好地应对气候变化带来的挑战。
Table 1 Key elements of climate policy framework in China
表1中国气候政策框架的关键要素
| Policies with "sticks" | Policies with "carrots" | ||
| Laws and regulations (by central and local governments) | Incentives | ||
| 30 laws: | e.g., Climate Change Law | e.g., pricing; subsidies; loan | |
| 90 regulations: | e.g., Administrative Regulations on ETS | discounts; fiscal and tax support; access to special funds | |
| Administrative orders (by central governments) | Markets | ||
| e.g., Standards for GHG emissions from industries (by SAC); accounting and reporting methods for GHG emissions in key industries (by NDRC) | e.g., 7 regional ETS pilots; national ETS in power sector; CCERs (by NDRC) | ||
In particular, as mentioned at the beginning of this chapter, there has been a constant and interactive feedback channel between China’s international commitments and domestic policy-making in climate change. Under the UN Framework Convention for Climate Change (UNFCCC), in 2009, China had pledged to reduce carbon intensity of GDP by 40-45% by 2020 from the 2005 level, and increase non-fossil fuels as a share of its energy structure to about 15%. Subsequently, the concept of carbon intensity was incorporated into the China’s 12th FYP (2011-2015). Similarly, during the Paris Climate Change Conference in 2015, China pledged to peak carbon emissions around 2030, and reduce carbon intensity of GDP by 60-65% by 2030 from the 2005 level. These commitments were integrated into China’s 13th FYP (2016-2020). Now that China has pledged to peak ${\mathrm{{CO}}}_{2}$ emissions prior to 2030 and become carbon neutral in 2060, one would expect that the coming 14th FYP (2021-2025) will embody a number of policies aimed at peaking ${\mathrm{{CO}}}_{2}$ emissions prior to 2030, and begin to work toward achieving carbon neutral in 2060.
特别是,如本章开头所述,中国的国际承诺与国内气候变化政策制定之间存在持续的互动反馈渠道。根据《联合国气候变化框架公约》(UNFCCC),2009年中国承诺到2020年将单位国内生产总值二氧化碳排放强度比2005年降低40 - 45%,并将非化石能源在能源结构中的占比提高到约15%。随后,碳排放强度概念被纳入中国的第十二个五年规划(2011 - 2015年)。同样,在2015年巴黎气候变化大会期间,中国承诺到2030年左右实现碳排放达峰,并到2030年将单位国内生产总值二氧化碳排放强度比2005年降低60 - 65%。这些承诺被纳入中国的第十三个五年规划(2016 - 202年)。既然中国已承诺在2030年前实现${\mathrm{{CO}}}_{2}$排放达峰并在2060年实现碳中和,人们预计即将到来的第十四个五年规划(2021 - 2025年)将包含一些旨在2030年前实现${\mathrm{{CO}}}_{2}$排放达峰的政策,并开始朝着2060年实现碳中和努力。
In what follows, we review some of the key policies, regulations, and laws, which together have fleshed out what has been and will continue to be an evolving policy framework for formulating a low-carbon and green economy in China, including the topic of CCUS as a negative carbon tool, in addition to low carbon and zero carbon technologies. In the process, among the complex and bewildering network of government agencies, we identify the key government departments tasked with green and sustainable growth in China.
在接下来的内容中,我们将回顾一些关键政策、法规和法律,它们共同构成并将继续构成中国制定低碳和绿色经济的不断演变的政策框架,包括作为负碳工具的CCUS主题,以及低碳和零碳技术。在此过程中,在复杂而令人困惑的政府机构网络中,我们确定了中国负责绿色和可持续增长的关键政府部门。
2.2 A Nexus of Legislation, Regulation, and Policy
2.2 立法、监管与政策的关联
Currently there are about 30 laws and 90 regulations regarding the development of low-carbon and green economy in China (see Table 1). In 2011, for better synergic work in a complex network of government agencies, the National Leading Group for Climate Change Legislation was set up to coordinate the legislation on issues of climate change. The group is comprised of the Environmental Protection and Resources Conservation Committee, the Law Committee of the National People’s Congress (NPC), the Legislative Affairs Office of the State Council-China’s cabinet, and as many as 17 central government ministries.
目前,中国有大约30部法律和90项法规涉及低碳和绿色经济发展(见表1)。2011年,为了在复杂的政府机构网络中更好地协同工作,成立了国家气候变化立法领导小组,以协调气候变化问题的立法工作。该小组由环境保护和资源保护委员会、全国人民代表大会法律委员会、国务院法制办公室(中国内阁)以及多达17个中央政府部委组成。
Among the 17 central government ministries, the National Development and Reform Commission (NDRC) is tasked with spearheading the legislative process, including drafting of laws, e.g., the Climate Change Law and the Administrative Regulations on Carbon Emissions Trading.
在这17个中央政府部委中,国家发展和改革委员会(NDRC)负责牵头立法进程,包括起草法律,例如《气候变化法》和《碳排放交易管理条例》。
Climate change-related legislation, regulation, and policy all tended to be very complicated. The making of China’s National Plan on Climate Change (2014- 2020) gives a good example of the complexity of the planning and implementation process. It involved not only many central government departments but also many local government departments. Indeed, setting ambitious but realistic targets is not an easy job. The effectiveness of policy impact is ultimately determined at the local levels rather than at the central level in Beijing. In other words, for policy implementation, there has to be a feedback channel in the political economy of central-local relations in China.
与气候变化相关的立法、监管和政策都往往非常复杂。中国《国家气候变化规划(2014 - 2020年)》的制定就是规划和实施过程复杂性的一个很好例子。它不仅涉及许多中央政府部门,还涉及许多地方政府部门。的确,设定雄心勃勃但切实可行的目标并非易事。政策影响的有效性最终是在地方层面而非北京的中央层面决定的。换句话说,对于政策实施,在中国中央 - 地方关系的政治经济中必须有一个反馈渠道。
Indeed, the top-down and bottom-up approach was reflected in the way that China built carbon market, known as emission-trading system (ETS) in Europe. In China, the 12th FYP (2011-15) had provided for “gradually establishing a carbon emissions trading market”. In line with the 12th FYP, in 2013, NDRC officially launched seven regional ETS pilots in China, including Beijing, Shanghai, Hubei, Guangdong, Shenzhen, Tianjin, and Chongqing-a topic that will be examined further in Part III of this study. In the same year, NDRC also issued a Circular on Promotion of Experiment and Demonstration in Carbon Capture, Utilization and Storage (CCUS), aimed at promoting CCUS as an emerging technology for direct ${\mathrm{{CO}}}_{2}$ emission reductions. As both CCUS and ETS are important topics of this study, they will be explored in a more systematical way in Part II and III, we will skip further discussion here to avoid redundancy.
的确,自上而下和自下而上的方法体现在中国建立碳市场的方式上,在欧洲被称为排放交易体系(ETS)。在中国,“十二五”规划(2011 - 2015年)规定“逐步建立碳排放交易市场”。根据“十二五”规划,2013年,国家发展和改革委员会正式在中国启动了七个区域碳排放交易试点,包括北京、上海、湖北、广东、深圳、天津和重庆——本研究第三部分将进一步探讨这个话题。同年,国家发展和改革委员会还发布了《关于推进碳捕集、利用与封存试验示范的通知》,旨在推动碳捕集、利用与封存作为直接减少${\mathrm{{CO}}}_{2}$排放的新兴技术。由于碳捕集、利用与封存和排放交易体系都是本研究的重要话题,它们将在第二部分和第三部分以更系统的方式进行探讨,在此我们将跳过进一步讨论以避免冗余。
It is important to note that in China’s evolving policy framework for low-carbon and green growth, “administrative orders”, more ad hoc than legislation, play an important role. These policy instruments are particularly salient in the energy conservation and ${\mathrm{{CO}}}_{2}$ emission controls. Examples include performance thresholds, green procurements, safety standards, and industry thresholds. For instance, in 2015 the Standardization Administration of China (SAC) issued 11 national standards for GHG emissions from industries. The Ministry of Transport (MOT), the National Railway Administration (NRA), and the State Forestry Administration (SFA) also issued low-carbon standards. The NDRC provided accounting and reporting methods for GHG emissions in 23 key industries. The National Technical Committee on Carbon Management (NTCC) was responsible for formulating and revising national standards for the carbon management, which includes a system of low-carbon product certification launched in 2015.
需要注意的是,在中国不断发展的低碳和绿色增长政策框架中,“行政命令”发挥着重要作用,其临时性高于立法。这些政策工具在节能和${\mathrm{{CO}}}_{2}$排放控制方面尤为突出。例子包括绩效门槛、绿色采购、安全标准和行业门槛。例如,2015年中国国家标准化管理委员会(SAC)发布了11项行业温室气体排放国家标准。交通运输部(MOT)、国家铁路局(NRA)和国家林业局(SFA)也发布了低碳标准。国家发展和改革委员会提供了23个重点行业温室气体排放的核算和报告方法。国家碳管理技术委员会(NTCC)负责制定和修订碳管理国家标准,其中包括2015年推出的低碳产品认证体系。
2.3 Low-Carbon Policy for Industry
2.3 工业领域的低碳政策
The industrial sector in China is a major energy consumer and ${\mathrm{{CO}}}_{2}$ emitter. ${}^{8}$ Key battles have to be fought there. Indeed, during the 12th FYP (2011-2015), China came up with a series of policies, with both “sticks” and “carrots”, all aiming at low-carbon and green growth. In the 12th FYP period, these policies came in the form of 10 plans, 9 programs, 13 opinions, 6 notices, and 8 decisions, measures and guidelines, which fall into six buckets: structural adjustment, standard development, regulatory instruments, economic incentives, market-based instruments, and policy guidance.
中国工业部门是主要的能源消费方和${\mathrm{{CO}}}_{2}$排放源。${}^{8}$必须在该领域打好关键战役。事实上,在“十二五”规划(2011 - 2015年)期间,中国出台了一系列政策,有“大棒”也有“胡萝卜”,目标都是实现低碳和绿色增长。在“十二五”规划期间,这些政策表现为10项规划、9个方案、13份意见、6份通知以及8项决定、措施和指导方针,可归为六大类:结构调整、标准制定、监管手段、经济激励、市场机制工具以及政策引导。
The mix of “sticks” and “carrots” of these policy instruments as whole seemed to have worked in reducing energy consumption and ${\mathrm{{CO}}}_{2}$ emissions. For example, while the share of energy-intensive industries declined, that of high-tech industries increased. In 2010, energy-intensive industries accounted for about 30.3% in terms of value added, by 2015, the comparable number was 27.8%, down by 2.5% from the 2010 level. In the process, a large amount of outdated production capacity was removed, including 91 million tons of iron, 95 million tons of steel, 657 million tons of cement, and 2 million tons of electrolytic aluminum. At the same time, energy efficiency was significantly improved. The energy consumption per unit of value added dropped by ${28}\%$ , representing 690 million tons of standard coal saved. In particular, six major industries—steel, nonferrous metals, petrochemicals, chemicals, building materials, and paper-making—narrowed the gap with their global leaders in terms of energy consumption per unit of products.
这些政策工具整体的“大棒”与“胡萝卜”组合在降低能源消耗和${\mathrm{{CO}}}_{2}$排放方面似乎发挥了作用。例如,能源密集型产业的占比下降,而高新技术产业的占比上升。2010年,能源密集型产业增加值占比约为30.3%,到2015年,这一数字为27.8%,比2010年水平下降了2.5%。在此过程中,大量落后产能被淘汰,包括9100万吨铁、9500万吨钢、6.57亿吨水泥以及200万吨电解铝。与此同时,能源效率显著提高。单位增加值能耗下降了${28}\%$,相当于节约了6.9亿吨标准煤。特别是钢铁、有色金属、石化、化工、建材和造纸这六大行业,在单位产品能耗方面缩小了与全球领先水平的差距。
${}^{8}$ According to IEA classification of ’Industry’, in 2015 for example, industry sector alone accounted for ${43}\%$ of national energy consumption and ${52}\%$ of national carbon emissions.
${}^{8}$ 例如,根据国际能源署对“工业”的分类,仅工业部门在2015年就占全国能源消耗的${43}\%$以及全国碳排放的${52}\%$。
2.4 Low-Carbon Policy for the Steel Sector
2.4 钢铁行业低碳政策
In 2006, under the United Nations Framework Convention on Climate Change (UNFCCC), China had pledged to the world to reduce energy intensity of GDP by 40-45% in 2020 from the 2005 level. Consistent with that pledge, during the 11th FYP (2006-2010), China had for the first time incorporated the concept of “energy intensity” into the national economic and social development plan. To promote low-carbon pathways, policy-makers started to set binding targets for energy conservation and energy efficiency and took proactive measures to adjust the industrial structure by inhibiting fossil-intensive industries. In the 12th FYP (2011-2015), carbon intensity of GDP was integrated into the national plan for economic and social development, and ${\mathrm{{CO}}}_{2}$ emission controls became an eye-grabbing issue especially for the steel sector.
2006年,根据《联合国气候变化框架公约》(UNFCCC),中国向世界承诺,到2020年将单位国内生产总值(GDP)能耗在2005年的基础上降低40%-45%。为履行这一承诺,在“十一五”规划(2006-2010年)期间,中国首次将“能源强度”概念纳入国民经济和社会发展规划。为推动低碳发展路径,政策制定者开始设定节能减排的约束性目标,并采取积极措施,通过抑制化石能源密集型产业来调整产业结构。在“十二五”规划(2011-2015年)期间,单位国内生产总值(GDP)碳强度被纳入国家经济和社会发展规划,${\mathrm{{CO}}}_{2}$排放控制成为一个引人关注的问题,尤其是对于钢铁行业而言。
In retrospect, a total of 36 key policies were issued for the iron/steel sector since 2006, including 12 during the 11th FYP (2006-2010), 17 during the 12th FYP (2011-2015), and 7 during the 13th FYP (2016-2020). These policy instruments can be categorized into five areas: structural adjustment, mandatory tasks, economic incentives, industry standards, and industry guidelines. And the policy making involved a long list of government departments, including the State Council, the NDRC, the Ministry of Industry and Information Technology (MIIT) (for the structural adjustment); the NDRC, the MIIT and the SAC (for the industry standards); the State Council, the NDRC, and the Ministry of Finance (MOF) (for economic incentives); and the State Council, the MIIT, the NDRC and local governments (for mandatory tasks).
回顾来看,自2006年以来,钢铁行业共发布了36项关键政策,其中“十一五”规划(2006 - 2010年)期间发布了12项,“十二五”规划(2011 - 2015年)期间发布了17项,“十三五”规划(2016 - 2020年)期间发布了7项。这些政策工具可分为五个领域:结构调整、强制性任务、经济激励、行业标准和行业指南。政策制定涉及众多政府部门,包括国务院、国家发展和改革委员会(国家发改委)、工业和信息化部(工信部)(负责结构调整);国家发改委、工信部和国家标准化管理委员会(国家标准委)(负责行业标准);国务院、国家发改委和财政部(负责经济激励);以及国务院、工信部、国家发改委和地方政府(负责强制性任务)。
While industry guidelines are not mandatory, they have the effect of encouraging industrial firms to shape or rather re-shape strategic planning, carry out R&D, and shift towards green-oriented circular economy via energy saving and technology upgrading, etc.
虽然行业指南不具有强制性,但它们具有鼓励工业企业制定或重新制定战略规划、开展研发,并通过节能和技术升级等实现向绿色循环经济转型的作用。
During the 11th FYP (2006-2010), the policy focus for the steel sector centered on structural adjustments, aiming to enhance energy efficiency, control overcapacity, and upgrade technology. Mergers and acquisitions (M&A) in the iron/steel sector were encouraged to improve industrial concentration. The results were significant. Under the combined policy implementation, 123 million tons of inefficient iron production capacity and 72 million tons of inefficient steel production capacity were phased out over the five years. They were replaced by large-scale modern facilitates. Among leading steel plants, the share of blast furnaces with over ${1000}{\mathrm{\;m}}^{3}$ capacity increased from 48 to ${61}\%$ , and that of converters with over 100 tons capacity increased from 45 to 57%. By 2011, energy consumption per ton of iron dropped to 605 kgce (kilograms of coal equivalent), down by 12.8%, as compared with that in 2005. Table 2 summarizes key targets of FYPs (Five Year Plans).
在“十一五”规划(2006 - 2010年)期间,钢铁行业的政策重点集中在结构调整上,旨在提高能源效率、控制产能过剩并升级技术。鼓励钢铁行业进行并购以提高产业集中度。成效显著。在各项政策共同实施下,五年间共淘汰了1.23亿吨低效炼铁产能和7200万吨低效炼钢产能。取而代之的是大规模现代化设施。在主要钢铁厂中,产能超过${1000}{\mathrm{\;m}}^{3}$的高炉占比从48%提高到了${61}\%$,100吨以上转炉的占比从45%提高到了57%。到2011年,每吨铁的能源消耗降至605千克标准煤,与2005年相比下降了12.8%。表2总结了各五年规划的主要目标。
Table 2 Key targets of FYPs
表2五年计划的主要目标
| 11th FYP (2006-2010) | 12th FYP (2011-2015) | 13th FYP (2016-2020) | |
| International pledges | Reduce carbon intensity of GDP by 40-45% in 2020 from the 2005 level; increase non-fossil to 15% | Reduce carbon intensity of GDP by 60-65% in 2030 from the 2005 level | Peak carbon emissions prior to 2030, and achieve carbon neutrality by 2060 |
| Domestic regulatory moves | Mergers and acquisitions in steel sector and energy conservation encouraged | Industrial standards and access to steel sector raised; pilot ETS launched | MOF offered supportive policies to steel sector; 25-member inter-ministerial joint conference set up with approval of SC to address overcapacity; national ETS started |
| Formation of carbon market | None | 7 regional ETS pilots launched in 2013. They cover many industries, including steel sector | National ETS in 2017, covering only power sector |
During the 12th FYP (2011-2015), “low carbon” was identified as a principal objective for the steel sector, and the target of ${18}\% {\mathrm{{CO}}}_{2}$ emission reduction per unit of value added was set. To this end, industrial standards and access to the sector were raised and new targets were set to further phase out inefficient facilities. As a result, a total of 90.89 million and 94.86 million tons of inefficient iron and steel production capacity were slashed off respectively, although overcapacity continued to exist. Crude steel capacity utilization, for instance, was down from 79 to ${70}\%$ , and the debt rate of large and medium-sized firms exceeded 70%. In the meantime, although the energy consumption per ton of steel declined from 605 to 572 kgce, it was not adequate to offset the net increase of energy consumption with continued production expansion in the sector.
在“十二五”规划期间(2011 - 2015年),“低碳”被确定为钢铁行业的主要目标,并设定了单位增加值${18}\% {\mathrm{{CO}}}_{2}$减排目标。为此,提高了行业标准和准入门槛,并设定了新目标以进一步淘汰低效产能。结果,尽管产能过剩问题依然存在,但分别削减了9089万吨和9486万吨低效钢铁产能。例如,粗钢产能利用率从79%降至${70}\%$,大中型企业负债率超过70%。与此同时,尽管每吨钢的能耗从605千克标准煤降至572千克标准煤,但仍不足以抵消该行业持续生产扩张带来的能源消耗净增长。
Efforts for a low-carbon economy had intensified in the 13th FYP (2016- 2020). Due to an integral part of quality-over-quantity growth strategy, supply-side reforms were highly emphasized on the agenda of the 13th FYP. In line with this, the overall policy on the steel sector tightened up, where the cumulative reduction in its production capacity was up to 100-150 million ton (including 90 million tons of outdated production facilities). To facilitate the low-carbon economy process, in addition to “sticks”, “carrots” were also offered. The MOF issued several policy documents, covering fiscal and tax supports, subsidies, employee relocation benefits, land use, etc. In addition, a mechanism of coordination of 25-member inter-ministerial joint conference was set up with the approval of the State Council. The policy goal was to solve the issue of overcapacity in iron, steel, and coal production.
在“十三五”规划(2016 - 2020年)期间,发展低碳经济的努力得到加强。作为质量优先于数量增长战略的一个组成部分,供给侧改革在“十三五”规划议程中得到高度重视。与此相应,钢铁行业的整体政策收紧,其产能累计削减达1亿至1.5亿吨(包括9000万吨落后生产设施)。为推动低碳经济进程,除了“大棒”政策,也有“胡萝卜”政策。财政部发布了多项政策文件,涵盖财税支持、补贴、职工安置福利、土地使用等方面。此外,经国务院批准,建立了由25个成员组成的部际联席会议协调机制。政策目标是解决钢铁、煤炭行业产能过剩问题。
The 12th FYP had provided for “gradually establishing a carbon emissions trading market”. Along with the experiences of the seven regional ETS pilots launched in 2013, during the 13th FYP (2016-2020), China has started the process of building national carbon market by the end of 2017. According to the 2015 China-US Joint Presidential Statement on Climate Change, the national ETS in China would cover some major polluting industries, like steel, electricity, chemicals, building materials, paper-making, and non-ferrous metals. Yet, when China first kicked off the national ETS in 2017, the national ETS only covered the power sector, with the expectation that other industrial sectors would eventually be included into the unified national ETS. At the same time, China has adopted a two-track system of ETSs—a national ETS and seven regional ETS pilots. The former covers only the power sector, whereas the latter covers a wider range of industrial sectors. Some have included the steel sector. Such heterogeneity may reflect the regional diversity of China in sectorial and industrial structures.
“十二五”规划提出“逐步建立碳排放交易市场”。随着2013年启动的七个区域碳排放交易试点的经验积累,在“十三五”规划(2016 - 2020年)期间,中国于2017年底开始了全国碳市场建设进程。根据2015年中美气候变化联合声明,中国的全国碳排放交易体系将覆盖一些主要污染行业,如钢铁、电力、化工、建材、造纸和有色金属行业。然而,2017年中国首次启动全国碳排放交易体系时,该体系仅覆盖电力行业,期望其他工业部门最终能纳入统一的全国碳排放交易体系。同时,中国采用了碳排放交易体系的双轨制——全国碳排放交易体系和七个区域碳排放交易试点。前者仅覆盖电力行业,而后者覆盖更广泛的工业部门。有些区域试点已将钢铁行业纳入。这种异质性可能反映了中国在行业和产业结构方面的区域多样性。
3 Section 3
3 第3节
3.1 Climate Policy Regarding CCUS: A Global Perspective
3.1 关于碳捕集、利用与封存(CCUS)的气候政策:全球视角
In 2018, the Intergovernmental Panel on Climate Change (IPCC) issued the Special Report on Global Warming of ${1.5}{}^{ \circ }\mathrm{C}$ (SR15). The Report warns that the impact of above ${1.5}^{ \circ }\mathrm{C}$ of global warming will spell disasters to the ecosystem on Earth, and highlights the urgency for the global community to undertake ${\mathrm{{CO}}}_{2}$ emission reductions with best available technologies (BATs). In this context, the International Energy Agency (IEA) takes carbon capture, utilization and storage (CCUS) as an integral part of the lowest cost route to achieving climate targets (IEA, 2019b; IPCC, 2018), and removing CCUS from the BAT portfolio would lead to a doubling of costs in the future-the biggest rise in costs from excluding any technology.
2018年,政府间气候变化专门委员会(IPCC)发布了《全球升温${1.5}{}^{ \circ }\mathrm{C}$的特别报告》(SR15)。该报告警告称,全球变暖超过${1.5}^{ \circ }\mathrm{C}$将给地球生态系统带来灾难,并强调全球社会迫切需要采用现有最佳技术(BAT)进行${\mathrm{{CO}}}_{2}$减排。在此背景下,国际能源署(IEA)将碳捕集、利用与封存(CCUS)视为实现气候目标的最低成本途径的一个组成部分(IEA,2019b;IPCC,2018),将CCUS排除在BAT组合之外将导致未来成本翻倍——这是排除任何技术导致的成本最大增幅。
While many governments have recognized the role of CCUS as an emerging technology for direct reduction of carbon emissions on industrial scale, actions in terms of policy supports are yet to come. Indeed, many are watching and waiting, given the fact that globally CCUS is still in nascent state with many uncertainties and risks, leading to an investment dilemma. A higher perceived risk means a higher rate of return expected, but making the funding process more difficult. The immediate challenge is that while an operational CCUS project may capture millions of tons of ${\mathrm{{CO}}}_{2}$ emissions per year, it requires hundreds of millions of dollars for an initial investment. As a result, funding has been a big barrier to the development of CCUS. That said, in the past few years, six countries-the US, the UK, Canada, Norway, Japan, and China-have stood out as CCUS leaders in the field (IEA, 2019b).
虽然许多国家政府已认识到CCUS作为一种可在工业规模上直接减少碳排放的新兴技术的作用,但在政策支持方面的行动尚未出台。事实上,鉴于全球范围内CCUS仍处于起步阶段,存在许多不确定性和风险,导致投资困境,许多国家都在观望等待。较高的感知风险意味着预期较高的回报率,但也使融资过程更加困难。当前的挑战是,一个运营中的CCUS项目每年可能捕获数百万吨${\mathrm{{CO}}}_{2}$排放,但初始投资需要数亿美元。因此,资金一直是CCUS发展的一大障碍。话虽如此,在过去几年中,美国、英国、加拿大、挪威、日本和中国这六个国家在该领域脱颖而出,成为CCUS的领先者(IEA,2019b)。
In what follows next, to better understand where China stands in terms of policy and practice in the field of CCUS, let us take a global fieldtrip first, looking at climate policies and CCUS projects in different countries/regions around the world. After the tour, we will come back to China in Section 4 for reviewing its policy and practice with respect to CCUS-a strategical reserve technology under development in its efforts of mitigation and adaptation to climate change down the road.
接下来,为了更好地了解中国在CCUS领域的政策和实践处于何种位置,让我们先进行一次全球之旅,看看世界不同国家/地区的气候政策和CCUS项目。参观之后,我们将在第4节回到中国,审视其在CCUS方面的政策和实践——CCUS是中国在应对气候变化的缓解和适应努力中正在开发的一项战略储备技术。
3.2 A Global Fieldtrip
3.2 一次全球实地考察
The United States
美国
As early as in 2006, the US Climate Technology Program had suggested controlling GHG emissions through CCUS. Accordingly, the US Carbon Capture and Storage Early Deployment Act (2009) encouraged the early deployment of CCUS, and the American Clean Energy Leadership Act (2009) further clarified the regulatory framework and financial assistance for CCUS. In its Clean Power Plan, the carbon emission standards pushed forward low-carbon technologies and gave strong impetus to mitigation in the power supply sector. As CCUS technology remains high on the learning curve, incentives focus on providing for early stage initiatives and reducing long-term uncertainty.
早在2006年,美国气候技术计划就建议通过碳捕集、利用与封存(CCUS)来控制温室气体排放。相应地,美国《碳捕集与封存早期部署法案》(2009年)鼓励CCUS的早期部署,而《美国清洁能源领导力法案》(2009年)进一步明确了CCUS的监管框架和财政援助。在其《清洁能源计划》中,碳排放标准推动了低碳技术发展,并有力地促进了电力供应部门的减排。由于CCUS技术仍处于学习曲线的高位阶段,激励措施主要集中在为早期项目提供支持并减少长期不确定性。
Specifically, the Department of Energy (DOE) incentivized CCUS demonstration projects in the industrial sector with US$ 1.52 billion in the deployment funding, derived from the 2009 American Reinvestment and Recovery Act. Section 45Q of the Internal Revenue Code also provided for carbon sequestration tax credits. Section 45Q gave $20 tax credit per ton of ${\mathrm{{CO}}}_{2}$ captured and stored, and $10 per ton of ${\mathrm{{CO}}}_{2}$ captured and used for enhanced oil recovery (EOR). In 2018, the United States Congress further increased tax credit to $\$ {35}$ per ton of ${\mathrm{{CO}}}_{2}$ sequestered through EOR and to \$50 per ton of geological sequestration if the project begins construction by 2024, which help to encourage the early deployment of CCUS. The value of up to $50 per ton of ${\mathrm{{CO}}}_{2}$ over the next five years is expected to spur a new round of CCUS facilities (Department of the Treasury, 2018).
具体而言,美国能源部(DOE)利用2009年《美国复苏与再投资法案》提供的15.2亿美元部署资金,激励工业部门的CCUS示范项目。美国《国内税收法典》第45Q条也规定了碳封存税收抵免。第45Q条规定,每吨捕获并封存的${\mathrm{{CO}}}_{2}$可获得20美元税收抵免,每吨捕获并用于提高石油采收率(EOR)的${\mathrm{{CO}}}_{2}$可获得10美元税收抵免。2018年,美国国会进一步提高了税收抵免额度,如果项目在2024年前开工建设,通过EOR封存每吨${\mathrm{{CO}}}_{2}$的税收抵免提高到$\$ {35}$,地质封存每吨${\mathrm{{CO}}}{2}$的税收抵免提高到50美元,这有助于鼓励CCUS的早期部署。预计未来五年每吨${\mathrm{{CO}}}{2}$高达50美元的价值将刺激新一轮CCUS设施建设(美国财政部,2018年)。
In the United States, there are a lot of local actions at the state level as well. For example, after California passed its legislation on zero-carbon energy mandate and carbon neutrality by 2050 target, other states followed suit. Louisiana, Montana, North Dakota, and Texas have also offered tax incentives for the deployment of CCUS (Clean Air Task Force, 2019).
在美国,州一级也有很多地方行动。例如,加利福尼亚州通过其关于零碳能源授权和2050年碳中和目标的立法后,其他州纷纷效仿。路易斯安那州、蒙大拿州、北达科他州和得克萨斯州也为CCUS的部署提供了税收激励(清洁空气任务组,2019年)。
So far, the United States has the largest CCUS facility in the world, with a cumulative capture and injection capacity of more than 150 million tons. Of the 18 operating CCUS facilities worldwide, 10 are located in the US (including a CO2 injection capture facility in Canada) (Global CCS Institute, 2019). Among these, the largest is the Century Natural Gas plant and CCUS plant in Texas, with an annual capacity of 8.4 million tons, followed by the Shuter Creek CCUS facility, which has an annual capacity of 7 million tons. The industrial CCS facility in Illinois reached the million-ton mark by extracting ${\mathrm{{CO}}}_{2}$ from an ethanol plant run by Archer Daniels Midland and storing ${\mathrm{{CO}}}_{2}$ deep underground near the plant.
到目前为止:美国拥有世界上最大的CCUS设施,累计捕集和注入能力超过1.5亿吨。全球18个运营中的CCUS设施中,有10个位于美国(包括加拿大的一个二氧化碳注入捕集设施)(全球CCS研究所,2019年)。其中,最大的是得克萨斯州的世纪天然气厂和CCUS厂,年处理能力为840万吨,其次是舒特溪CCUS设施,年处理能力为700万吨。伊利诺伊州的工业CCS设施通过从阿彻丹尼尔斯米德兰公司运营的乙醇厂提取${\mathrm{{CO}}}_{2}$并将其深埋在工厂附近地下,达到了百万吨级规模。
The Petra Nova is the only large CCUS power plant in the United States, and one of the only two in the world. The plant uses post-combustion capture technology to extract ${90}\%$ of ${\mathrm{{CO}}}_{2}$ emissions from the flue gas of the generator set. The facility captures up to 1.4 million tons of ${\mathrm{{CO}}}_{2}$ emissions on a yearly basis.
佩特拉诺瓦是美国唯一的大型CCUS发电厂,也是世界上仅有的两座此类发电厂之一。该工厂采用燃烧后捕集技术,从发电机组的烟气中提取${\mathrm{{CO}}}_{2}$排放中的${90}\%$。该设施每年最多可捕集140万吨${\mathrm{{CO}}}_{2}$排放。
Canada and South America
加拿大和南美洲
Across the Americas, interest in CCUS remains high. Indeed, more than 10% of Canadian government R&D spending has been directed toward CCUS since 2010. Since then, the country has aimed to drive the development of CCUS through both grant support and emission performance standard. At the provincial level, Alberta and Saskatchevan have a royalty relief protocol for ${\mathrm{{CO}}}_{2}$ -EOR, and British Columbia has a carbon tax of US$ 30/ton ${\mathrm{{CO}}}_{2}$ from anthropogenic combustion emissions.
在整个美洲地区,对碳捕集、利用与封存(CCUS)的兴趣依然浓厚。事实上,自2010年以来,超过10%的加拿大政府研发支出都投向了CCUS领域。自那时起,该国一直致力于通过拨款支持和排放绩效标准来推动CCUS的发展。在省级层面,艾伯塔省和萨斯喀彻温省针对${\mathrm{{CO}}}_{2}$ -提高采收率(EOR)制定了特许权使用费减免协议,而不列颠哥伦比亚省对人为燃烧排放的${\mathrm{{CO}}}_{2}$征收30美元/吨的碳税。
Under the Canadian Sustainable Growth and Climate Action Plan, each Canadian province and territory is required to submit to the federal government with a summary of its carbon pricing plan. Costs must start at Canadian $10 (or more) per ton of ${\mathrm{{CO}}}_{2}$ and rise to Canadian $50 per ton by 2022. The federal carbon pricing scheme took effect in January, 2019, and all direct carbon pricing revenue will return to the jurisdiction of origin (Government of Canada, 2008).
根据加拿大可持续增长与气候行动计划,加拿大的每个省和地区都必须向联邦政府提交其碳定价计划摘要。成本必须从每吨${\mathrm{{CO}}}_{2}$ 10加元(或更高)起步,并在2022年升至每吨50加元。联邦碳定价计划于2019年1月生效,所有直接碳定价收入将返还至来源地辖区(加拿大政府,2008年)。
In the Americas, through the Canada Strategic Innovation Fund, several milestones were set as the Canadian government. They has invested $25 million in Carbon Engineering (a Canadian Direct Air Capture company), in partnership with some private firms such as BHP, Chevron, and Occidental. Since 2013, the Petrobras Santos Basin Pre-Salt Oil Field CCS has been on-site to separate and capture ${\mathrm{{CO}}}_{2}$ as part of natural gas extraction. Deploying EOR (enhanced oil recovery) technology, the captured ${\mathrm{{CO}}}_{2}$ is injected directly into the natural gas field. The Boundary Dam CCUS project has the capacity to captures about $1\mathrm{M}$ tpa ${\mathrm{{CO}}}_{2}$ from a coal-fired power plant and use part of it for EOR purposes at the Weyhurn oil field, with a small proportion for dedicated geological storage. The Quest CCUS facility, a joint venture of Shell (60%), Chevon (20%) and Marathon Oil (20%), captures, transports, and stores over $1\mathrm{{Mtpa}}$ of ${\mathrm{{CO}}}_{2}$ .
在美洲地区,通过加拿大战略创新基金,加拿大政府设定了多个里程碑。它已与必和必拓、雪佛龙和西方石油等一些私营公司合作,向碳工程公司(一家加拿大直接空气捕集公司)投资2500万美元。自2013年以来,巴西国家石油公司桑托斯盆地盐下油田的碳捕集与封存项目一直在现场进行,以分离和捕获${\mathrm{{CO}}}_{2}$作为天然气开采的一部分。通过部署提高采收率(EOR)技术,捕获的${\mathrm{{CO}}}_{2}$被直接注入天然气田。边界大坝CCUS项目有能力从一座燃煤发电厂捕获约$1\mathrm{M}$吨/年的${\mathrm{{CO}}}_{2}$,并将其中一部分用于韦于恩油田的提高采收率目的,一小部分用于专门的地质封存。魁斯特CCUS设施是壳牌(60%)、雪佛龙(20%)和马拉松石油(20%)合资的项目,可捕获、运输和储存超过$1\mathrm{{Mtpa}}$的${\mathrm{{CO}}}_{2}$。
Elsewhere, coal and gas power plants, as well as stakeholders in the ethanol market, are keen to speed up CCUS development. In Mexico, there are two CCUS pilots- ${\mathrm{{CO}}}_{2}$ Capture Pilot Project and ${\mathrm{{CO}}}_{2}$ -EOR and Sequestration Pilot-underway with the support of the CCUS Trust Fund of the World Bank. These CCUS projects were expected to begin operation in 2020.
在其他地方,煤炭和天然气发电厂以及乙醇市场的利益相关者都渴望加快CCUS的发展。在墨西哥,在世界银行的CCUS信托基金支持下,有两个CCUS试点项目——${\mathrm{{CO}}}_{2}$捕集试点项目和${\mathrm{{CO}}}_{2}$ -提高采收率与封存试点项目正在进行中。这些CCUS项目预计于2020年开始运营。
The European Union
欧盟
As early as in 2006, the Green Paper: A European Strategy for Sustainable, Competitive and Secure Energy was issued by the European Union (EU). The Green Paper identified CCUS as one of the three policy priorities to address the challenge associated with energy security and climate change. In addition, the European Strategic Energy Technology Plan (SET-Plan) published in 2007 proposed a dedicated policy to accelerate the development and application of low-carbon technologies.
早在2006年,欧盟就发布了《绿皮书:欧洲可持续、竞争和安全能源战略》。该绿皮书将碳捕集、利用与封存(CCUS)确定为应对能源安全和气候变化挑战的三大政策重点之一。此外,2007年发布的《欧洲战略能源技术计划》(SET-Plan)提出了一项专门政策,以加速低碳技术的开发和应用。
With respect to CCUS technology, the EU CCS Directive specifically dedicates Articles 13 and 16 to the issue of leakage, and the Recommended Practice: Design and Operation of ${\mathrm{{CO}}}_{2}$ Pipelines of Det Norske Veritas makes provisions for monitoring tools and incident response. In addition, the EU’s Seventh Framework Program for Research and Technological Development released in 2007 proposed funding projects related to CCUS and sets aside 300 million EU ETS (Emission Trading System) allowances to support 10-12 CCUS projects. Moreover, the EU Comprehensive Climate and Energy Package of 2009 set specific targets for ETS and CCUS, as well as for renewables as share of energy consumption to increase to 20% and to cut GHG emissions by 20% by 2020 from the 1990 level.
关于CCUS技术,欧盟的CCS指令特别将第13条和第16条专门用于泄漏问题,挪威船级社(Det Norske Veritas)的《${\mathrm{{CO}}}_{2}$管道设计与运行推荐做法》对监测工具和事故应对做出了规定。此外,2007年发布的欧盟第七个研究与技术发展框架计划提出了与CCUS相关的资助项目,并预留了3亿个欧盟排放交易体系(ETS)配额,以支持10 - 12个CCUS项目。此外,2009年欧盟的《综合气候与能源一揽子计划》为ETS和CCUS以及可再生能源设定了具体目标,即到2020年将可再生能源在能源消费中的占比提高到20%,并将温室气体排放量在1990年的基础上削减20%。
In 2018, in its Clean World for All-A Long-term European Strategic Vision for a Stable, Modern, Efficient and Climate-Neutral Economy, the European Commission (EC) unveiled its plan for Europe to achieve carbon neutrality by 2050 (European Commission, 2018). To achieve that goal, both ETS and CCUS have a strategic role to play. In terms of ETS, based on new research on EU-ETS, the EU beeefd up its market stability reserves and was ready to accelerate emission reductions. More specifically, from 2021, the EU will reduce total emission allowances at an annual rate of 2.2%, as compared with the current rate of 1.74%. In terms of CCUS, a €10 billion Innovation Fund was set up, with an aim to speed up the development of CCUS projects. CCUS was expected to contribute anywhere from 52 million to 6.06 million tons of ${\mathrm{{CO}}}_{2}$ per year by 2050 under different scenarios.
2018年,欧盟委员会(EC)在其《为所有人创造清洁世界——欧洲实现稳定、现代、高效和气候中和经济的长期战略愿景》中公布了欧洲到2050年实现碳中和的计划(欧盟委员会,2018年)。为实现这一目标,ETS和CCUS都将发挥战略作用。在ETS方面,基于对欧盟排放交易体系的新研究,欧盟加强了其市场稳定储备,并准备加速减排。更具体地说,从2021年起,欧盟将以每年2.2%的速度减少总排放配额,而目前的速度为1.74%。在CCUS方面,设立了100亿欧元的创新基金,旨在加速CCUS项目的开发。在不同情景下,预计到2050年CCUS每年将贡献5200万至606万吨的${\mathrm{{CO}}}_{2}$。
In recent years, significant changes have taken place in the way the CCUS project is designed in Europe. The new emphasis is on integrated and full chain solution rather than individual transportation from ${\mathrm{{CO}}}_{2}$ source to storage site. Shared infrastructure for ${\mathrm{{CO}}}_{2}$ transport and storage sites can reduce unit costs across the CCUS value chain. As a result, most CCUS projects in Europe are designed as an integral part of industrial clusters with hubs and spokes. These CCUS-dedicated industrial clusters are expected to be established in several major industrial areas of Europe: the ports of Antwerp in Belgium, Amsterdam and Rotterdam in the Netherlands, Humber and Teesside in the UK (Global CCS Institute, 2016).
近年来,欧洲CCUS项目的设计方式发生了重大变化。新的重点是综合和全链条解决方案,而不是从${\mathrm{{CO}}}_{2}$源到储存地点的单独运输。${\mathrm{{CO}}}_{2}$运输和储存地点的共享基础设施可以降低CCUS价值链的单位成本。因此,欧洲的大多数CCUS项目都被设计为工业集群的一个组成部分,形成中心辐射型布局。预计这些专门的CCUS工业集群将在欧洲的几个主要工业区建立:比利时的安特卫普港、荷兰的阿姆斯特丹和鹿特丹港、英国的亨伯和蒂斯赛德(全球CCS研究所,2016年)。
The United Kingdom
英国
In the UK, the Stern Report in 2006 provided a basis for meeting energy challenge and developing CCUS. In its wake, the White Paper on Energy in 2007 put forward process-wide CCUS demonstration in power plants across the country. Further, the Energy Act of 2008 provided a framework for licensing, enforcement and registration of storage sites. The world’s first Climate Change Act of 2008 incorporated CCUS into the emission reduction plan for the power industry.
2006年,英国的《斯特恩报告》为应对能源挑战和发展碳捕集、利用与封存(CCUS)提供了基础。随后,2007年的《能源白皮书》提出在全国发电厂进行全流程CCUS示范。此外,2008年的《能源法案》为封存地点的许可、执法和注册提供了框架。2008年世界上第一部《气候变化法案》将CCUS纳入电力行业减排计划。
From the perspective of the UK government, CCUS is taken as an important technology in its strategy to transit to a low-carbon economy, and the government therefore provides tax supports to facilitate this strategic transition. Accordingly, the UK Climate Change Levy stipulates that the electric power enterprises enjoy an 80% tax relief as long as they reach certain targets for energy efficiency and emission reduction through CCUS applications. As a part of its Clean Growth plan, the UK government has also pledged to invest $100 million in innovation in CCUS to reduce costs, as well as to pursue international cooperation opportunities.
从英国政府的角度来看,CCUS被视为其向低碳经济转型战略中的一项重要技术,因此政府提供税收支持以促进这一战略转型。相应地,英国气候变化税规定,只要电力企业通过CCUS应用达到一定的能源效率和减排目标,就可享受80%的税收减免。作为其清洁增长计划的一部分,英国政府还承诺投资1亿美元用于CCUS创新以降低成本,并寻求国际合作机会。
In 2019, based on the recommendation by the UK Committee on Climate Change, the UK government set the goal of achieving carbon neutrality by 2050. To facilitate decarbonization, CCUS was identified to play an important role in the process. In March 2019, the UK government set up the CCUS Advisory Group-composed of experts from the business, finance and legal professions-to identify current bottlenecks facing CCUS development (CCUS Advisory Group, 2019). Apart from business models that propose to diversify funding mechanisms of CCUS investment, the Advisory Group also recommended the reuse or repurpose of the existing infrastructure in the country, aiming to reduce ${\mathrm{{CO}}}_{2}$ transportation and storage costs.
2019年,根据英国气候变化委员会的建议,英国政府设定了到2050年实现碳中和的目标。为推动脱碳,CCUS被认为在这一过程中发挥重要作用。2019年3月,英国政府成立了CCUS咨询小组,成员包括来自商业、金融和法律行业的专家,以确定CCUS发展目前面临的瓶颈(CCUS咨询小组,2019年)。除了提出多样化CCUS投资融资机制的商业模式外,咨询小组还建议对该国现有基础设施进行再利用或重新定位,旨在降低${\mathrm{{CO}}}_{2}$运输和存储成本。
Earlier in 2018, the UK government had announced that it would create its first net-zero carbon cluster in the North-East of England by 2040. The cluster aimed to capture six million tons of carbon emissions on a year basis from a gas-fired power plant and other industrial sources and was expected to start operation by 2030. (European Commission, 2019). Beyond CCUS, Drax, the UK’s largest power station, has been conducting tests of the BECCS project and has proposed a local hydrogen and CCS network. A large hydrogen and CCUS center were under plan at St Fergus in Scotland—a good location to add hydrogen directly to the power grid, since 35% of UK’s gas comes from onshore. In 2018, the project took step forward when the Oil and Gas Authority-the UK’s independent regulator and licensing authority for offshore ${\mathrm{{CO}}}_{2}$ storage-issued the first ${\mathrm{{CO}}}_{2}$ assessment and storage license (Committee on Climate Change, 2018).
早在2018年,英国政府就宣布将在2040年前在英格兰东北部创建首个净零碳集群。该集群旨在每年从一座燃气发电厂和其他工业源捕获600万吨碳排放,预计2030年开始运营。(欧盟委员会,2019年)。除了CCUS,英国最大的发电站德拉克斯一直在进行生物能源与碳捕集与封存(BECCS)项目测试,并提出了当地的氢气和碳捕集与封存网络。苏格兰圣弗格斯正在规划一个大型氢气和CCUS中心,由于英国35%的天然气来自陆上,这里是直接向电网添加氢气的理想地点。2018年,当英国独立的海上${\mathrm{{CO}}}_{2}$存储监管和许可机构——石油和天然气管理局颁发首个${\mathrm{{CO}}}_{2}$评估和存储许可证时(气候变化委员会,2018年),该项目向前迈进了一步。
Norway
挪威
Carbon taxes have been applied in a number of Nordic countries, but only Norway has effectively applied a carbon tax to trigger its CCUS investment. As early as in 1991, Norway introduced a carbon tax on carbon emissions from oil and gas production facilities. This move eventually led to two ${\mathrm{{CO}}}_{2}$ storage projects, Sleipner and Snøhvit, both operated by the Norwegian oil companies Statoil. In 2008, the EU ETS included Norway’s offshore oil and gas production emissions, which means that the operators of these facilities must also surrender one EU allowance (EUA) for every ton of ${\mathrm{{CO}}}_{2}$ emitted. But if the ${\mathrm{{CO}}}_{2}$ can be permanently stored, both the tax and EU ETS liabilities can be avoided, which provides powerful incentives to spur CCUS development. Consequently, Norway has been a major player in the global CCUS industry, reducing more than 20 million tons of ${\mathrm{{CO}}}_{2}$ through geological sequestration over the past two decades. Sleipner and Snøhvit are the first companies in the world to store ${\mathrm{{CO}}}_{2}$ emissions offshore and the only large-scale operational CCS facility in Europe.
一些北欧国家已实施碳税,但只有挪威有效地运用碳税来推动其碳捕集、利用与封存(CCUS)投资。早在1991年,挪威就对石油和天然气生产设施的碳排放开征碳税。此举最终促成了两个${\mathrm{{CO}}}_{2}$封存项目,即由挪威国家石油公司(Statoil)运营的 Sleipner 和 Snøhvit 项目。2008年,欧盟排放交易体系(EU ETS)将挪威的海上石油和天然气生产排放纳入其中,这意味着这些设施的运营商每吨${\mathrm{{CO}}}_{2}$排放还必须交出一个欧盟配额(EUA)。但如果${\mathrm{{CO}}}_{2}$能够永久封存,那么碳税和EU ETS的责任均可免除,这为刺激CCUS发展提供了强大动力。因此,挪威一直是全球CCUS行业的主要参与者,在过去二十年通过地质封存减少了超过2000万吨${\mathrm{{CO}}}_{2}$排放。Sleipner和Snøhvit是世界上首批在海上封存${\mathrm{{CO}}}_{2}$排放的公司,也是欧洲唯一的大型CCUS运营设施。
There is also a major CCS proposal that would involve capturing and transporting ${\mathrm{{CO}}}_{2}$ for offshore storage from multiple industrial facilities in Europe. The proposed facility will be operated by Equinor in partnership with Shell and Total, and it will ship and store ${\mathrm{{CO}}}_{2}$ mainly from northwest Europe (IEA,2016). FEED research (front-end engineering design) has been doing feasibility studies, and a drilling operation is planned to examine the Norwegian continental shelf for ${\mathrm{{CO}}}_{2}$ sequestration. Based on past success with the large-scale CCS deployment, the Norwegian government intends to use the proposed project as a catalyst for a wider CCS implementation in Europe (Overa, 2019).
还有一项重大的CCUS提案,该提案将涉及从欧洲多个工业设施捕获并运输${\mathrm{{CO}}}_{2}$用于海上封存。拟议中的设施将由挪威国家石油公司(Equinor)与壳牌(Shell)和道达尔(Total)合作运营,主要运输和封存来自西北欧的${\mathrm{{CO}}}_{2}$(国际能源署,2016年)。前端工程设计(FEED)研究一直在进行可行性研究,并计划进行钻探作业,以勘查挪威大陆架用于${\mathrm{{CO}}}_{2}$封存情况。基于过去大规模CCUS部署的成功经验,挪威政府打算将该拟议项目作为在欧洲更广泛实施CCUS的催化剂(奥韦拉,2019年)。
Indeed, the Norwegian government has rich experience in the CCUS industry. To illustrate, the government had set up Gassnova, a state-owned enterprise, which has represented the country’s investment as a shareholder of Technology Center Mong-stad, or TCM. TCM is the world’s largest center for testing and developing CCUS technologies. It has the capacity to capture up to 100,000 tons of ${\mathrm{{CO}}}_{2}$ emissions on a yearly basis, and has participated in the first full-scale CCUS project in Norway.
事实上,挪威政府在CCUS行业拥有丰富经验。举例来说,政府设立了国有企业Gassnova,它作为Technology Center Mongstad(简称TCM)的股东代表国家进行投资。TCM是世界上最大的CCUS技术测试与开发中心。它每年能够捕获多达10万吨${\mathrm{{CO}}}_{2}$排放,并参与了挪威首个全面的CCUS项目。
Middle East and Central Asia
中东和中亚
There is a growing recognition in the Middle East that CCUS will play an important role in supporting energy demand and shifting to clean energy. Indeed, led by Saudi Arabia and the United Arab Emirates (UAE), each country in the region has a large CCS facility. Whereas Abu Dhabi extracts ${\mathrm{{CO}}}_{2}$ from steel production, Saudi Arabia extracts ${\mathrm{{CO}}}_{2}$ from natural gas production with EOR technology. Abu Dhabi National Oil Company (ADNOC) has recently announced that ${\mathrm{{CO}}}_{2}$ emissions will be reduced by 10% by 2023, and ADNOC also plans to scale up CCS deployment in the next 10 years to capture 5 million tons of ${\mathrm{{CO}}}_{2}$ emissions by 2030 (Adnoc, 2019).
中东地区越来越认识到碳捕集、利用与封存(CCUS)在支持能源需求和向清洁能源转型方面将发挥重要作用。事实上,在沙特阿拉伯和阿拉伯联合酋长国(阿联酋)的引领下,该地区每个国家都有一个大型碳捕集与封存(CCS)设施。阿布扎比从钢铁生产中提取${\mathrm{{CO}}}_{2}$,而沙特阿拉伯利用提高采收率(EOR)技术从天然气生产中提取${\mathrm{{CO}}}_{2}$。阿布扎比国家石油公司(ADNOC)最近宣布,到2023年${\mathrm{{CO}}}_{2}$排放量将减少10%,并且ADNOC还计划在未来10年扩大CCS部署,到2030年捕获500万吨${\mathrm{{CO}}}_{2}$排放量(Adnoc,2019年)。
In 2019, Qatar announced that it plans to capture and store 5 million tons of ${\mathrm{{CO}}}_{2}$ emissions from its facilities by 2025 (Zawadzki &Kravtsova,2019). Qatar Petroleum also announced that it will build the largest CCS-EOR capture and storage facility in the Middle East and North Africa, with a capacity of 2.1 million tons of ${\mathrm{{CO}}}_{2}$ (Aljazeera,2019). Saudi Arabia and the UAE are members of the Ministerial Meeting on Innovation Tasks and Renewable Energy. Both countries have pledged to double public investment in the renewable energy research and development, and are active participants in the clean energy ministerial CCUS initiative.
2019年,卡塔尔宣布计划到2025年从其设施中捕获并封存500万吨${\mathrm{{CO}}}_{2}$排放量(Zawadzki & Kravtsova,2019年)。卡塔尔石油公司还宣布将在中东和北非建造最大的CCS-EOR捕集与封存设施,容量为210万吨${\mathrm{{CO}}}_{2}$(半岛电视台,《F0》)。沙特阿拉伯和阿联酋是创新任务与可再生能源部长级会议的成员。两国都承诺将可再生能源研发方面的公共投资增加一倍,并且是清洁能源部长级CCUS倡议的积极参与者。
Central Asia is one of the world’s most energy-intensive economic zone, and it will face enormous challenges to decarbonize the region’s energy system and to meet global climate goals. For example, in Kazakhstan, coal, oil, and natural gas have provided 98% of the country’s primary energy supply (IEA, 2019a). Given the country’s significant coal reserves and dependence on mining, Kazakhstan has a strong interest in CCUS technology. Eurasia Resources Group (ERG), a natural resources company, is currently studying how CCUS can be used to reduce ${\mathrm{{CO}}}_{2}$ emissions from generating electricity from fossil fuels. The preliminary proposal is to retrofit a coal-fired power plant with a ${20}\mathrm{{mt}}/$ year capacity via a CCUS pilot.
中亚是世界上能源密集程度最高的经济区之一,该地区在使能源系统脱碳以及实现全球气候目标方面将面临巨大挑战。例如,在哈萨克斯坦,煤炭、石油和天然气提供了该国98%的一次能源供应(国际能源署,2019a)。鉴于该国丰富煤炭储量以及对采矿的依赖,哈萨克斯坦对CCUS技术有着浓厚兴趣。自然资源公司欧亚资源集团(ERG)目前正在研究如何利用CCUS减少化石燃料发电产生的${\mathrm{{CO}}}_{2}$排放量。初步提议是通过一个CCUL试点项目对一座年产能为${20}\mathrm{{mt}}/$的燃煤电厂进行改造。
Asia Pacific
亚太地区
Over half of the world’s total ${\mathrm{{CO}}}_{2}$ emissions come from the Asia-Pacific region. The Asia-Pacific economies also produce over half of the world’s most emission-intensive commodities, such as iron, steel, and cement (Global Cement, 2017). Many countries, particularly in South-East Asia, already have and are planning to have more fossil-fuel power plants, and these plants will have a life cycle of decades ahead of them. With the inertia to develop a low-carbon strategy and the lack of an effective legal framework to promote investment in CCUS, the challenge to decarbonize these economies would seem to be enormous. That said, it is encouraging to note that in 2019, the Asia-Pacific region is a home to 12 large CCUS facilities in operation or at various stages of development (GCCSI, 2019).
全球${\mathrm{{CO}}}_{2}$排放总量的一半以上来自亚太地区。亚太地区经济体还生产了全球一半以上排放强度最高的商品,如钢铁和水泥(全球水泥,2017年)。许多国家,特别是东南亚国家,已经拥有并计划建设更多的化石燃料发电厂,这些发电厂的生命周期将长达数十年。由于制定低碳战略存在惰性,且缺乏促进碳捕集、利用与封存(CCUS)投资的有效法律框架,这些经济体实现脱碳的挑战似乎巨大。话虽如此,令人鼓舞的是,2019年亚太地区有12座大型CCUS设施正在运营或处于不同的开发阶段(全球碳捕集与封存研究所,2019年)。
Japan
日本
In Japan, the Act on Promotion of Global Warming Countermeasures of 1998 stipulated that the control of carbon emissions is the shared responsibility of governments, businesses and the general public. Recognizing the importance of low-carbon technologies, the Japanese government supports research on nuclear power, energy efficiency, renewable energy, and clean fossil energy utilization, including CCUS application. Japan’s efforts to develop CCUS has received the policy support and guidance of the Ministry of Economy, Trade, and Industry (METI) and the Ministry of the Environment (MOE).
在日本,1998年的《促进全球变暖对策法》规定,碳排放控制是政府、企业和公众的共同责任。认识到低碳技术的重要性,日本政府支持对核能、能源效率、可再生能源以及包括碳捕集、利用与封存(CCUS)应用在内的清洁化石能源利用进行研究。日本发展CCUS的努力得到了经济产业省(METI)和环境省(MOE)的政策支持与指导。
In 2012, the METI decided to carry out a CCS pilot in Tomakomai City, Hokkaido Prefecture. Earlier, the initial preparation work was commissioned by METI to Japan CCS Co (or JCCS) founded in 2008, which can be regarded as a special purpose vehicle (SPV) explicitly dedicated to the development of CCUS (Japan CCS, 2018). By way of the SPV, the Japanese government funded extensive studies on the various aspects-economic, social, environmental, and legal-of CCUS project, including possible ${\mathrm{{CO}}}_{2}$ storage sites. On the basis of JCCS experience, in 2019, the Japanese government announced its long-term plan to decarbonize its economy under the Paris Agreement. In the plan, CCUS was taken as an important mitigation technology, and the Japanese government decided to work with the private sector as well as other governments to implement a series of initiatives aimed at reducing obstacles to the commercial deployment of CCUS technologies (GCCSI, 2015, 2019).
2012年,经济产业省决定在北海道苫小牧市开展碳捕集与封存(CCS)试点项目。在此之前,经济产业省已将前期筹备工作委托给2008年成立的日本碳捕集与封存公司(JCCS),该公司可被视为专门致力于碳捕集、利用与封存(CCUS)开发的特殊目的公司(SPV)(日本碳捕集与封存公司,2018年)。通过该特殊目的公司,日本政府资助了对碳捕集、利用与封存(CCUS)项目的经济、社会、环境和法律等各方面的广泛研究,包括可能${\mathrm{{CO}}}_{2}$的储存地点。基于日本碳捕集与封存公司的经验,2019年,日本政府宣布了其在《巴黎协定》下实现经济脱碳的长期计划。在该计划中,碳捕集、利用与封存(CCUS)被视为一项重要的减排技术,日本政府决定与私营部门以及其他国家政府合作,实施一系列旨在减少碳捕集、利用与封存(CCUS)技术商业部署障碍的举措(全球碳捕集与封存研究所,2015年、2019年)。
One example of the Japanese government working to commercialize CCS is the Hydrogen Supply Chain program (HESC). The HESC pilot has involved a number of private businesses, e.g., J-Power, Iwatani, Kawasaki Heavy Industries, Marubeni, Sumitomo, and AGL. The pilot aims to demonstrate hydrogen production from coal with CCS. The construction of the gasifier began in November 2019 in Latropus Valley, Australia, and the project was expected to provide the first batch of hydrogen by 2021. If successful, it was hoped, the demonstration could lead to investment decision around the mid-2020s.
日本政府推动碳捕集与封存(CCS)商业化的一个例子是氢能供应链项目(HESC)。氢能供应链项目(HESC)试点涉及多家私营企业,如日本电源开发公司(J-Power)、岩谷产业株式会社(Iwatani)、川崎重工、丸红株式会社、住友商事株式会社和AGL。该试点旨在展示采用碳捕集与封存(CCS)技术的煤炭制氢过程。气化炉于2019年11月在澳大利亚拉特罗普斯山谷开工建设,该项目预计在2021年提供首批氢气。如果成功,有望在2020年代中期左右促成投资决策。
Australia
澳大利亚
Australia has a good prospect for CCUS applications, with sound legal and regulatory framework and large geological storage capacities. By making renewable energy and low-carbon technologies available for the same investment opportunities, in 2017, the Amendment to the Clean Energy Finance Corporation (CEFC) further removed barriers to CCUS investment. In Australia, CEFC is a government agency charged with overseeing a US$10 billion clean energy plan (GCCSI, 2019).
澳大利亚在碳捕集、利用与封存(CCUS)应用方面前景良好,拥有完善的法律法规框架和巨大的地质封存能力。通过为可再生能源和低碳技术提供相同的投资机会,2017年,清洁能源金融公司(CEFC)修正案进一步消除了CCUS投资的障碍。在澳大利亚,CEFC是一个负责监督一项100亿美元清洁能源计划的政府机构(全球碳捕集与封存研究所,2019年)。
In 2019, Australia announced that it would build the country’s largest and the world’s 19th major CCUS project with EOR technology. When fully operational, the project will have a ${\mathrm{{CO}}}_{2}$ storage capacity of 3.4-4 Mt/year-the largest dedicated geologic sequestration facility in the world. As a result, the Latropus Valley has been gaining momentum around the Hydrogen Supply Chain program (HESC) in collaboration with the Japanese government and private firms. Besides, Carbon Net in Victoria, Australia, has also been conducting feasibility studies to develop a commercial CCUS transport and storage site.
2019年,澳大利亚宣布将采用提高采收率(EOR)技术建设该国最大、全球第19个大型CCUS项目。全面投产后,该项目的${\mathrm{{CO}}}_{2}$封存能力将达到每年340 - 400万吨,成为世界上最大的专用地质封存设施。因此,拉特罗普斯山谷与日本政府和私营企业围绕氢供应链计划(HESC)开展合作的势头正日益增强。此外,澳大利亚维多利亚州的碳网公司也一直在进行可行性研究,以开发一个商业化的CCUS运输和封存场地。
India
印度
India, the world’s second-largest energy producer, saw carbon emissions increase by 4.8%, and coal consumption increase by 5% in 2018. However, the IEA has predicted that in a clean energy scenario, India can account for 20% of global industrial ${\mathrm{{CO}}}_{2}$ emissions captured and sequestered by 2060. As such, CCUS has an important role to play in India in the years ahead (IEA, 2019b).
印度是世界第二大能源生产国,2018年碳排放增长4.8%,煤炭消费增长5%。然而,国际能源署预测,在清洁能源情景下,到2060年印度能够占全球工业${\mathrm{{CO}}}_{2}$捕获和封存排放量的20%。因此,碳捕集、利用与封存(CCUS)在未来几年的印度将发挥重要作用(国际能源署,2019b)。
For example, Dalmia Cement, an Indian company, has announced that the company will achieve carbon negative by 2040, and that the company takes CCUS as one of the pathways to achieve this goal. In 2019, the company announced that it will build a large CCUS facility in Tamil Nadu, with an annual capacity to capture 500,000 tons of carbon emissions. To implement the plan, the company has been working with Carbon Clean Solutions, which will provide CCUS technology for the project. The company is also considering multiple carbon capture facilities for source-sink optimalization.
例如,印度公司达尔米亚水泥宣布,公司将在2040年前实现负碳,并将碳捕集、利用与封存(CCUS)作为实现这一目标的途径之一。2019年,该公司宣布将在泰米尔纳德邦建设一座大型碳捕集、利用与封存(CCUS)设施,年捕集碳排放量50万吨。为实施该计划,公司一直与碳清洁解决方案公司合作,后者将为该项目提供碳捕集、利用与封存(CCUS)技术。公司还在考虑多个碳捕集设施以实现源汇优化。
We end our global tour here. Table 3 highlights some of the key elements of the policy or legal framework for CCUS in the major regions/countries that we have just visited before heading back to China.
我们的全球之旅到此结束。在返回中国之前,表3重点介绍了我们刚刚走访的主要地区/国家碳捕集、利用与封存(CCUS)政策或法律框架的一些关键要素。
Table 3 CCUS Regulatory Framework in Major region/countries
表3 主要地区/国家的碳捕集、利用与封存(CCUS)监管框架
| Stage | Legal action | Examplar legislation | |
| EU | Identification | Identify CCUS as a preferred option to tackle climate change | e.g., via Green Paper: A European Strategy for Sustainable, Competitive and Secure Energy (2006) |
| Finance/Commercialization | Provide finance to CCUS projects and studies | Climate and Renewable Energy Package (2008) | |
| Institutionalization | form world's first detailed legislation on CCUS | CCUS Directive 2009/31 (2009) | |
| UK | Identification | Implement CCUS demonstration in power plants | Meeting the Energy Challenge: A White Paper on Energy (2007) |
| Finance/Commercialization | Identify CCUS as an important technical choice for electric power industry | Climate Change Act (2008) | |
| Institutionalization | include provisions on agreeing and using CCUS technologies | Energy Act (2010) | |
| US | Identification | Plan to control GHG emissions through capture and storage | Climate Change Technology Program (CCTP) (2006) |
| Finance/Commercialization | update Safe Drinking Water Act by including injection wells purely for carbon sequestration | Bill for Regulation for Underground Storage of Carbon Dioxide (2008) | |
| Institutionalization | provide ownership of stored gas and responsibility of transfer after CCUS projects shut down | House Bill to Include Carbon Storage Act into Legal System (HB259) (2010) |
(continued)
(续)
Table 3 (continued)
表3(续)
| Stage | Legal action | Examplar legislation | |
| Australia | Identification | Establish unified | Regulatory Guiding |
| CCUS framework | Principles for Carbon | ||
| within jurisdiction of | Dioxide Capture and | ||
| Australia | Geological Storage (2005) | ||
| Finance/Commercialization | N.A | N.A | |
| Institutionalization | provide legality of offshore storage of ${\mathrm{{CO}}}_{2}$ | Offshore Petroleum and Greenhouse Gas Storage Act (2006) |
4 Section 4
4 第4节
4.1 Reality Check on CCUS in China
4.1 中国碳捕集、利用与封存(CCUS)的现状审视
Climate change is increasingly becoming the focus of China’s developmental agenda in the past decade, so that the issue has been elevated to “the construction of eco-civilization” described by the Chinese government in many of its official documents.
在过去十年间,气候变化日益成为中国发展议程的重点,以至于该议题已被提升至中国政府诸多官方文件中所提及的“生态文明建设”高度。
In 2018, the Chinese central government set up a new and dedicated ministry, the Ministry of Ecology and Environment (MEE), and a big part of the new ministry’s mission has to deal with the challenge of climate change. Apparently, even if GDP growth was the top concern previously, the measurement is no longer enough. Now the indicators of carbon intensity must be taken into account in the GDP growth, since the single-minded GDP growth will destroy the ecosystem on Earth. As reflected by the evolving policy framework for low-carbon and green growth punctuated by the country’s FYPs, the trend has been clear: as the economy grew as a share of the world’s total, so does its mitigation and adaptation efforts. So far, the general contour is marked by three milestones: 2020 (carbon intensity); ${}^{9}$ 2030 (carbon peak) ${}^{10}$ ; and 2060 (carbon neutral).
2018年,中国中央政府设立了一个全新且专门的部门——生态环境部(MEE),该部门的一项重要使命便是应对气候变化挑战。显然,即便此前GDP增长是首要关注点,但如今这一衡量标准已不再充分。当前,在GDP增长中必须纳入碳强度指标,因为单纯追求GDP增长会破坏地球生态系统。正如中国五年规划所突显的低碳与绿色增长政策框架的演变所示,趋势已然明晰:随着经济在全球总量中占比的增长,其减缓与适应气候变化的努力也在同步提升。迄今为止,总体脉络由三个重要节点勾勒而成:2020年(碳强度);${}^{9}$ 2030年(碳达峰)${}^{10}$;以及2060年(碳中和)。
${}^{9}$ In 2009, China had pledged that it would lower carbon intensity of GDP by 40-45% by 2020 from the 2005 level. By the end of 2019, China had successfully surpassed that target by achieving a 48.1% reduction in carbon intensity of GDP. During the same period, non-fossil fuels as a share of its energy structure rose from 7.4% in 2005 to 15.3% in 2019. Based on this success, China has pledged to reduce carbon intensity of GDP by 65% by 2030 from the 2005 level, and to increase non-fossil fuels as a share of its energy structure to 25% by 2030. ${}^{10}$ By comparison, the EU peaked ${\mathrm{{CO}}}_{2}$ emissions in 2006 and the US in 2007. As part of its NDCs (nationally determined contributions) under of Paris Agreement, of late China has
${}^{9}$ 2009年,中国承诺到2020年将单位国内生产总值(GDP)的碳强度在2005年的基础上降低40 - 45%。截至2019年底,中国成功超额完成目标,单位GDP碳强度下降了48.1%。同期,非化石能源在能源结构中的占比从2005年的7.4%提高到2019年的15.3%。基于这一成功,中国承诺到2030年将单位GDP碳强度在2005年的基础上降低65%,并将非化石能源在能源结构中的占比提高到25%。${}^{10}$相比之下,欧盟的${\mathrm{{CO}}}_{2}$排放量在2006年达到峰值,美国则在2007年达到峰值。作为《巴黎协定》国家自主贡献(NDCs)的一部分,近期中国已
Currently China produces close to one third of the world’s ${\mathrm{{CO}}}_{2}$ emissions and urgently needs to reduce them. The Chinese government has viewed CCUS as a promising or strategic reserve technology for the direct abatement of ${\mathrm{{CO}}}_{2}$ emissions on large industrial scale, ${}^{11}$ and as such, the government has already put in place a workable regulatory and policy framework to shape its development. As it shown in Table 4, while there is no law dedicated to CCUS in China, CCUS projects are nonetheless regulated by new and relevant policies and existing laws, which, collectively and/or individually, cover the various aspects of CCUS projects. In the life cycle of a CCUS project, these aspects would include project approval, ownership, operation, environmental protection, safety standard, and closure process.
当前,中国的${\mathrm{{CO}}}_{2}$排放量接近全球总量的三分之一,亟需加以削减。中国政府将碳捕集、利用与封存(CCUS)视为在大型工业规模上直接减排${\mathrm{{CO}}}_{2}$的一项具有前景或战略性储备的技术,${}^{11}$ 因此,政府已构建起一套可行的监管与政策框架以推动其发展。如表4所示,尽管中国尚无专门针对CCUS的法律,但CCUS项目仍受新的相关政策及现行法律的规范,这些政策和法律共同或分别涵盖了CCUS项目的各个方面。在一个CCUS项目的生命周期中,这些方面包括项目审批、所有权、运营、环境保护、安全标准以及封存流程。
To see how these seemingly separate laws and policies work, let us elaborate on the process by setting up an imaginary CCUS project in China. The proposal for setting up such a project will go through the Construction Law and the Administrative Licensing Law to get project approval. Then ownership of the project will get recognized under the Property Law, the Land Management Law, as well as the Contract Law. While the project is in operation, the ${\mathrm{{CO}}}_{2}$ capture is under the purview of the Production Safety Law; ${\mathrm{{CO}}}_{2}$ transport is governed by the Highway Law, the Law on Protection of Oil and Gas Pipelines, as well as the Road Transport Regulations; and ${\mathrm{{CO}}}_{2}$ storage and utilization fall within the purview of the Mineral Resources Law. Meanwhile, the CCUS project has to comply with a variety of environment and safety regulations, such as the Environmental Impact Assessment Law, the Labor Law, the Production Safety Law, the Tort Liability Law, the Regulations on Hazardous Chemicals, and the Regulations for Safety and Supervision of Pressure Pipelines, etc. In the event that the CCUS project causes environmental damage or degradation, the Environmental Protection Law or the Marine Environmental Protection Law will be invoked.
为了解这些看似分散的法律和政策如何发挥作用,让我们通过在中国设立一个虚构的CCUS项目来详细阐述这一过程。设立此类项目的提议需经由《建筑法》和《行政许可法》以获得项目审批。随后,项目所有权将依据《物权法》、《土地管理法》以及《合同法》得到确认。项目运营期间,${\mathrm{{CO}}}_{2}$捕集受《安全生产法》管辖;${\mathrm{{CO}}}_{2}$运输由《公路法》、《石油天然气管道保护法》以及《道路运输条例》规制;而${\mathrm{{CO}}}_{2}$封存与利用则在《矿产资源法》范畴之内。与此同时,CCUS项目必须遵守各类环境与安全法规,诸如《环境影响评价法》、《劳动法》、《安全生产法》、《侵权责任法》、《危险化学品安全管理条例》以及《压力管道安全管理与监察规定》等。倘若CCUS项目造成环境损害或退化,将援引《环境保护法》或《海洋环境保护法》。
According to the Global Carbon Capture and Storage Institute (GCCSI), by the end of 2016, there were a total of 38 large-scale integrated projects (LSIPs). ${}^{12}$
根据全球碳捕集与封存研究所(GCCSI)的数据,截至2016年底,全球共有38个大型综合项目(LSIPs)。${}^{12}$
pledged to peak ${\mathrm{{CO}}}_{2}$ emissions prior to 2030. In addition, carbon intensity of GDP will drop to 65% from the 2005 level; 6 billion ${\mathrm{m}}^{3}$ of forest will be added to the 2005 level; non-fossil fuels, as a share of its energy structure, will increase to 25%; and capacity of wind and solar power will increase to 1.2 billion kw by 2030.
承诺在2030年前实现${\mathrm{{CO}}}_{2}$排放达峰。此外,国内生产总值的碳强度将比2005年水平下降至65%;森林面积将在2005年基础上新增600亿${\mathrm{m}}^{3}$;非化石能源在能源结构中的占比将提高至25%;到2030年,风能和太阳能发电装机容量将增至12亿千瓦。
11 Integrated with other technologies, CCUS may neutralize ${\mathrm{{CO}}}_{2}$ emission, or may remove ${\mathrm{{CO}}}_{2}$ from atmosphere, thus contributes to carbon neutrality, or even negative emission.
与其他技术相结合,碳捕集、利用与封存(CCUS)技术可以中和${\mathrm{{CO}}}_{2}$排放,或从大气中去除${\mathrm{{CO}}}_{2}$,从而助力碳中和,甚至实现负排放。
12 Large-scale integrated projects (LSIPs) refer to large-scale projects that integrate carbon capture, transport and storage, with an annual capture capacity of 800,000 tons for coal-fired power plants and with an annual capture capacity of 400,000 tons for other emissions-intensive sources.
大型综合项目(LSIPs)是指集碳捕集、运输和封存于一体的大型项目,其中燃煤电厂的年捕集能力为80万吨,其他排放密集型企业的年捕集能力为40万吨。
Table 4 Policy Framework for CCUS development in China
表4中国CCUS发展政策框架
| Authority | Dedicated Policy Documents | Year |
| MOST | Science and Technology Road map of China's CCUS Development | 2011 |
| MOST | National Special Plan for CCUS Technology Development in 12th FYP | 2013 |
| NDRC | Notice on Promoting CCUS Experiment and Demonstration | 2013 |
| MEPC | Notice on Strengthening Environmental Protection of CCUS Pilot Demonstration Projects | 2013 |
| Relevant Policy Documents | ||
| State Council | National Guideline on Medium- and Long-term Program for S&T Development (2006-2020) | 2006 |
| MOST | China's National Climate Change Program | 2007 |
| MOST | National S & T Actions on Climate Change | 2007 |
| MOST | National Plan for S & T Development (12th FYP) | 2011 |
| State Council | Working Plan on GHG Control (12th FYP) | 2011 |
| NDRC | Coal Industry Development (12th FYP) | 2012 |
| State Council | Energy Development Plan (12th FYP) | 2013 |
| State Council | Opinions on Accelerating the Development of Energy Saving and Environmental Protection Industry | 2013 |
| NDRC | National Key Low-carbon Technology Catalogue (I) | 2014 |
| NDRC | National Plan on Climate Change (2014-2020) | 2014 |
| State Council | Enhanced Actions on Climate Change: China's Nationally Determined Contributions | 2015 |
| NDRC | National Key Low-carbon Technology Catalogue (II) | 2015 |
| MEE | Opinion to Promote Super Low Emission in Iron/Steel Sector; Guideline for Super Low Emissions in Iron/Steel Sector | 2019 |
| MEE | National Measures for the Administration of Carbon Emissions Trading (for Trial Implementation) | 2021 |
Among them, 15 projects became operational and captured more than 29 million tons of ${\mathrm{{CO}}}_{2}$ . While most LSIPs are in the United States and China, those already in operation are mostly in the United States and Canada, and they mostly involve natural gas and coal-fired power plants. Likewise, most CCUS pilots in China are targeted at energy and coal-fired power plants, and none has existed in the steel sector so far. However, unlike the United States where Section 45Q of the Internal Revenue Code has been a potential tool to encourage CCUS development, in China, government supports thus far have been mainly targeted at R&D of CCUS pilots and mostly by the Ministry of Science and Technology (MOST). The latest Road Map for CCUS in China was released in May 2019. Recognizing the important role of CCUS as part of the country’s strategy for low-carbon and green growth, the road map sets out medium- and long-term goals and objectives for achieving low-carbon transformation through affordable, feasible, and reliable CCUS technologies (Asian Development Bank, 2015).
其中,15个项目已投入运营,捕集了超过2900万吨${\mathrm{{CO}}}_{2}$。虽然大多数大型综合项目在美国和中国,但已运营的项目大多在美国和加拿大,且大多涉及天然气和燃煤电厂。同样,中国的大多数CCUS试点项目都针对能源和燃煤电厂,到目前为止钢铁行业尚无此类项目。然而,与美国《国内税收法典》第45Q条作为鼓励CCUS发展的潜在工具不同,在中国,政府目前的支持主要针对CCUS试点项目的研发,且大多由科学技术部(MOST)提供。中国最新的CCUS路线图于2019年5月发布。认识到CCUS作为国家低碳和绿色增长战略一部分的重要作用,该路线图制定了通过经济实惠、可行且可靠的CCUS技术实现低碳转型的中长期目标(亚洲开发银行,2015年)。
In 2019, China has one large LSIP project in operation, two under construction, and five in early stage of development. The CNPC Jilin Oilfield ${\mathrm{{CO}}}_{2}$ -EOR demonstration, with a total injection capacity of 1.12 million tons, was the first LSIP in operation in China and the world’s 18th LSIP facility. Since 2007, the Sinopec Zhongyuan Oilfield has been injected with ${\mathrm{{CO}}}_{2}$ from a nearby chemical plant with an annual capacity of 100,000 tons. The Dunhua Methanol Plant, which began operation in 2015, could collect 100,000 tons of methanol on a yearly basis. These were all SOEs (state-owned enterprises). In terms of ownership, the Xinjiang Dunhua Petroleum Technology Co. was about the only private company deploying ${\mathrm{{CO}}}_{2}$ -EOR technology in China.
2019年,中国有1个大型综合项目已投入运营,2个正在建设,5个处于开发初期。中国石油吉林油田${\mathrm{{CO}}}_{2}$驱油示范项目总注入量为112万吨,是中国首个投入运营的大型综合项目,也是世界第18个大型综合项目设施。自2007年以来,中石化中原油田每年从附近化工厂注入10万吨${\mathrm{{CO}}}_{2}$。2015年投产的敦化甲醇厂每年可收集10万吨甲醇。这些都是国有企业。在所有权方面,新疆敦华石油技术有限公司是中国唯一一家采用${\mathrm{{CO}}}_{2}$驱油技术的民营企业。
After over a decade of R&D in CCUS technology, China has made remarkable progress in low-concentration ${\mathrm{{CO}}}_{2}$ capture, manufacturing of the carbon capture equipment, ${\mathrm{{CO}}}_{2}$ enhanced oil recovery (EOR), and corrosion prevention. For the carbon capture, China has built several carbon capture plants with capacity of over 100,000 tons each. In 2019, China captured about 2 million tons of ${\mathrm{{CO}}}_{2}$ emissions, representing about ${0.02}\%$ of the total ${\mathrm{{CO}}}_{2}$ emissions nation-wide, and ${\mathrm{{CO}}}_{2}$ captured as of 2019 added up to 3.7 million tons of ${\mathrm{{CO}}}_{2}$ emissions. As for the carbon transport, China has experimented with all three modes, i.e., pipeline, tanker and sea transport, and completed a total of ${50}\mathrm{\;{km}}$ of pipeline in length. For carbon storage, China has built an onshore saline aquifer ${\mathrm{{CO}}}_{2}$ geological storage demonstration project with a capacity of 100,000 tons/year, which, once included in saline aquifer storage projects, can increase the annual ${\mathrm{{CO}}}_{2}$ storage to nearly 1.1 million tons and the total ${\mathrm{{CO}}}_{2}$ storage to more than 5.6 million tons.
经过十多年的CCUS技术研发,中国在低浓度${\mathrm{{CO}}}_{2}$捕集、碳捕集设备制造、${\mathrm{{CO}}}_{2}$强化采油(EOR)和防腐方面取得了显著进展。在碳捕集方面,中国已建成多个年捕集能力超过10万吨的碳捕集厂。2019年,中国捕集了约200万吨${\mathrm{{CO}}}_{2}$排放,约占全国${\mathrm{{CO}}}_{2}$排放总量的${0.02}\%$,截至2019年累计捕集的${\mathrm{{CO}}}_{2}$达370万吨${\mathrm{{CO}}}_{2}$排放。在碳运输方面,中国已对管道、油轮和海运三种方式进行了试验,建成管道总长度达${50}\mathrm{\;{km}}$。在碳封存方面,中国已建成一个年容量为10万吨的陆上咸水层${\mathrm{{CO}}}_{2}$地质封存示范项目,一旦纳入咸水层封存项目,每年的${\mathrm{{CO}}}_{2}$封存量可增至近110万吨,${\mathrm{{CO}}}_{2}$封存总量可超过560万吨。
In all, by 2020 China has established about 30 CCUS projects, with extensive demonstration of the various industrial aspects or processes of CCUS technology. It has set up several ${\mathrm{{CO}}}_{2}$ capture projects with a capacity of 100,000 tons or more each, and built ${\mathrm{{CO}}}_{2}$ transport pipelines with a combined length of ${50}\mathrm{\;{km}}$ . As discussed earlier, so far most of these CCUS projects are in the energy sector and none in the cement or the steel sector.
总体而言,到2020年中国已建成约30个碳捕集、利用与封存(CCUS)项目,对CCUS技术的各个工业环节或流程进行了广泛示范。中国已建成若干个单个容量达10万吨及以上的${\mathrm{{CO}}}_{2}$捕集项目,并建成了总长为${50}\mathrm{\;{km}}$的${\mathrm{{CO}}}_{2}$输送管道。如前文所述,到目前为止,这些CCUS项目大多集中在能源领域,水泥或钢铁领域尚无项目。
4.2 Challenges Ahead
4.2 未来挑战
The Paris Agreement sets out a global action plan to set the world on track to avoid dangerous climate change by limiting global warming below $2{}^{ \circ }\mathrm{C}$ above pre-industrial levels in the long-term, and to pursue best efforts to limit the increase in warming to ${1.5}^{ \circ }\mathrm{C}$ . To achieve this target, the Agreement emphasized the need for global GHG emissions to peak as soon as possible and called for the contracting states to the Agreement to reduce ${\mathrm{{CO}}}_{2}$ emissions with best available (BATs).
《巴黎协定》制定了一项全球行动计划,以使世界走上正轨,通过长期将全球变暖限制在比工业化前水平高$2{}^{ \circ }\mathrm{C}$以下,来避免危险的气候变化,并尽最大努力将升温幅度限制在${1.5}^{ \circ }\mathrm{C}$以内。为实现这一目标,《协定》强调全球温室气体排放需要尽快达到峰值,并呼吁《协定》缔约国使用最佳可得技术(BATs)减少${\mathrm{{CO}}}_{2}$排放。
Generally speaking, there are three categories of BATs, readily available or still on the horizon, i.e., net-low carbon technology, net-zero carbon technology, and net-negative carbon technology. Along this spectrum of technologies of mitigation and adaptation to the impact of climate change, carbon capture, utilization and storage (CCUS) belongs to the last category, i.e., net-negative carbon technology-a topic that Part II of this study will further explore and discuss in more depth.
一般来说,现有或即将出现的最佳可用技术有三类,即低碳技术、零碳技术和负碳技术。在应对气候变化影响的减缓和适应技术范围内,碳捕获、利用与封存(CCUS)属于最后一类,即负碳技术——本研究的第二部分将进一步深入探讨和讨论这一主题。
A reality check of the existing CCS demonstration projects around the world suggests that while China is not too behind on this technology, more must be done to realize its potential in the years ahead now that the country has pledged to peak ${\mathrm{{CO}}}_{2}$ emissions prior to 2030 and to achieve carbon neutrality by 2060. More specifically, while China has made remarkable progress in CCUS demonstrations, they are mostly in the power sector but none in the steel sector so far. The fact is that the iron/steel sector in China contributes more than half of the world’s total ${\mathrm{{CO}}}_{2}$ emissions from iron/steel making, and about ${15}\%$ of China’s total ${\mathrm{{CO}}}_{2}$ emissions from the industry. And the policy review by this study on climate mitigation and adaptation in China indicates that the iron/steel sector so far has relied mainly on net-low carbon technologies in its strategic shift toward green growth.
对全球现有碳捕集与封存示范项目的实际情况进行审视后发现,尽管中国在这项技术上并不太落后,但鉴于中国已承诺在2030年前实现${\mathrm{{CO}}}_{2}$排放达峰,并在2060年前实现碳中和,未来几年要挖掘其潜力仍需付出更多努力。具体而言,虽然中国在碳捕集、利用与封存示范项目方面取得了显著进展,但大多集中在电力行业,钢铁行业目前尚无此类项目。事实上,中国钢铁行业的${\mathrm{{CO}}}_{2}$排放量占全球钢铁生产总排放量的一半以上,约占中国工业${\mathrm{{CO}}}_{2}$排放总量的${15}\%$。本研究对中国气候缓解与适应政策的审查表明,钢铁行业在向绿色增长的战略转型中,目前主要依赖净低碳技术。
Looking forward, the immediate challenge is to explore and indeed, ascertain the best strategic pathways or road maps for the deployment of CCUS to decarbonize the steel sector-a topic that the next chapter of this study will follow upon.
展望未来,当务之急是探索并确定部署碳捕集、利用与封存(CCUS)技术以使钢铁行业脱碳的最佳战略路径或路线图——本研究的下一章将探讨这一主题。
According to IEA, there will be a 50% chance to control the global temperature rise below two degrees by 2050 when the ${\mathrm{{CO}}}_{2}$ emissions are cut by 60% from the 2013 level and emission reductions total 1000 billion tons. By then, CCUS-derived emission reductions have to reach 6.1 billion tons, which implies an average annual increase of ${50}\%$ from the current level of 2.9 million tons. Specifically, it means that an estimate of 6000 CCS projects, each with a storage capacity of over one million ${\mathrm{{tCO}}}_{2}$ , must be deployed by 2050. At present, however, there are only 3 CCS projects with a storage capacity of over one million ${\mathrm{{tCO}}}_{2}$ globally. Given the current status of CCUS, the challenge will be enormous, so will be the potential, especially in China, and for two reasons. First, currently most CCUS projects are in natural gas and coal-fired power plants, and are not yet well deployed in sectors such as steel, cement, and biotransformation industries. Second, of the total industrial ${\mathrm{{CO}}}_{2}$ emissions in China, the power sector accounts for about ${50}\%$ , steel ${15}\%$ , and cement ${15}\%$ , and as high as ${85}\%$ of the current energy structure in China is based on fossil-fuels, of which coal takes up 58% and oil 19%.
根据国际能源署的数据,若到2050年将${\mathrm{{CO}}}_{2}$排放量在2013年的水平上削减60%,减排总量达到10000亿吨,那么将全球气温升幅控制在2摄氏度以内的可能性为50%。届时,碳捕集、利用与封存(CCUS)带来的减排量必须达到61亿吨,这意味着要在当前290万吨的水平上实现年均增长${50}\%$。具体而言,这意味着到2050年必须部署约6000个碳捕集、利用与封存项目,每个项目的封存能力超过100万${\mathrm{{tCO}}}_{2}$。然而目前,全球仅有3个封存能力超过100万${\mathrm{{tCO}}}_{2}$的碳捕集、利用与封存项目。鉴于碳捕集、利用与封存的现状,挑战巨大,但潜力同样巨大,尤其是在中国,原因有二。其一,目前大多数碳捕集、利用与封存项目都在天然气和燃煤发电厂,尚未在钢铁、水泥和生物转化等行业广泛应用。其二,在中国工业${\mathrm{{CO}}}_{2}$排放总量中,电力部门约占${50}\%$,钢铁占${15}\%$,水泥占${15}\%$,而且中国目前高达${85}\%$的能源结构以化石燃料为基础,其中煤炭占58%,石油占19%。
Acronym Full spelling
首字母缩略词 完整拼写
BATs Best available technologies
最佳可得技术(BATs)
CCER China certified emission reduction
中国核证自愿减排量
CCS Carbon capture and storage
碳捕获与封存
CCUS Carbon capture, utilization and storage
碳捕获、利用与封存
CNPC China National Petroleum Corporation
中国石油天然气集团公司
EOR Enhance oil recovery
提高石油采收率
ETS Emission-trading system
ETS排放交易系统
FYP Five Year Plan
五年计划
GCCSI Global Carbon Capture and Storage Institute
全球碳捕集与封存研究所
GHG Greenhouse gas
温室气体
IEA International Energy Agency
国际能源署
IPCC Intergovernmental Panel on Climate Change
政府间气候变化专门委员会
LSIPs Large-scale integrated projects
大型综合项目
MEE Ministry of Ecology and Environment
生态环境部
MIIT Ministry of Industry and Information Technology
工业和信息化部
MNR Ministry of Natural Resources
自然资源部
MOF Ministry of Finance
财政部
MOST Ministry of Science and Technology
科学技术部
MOT Ministry of Transport
交通运输部
NCSC National Center for Climate Strategy and International Cooperation
国家气候战略中心
NDRC National Development and Reform Commission
国家发展和改革委员会
NPC National People’s Congress
全国人民代表大会
NRA National Railway Administration
国家铁路局
NTCC National Technical Committee on Carbon Management
全国碳管理标准化技术委员会
SAC Standardization Administration of China
中国国家标准化管理委员会
SACC Strategy Analysis of Climate in China
中国气候的SACC战略分析
SFA State Forestry Administration
国家林业局
UNFCCC United Nations Framework Convention on Climate Change
《联合国气候变化框架公约》
References
参考文献
Adnoc. (2019). ADNOC reinforces leadership role and commitment to environmental stewardship as it strengthens its position as one of the lowest greenhouse gas emitters in the oil and gas industry. https://www.adnoc.ae/en/news-and-media/press-releases/2019/ adnoc-reinforces-leadership-role-and-commitment-to-environmental-stewardship
Aljazeera. (2019). Qatar building large ${\mathrm{{CO}}}_{2}$ storage plant. https://www.aljazeera.com/eco nomy/2019/10/8/qatar-building-large-co2-storage-plant
Asian Development Bank (ADB). (2015). Roadmap for carbon capture and storage demonstration and deployment in the People’s Republic of China. Manila.
China Steel Statistics. Beijing: China Iron and Steel Association (Various years).
CCUS Advisory Group. (2019). Investment frameworks for development of CCUS in the UK. CAG final report. http://www.ccsassociation.org/files/4615/6386/6542/CCUS_Advi sory_Final_Report_22_July_2019.pdf.
Clean Air Task Force. (2019). State and utility climate change targets shift to carbon reductions, technology diversity. https://www.catf.us/wp-content/uploads/2019/05/State-and-Uti lity-Climate-Change-Targets.pdf
Committee on Climate Change. (2018). Reducing UK emissions. 2018 progress report to parliament. https://www.theccc.org.uk/wp-content/uploads/201806/CCC-2018- Progress-Report-to-Parliament.pdf
Department of the Treasury, USA. (2018). Carbon oxide sequestration credit. https://www.irs/pub/irs-access/f8933_accessible.pdf
European Commission. (2019). The potential for CCS and CCU in Europe. https://ec.europa.eu/info/sites/info/files/iogp_-_report_-_ccs_ccu.pdf
Global CCS Institute (Global Carbon Capture and Storage Institute). (2009). Strategic analysis of the global status of CCS: 2009. Melbourne, Australia.
Global CCS Institute (Global Carbon Capture and Storage Institute). (2015). The global status of CCS: 2015. Melbourne, Australia.
Global CCS Institute (Global Carbon Capture and Storage Institute). (2016). The global status of CCS: 2016. Melbourne, Australia.
Global CCS Institute (Global Carbon Capture and Storage Institute). (2019). The global status of CCS: 2019. Melbourne, Australia.
Global Cement. (2017). Global cement top 100 report 2017-2018. http://www.globalcement.com/magazine/articles/1054-global-cement-top-100-report-2017-2018.
Government of Canada. (2008). The global status of CCS, 2028. http://www.globalcement.com/resources/global-status-report
International Energy Agency (IEA). (2019a). World outlook 2019. Paris: IEA. https://www.iea.org/reports/world-energy-outlook-2019
International Energy Agency (IEA). (2019b). Transforming industry through CCUS. http:// www.iea.org/reports/tranforming-industry-through-ccus
International Energy Agency (IEA). (2020). World energy outlook 2020. https://www.iea.org/ reports/world-energy-outlook-2020
IPCC. (2018). In V. Masson-Delmotte, P. Zhai, H.-O. Pörtner, D. Roberts, J. Skea, P. R. Shukla, A. Pirani, W. Moufouma-Okia, C. Péan, R. Pidcock, S. Connors, J. B. R. Matthews, Y. Chen, X. Zhou, M.I. Gomis, E. Lonnoy, T. Maycock, M. Tignor, & T. Waterfield (Eds.), Global warming of ${1.5}^{ \circ }\mathrm{C}$ . An IPCC special report on the impacts of global warming of ${1.5}^{ \circ }\mathrm{C}$ above pre-industrial levels and related global greenhouse gas emission pathways, in the context of strengthening the global response to the threat of climate change, sustainable development, and efforts to eradicate poverty. Geneva, Switzerland: World Meteorological Organization.
Japan CCS. (2018). From Japan to the world—Aiming for the practical use of CCS Technology in Japan. http://www.Japanccs.com/en/corporae/message.php
Jiang, K., et al. (2020). China’s carbon capture, utilization and storage (CCUS) policy: A critical review. Renewable and Sustainable Energy Reviews., 119, 109601. https://doi.org/ 10.1016/j.rser.2019.109601
Li, J. (2011). Carbon capture, utilization and storage (CCUS) Activities in China. Sanya, China. http://www.cagsinfo.net/__data/assets/pdf_file/0009/81576/1-3-carbon-capture-utilisation-storage-activities-China.pdf.Accessed March 5, 2021.
Li, X. (2020). The road map of China’s steel industry: Reduction. Beijing, China: Metallurgical Industry Press.
Liu, Q. (2016). CCUS development in China: Outlook, projects and policies. Japan. http:// jp.globalccsinstitute.com/sites/jp.globalccsinstitute.com/files/content/media_release/122 850/files/S2_CCUS_development_in_China_Liu_qiang_NCSC.pdf. Accessed June 16.
National Bureau of Statistics of the People’s Republic of China. http://www.stats.gov.cn
Overa, S. (2019). Telling the Norwegian CCS story, Northern lights: A European CO2 transport and storage project. https://www.globalccsinstitute.com/news-media/events/telling-the-norwegian-ccs-story-part-3-northern-lights-a-european-co2-transport-and-storage-pro ject/
PBL Netherlands Environmental Assessment Agency. (2021). Energy and climate change. The Hague. https://www.pbl.nl/en/topics/energy-and-climate-change
Shan, Y., et al. (2018). China ${\mathrm{{CO}}}_{2}$ emission accounts 1997-2015. Scientific Data, 5, 170201. https://doi.org/10.1038/sdata.2017.201
Shan, Y., et al. (2020). China ${\mathrm{{CO}}}_{2}$ emission accounts 2016-2017. Scientific Data, 7,54. https://doi.org/10.1038/s41597-020-0393-y
U.S. Environmental Protection Agency. (2021). Greenhouse Gas (GHG) emissions. Washington, D.C. https://www.epa.gov/ghgemissions
Website of Aisixiang. (2021, 5 March). http://www.aisixiang.com/zhuanti/175.html
World Steel Association (, Worldsteel, & ). (2019). World steel in figures 2019. Belgium.
Zawadzki, S., & Kravtsova, E. (2019). Qatar opens CO2storage plant, targets 5 mln T a year by 2025. https://www.nasdaq.com/articles/qatar-opens-co2-storage-plant-targets-5- mln-t-a-year-by-2025-2019-10-08
Zhang, X. (2014). Status of CCUS in China. Changsha, China. https://iea.blob.core.windows.net/assets/imports/events/76/CarboncaptureandstoragedevelopmentsinChina.pdf.Accessed March 5, 2021.
Drawing Strategic Roadmap of Decarbonization for the Steel Sector
绘制钢铁行业脱碳战略路线图
Jun Fu, Min Wang, and Qimin Cai
傅军、王敏、蔡启敏
The steel sector is one of the largest industrial sources of ${\mathrm{{CO}}}_{2}$ emissions, contributing around $7\%$ of the global energy sector ${\mathrm{{CO}}}_{2}$ emissions (including process emissions) (IEA, 2020). ${}^{1}$ In the overall scheme of this study, one may take China’s steel sector as a window through which to see the magnitude of mitigation and
钢铁行业是${\mathrm{{CO}}}_{2}$排放的最大工业来源之一,约占全球能源行业${\mathrm{{CO}}}_{2}$排放(包括工艺排放)的$7\%$(国际能源署,2叭0年)。${}^{1}$在本研究的整体框架中,可以将中国钢铁行业作为一个窗口,从中了解减排的规模以及
${}^{1}$ IEA (2020), Iron and Steel Technology Roadmap, IEA, Paris, https://www.iea.org/reports/ iron-and-steel-technology-roadmap.
${}^{1}$ 国际能源署(2020年),《钢铁技术路线图》,国际能源署,巴黎,https://www.iea.org/reports/iron-and-steel-technology-roadmap。
${}^{2}$ In terms of ${\mathrm{{CO}}}_{2}$ emissions, the power, the steel, and the cement sectors are the three largest ${\mathrm{{CO}}}_{2}$ emitters in China. As a share of total industrial ${\mathrm{{CO}}}_{2}$ emissions, the power sector accounts for about ${50}\%$ , the steel sector ${15}\%$ , and the cement another ${50}\%$ . Compared with the other two sectors, the steel sector is arguably more representative of the complexity that China faces in its decarbonization efforts, if only because it is more diverse in production processes and product portiforlios than those of the power and cement sectors. This would make the MRV (monitoring, reporting and verification) system—a necessary component of carbon market— more difficult. The point is that if a system is ready to deal with complexity, it is relatively easy to deal with simplicity. For discussion on carbon market or ETS (emissions trading system) in China, see Chapter 5 of this study.
${}^{2}$在${\mathrm{{CO}}}_{2}$排放方面,电力、钢铁和水泥行业是中国三大${\mathrm{{CO}}}_{2}$排放源。就工业${\mathrm{{CO}}}_{2}$排放总量而言,电力行业约占${50}\%$,钢铁行业占${15}\%$,水泥行业占另外的${50}\%$。与其他两个行业相比,钢铁行业更能代表中国在脱碳努力中面临的复杂性,这仅仅是因为其生产过程和产品组合比电力和水泥行业更多样化。这将使碳市场的必要组成部分——监测、报告和核查(MRV)系统变得更加困难。关键在于,如果一个系统能够应对复杂性,那么应对简单性就相对容易。关于中国碳市场或排放交易体系(ETS)的讨论,请参阅本研究的第5章。
In writing this chapter, the authors benefited from two seminars on climate change given at Peking Uiversity by LI Junfeng, formerly director-general of the National Center for Climate Change Strategy and International Cooperation (NCSC) in China, as well as from several talks with LI Xinchuang, President of China Metallorgical Industry Planning and Research Institute.
在撰写本章时,作者受益于中国国家应对气候变化战略与国际合作中心(NCSC)前主任李俊峰在北京大学举办的两次关于气候变化的研讨会,以及与中国冶金工业规划研究院院长李新创的多次交谈。
J. Fu ( $\boxtimes$ ) $\cdot$ M. Wang
傅杰($\boxtimes$)$\cdot$ 王萌
National School of Development, Peking University, Beijing, China
中国北京北京大学国家发展研究院
Q. Cai
蔡Q.
National Center for Climate Change Strategy and International Cooperation (NCSC), Beijing, China
中国北京国家应对气候变化战略研究和国际合作中心(NCSC)
adaptation efforts under climate change. ${}^{2}$ Indeed, the steel sector has been playing an important role in the country’s strategy for developing a low-carbon economy. To highlight the point, a few more statistics shall suffice here.
气候变化下的适应努力。${}^{2}$ 事实上,钢铁行业在该国发展低碳经济的战略中一直发挥着重要作用。为突出这一点,这里再列举一些统计数据就足够了。
In 2020, the world’s total crude steel output was 1.864 billion tons, to which China contributed 56.5% (World Steel Association, 2021). On average, an integrated blast furnace steel plant produces approximated 2 tons of ${\mathrm{{CO}}}_{2}$ per ton of crude steel produced. Given these simple yet powerful numbers, it is critical to explore ways to decarbonize the steel sector in China, especially when Chinese central government announced to peak ${\mathrm{{CO}}}_{2}$ emissions by 2030 and work towards carbon neutrality by 2060. One important technological option for direct reduction of ${\mathrm{{CO}}}_{2}$ emissions is carbon capture, utilization and storage (CCUS), especially after the current paraphernalia of technologies at indirect ${\mathrm{{CO}}}_{2}$ emission reductions via energy savings and energy efficiency has increasingly exhausted their marginal effects. We must plan ahead. For over the next 40 years, the ambition is no longer low carbon now but carbon neural.
2020年,全球粗钢总产量为18.64亿吨,其中中国占56.5%(世界钢铁协会,2021年)。平均而言,一座综合高炉炼钢厂每生产一吨粗钢会产生约2吨${\mathrm{{CO}}}_{2}$。鉴于这些简单却有力的数据,探索中国钢铁行业脱碳的方法至关重要,尤其是在中国中央政府宣布到2030年实现${\mathrm{{CO}}}_{2}$排放达峰并在2060年前实现碳中和的情况下。直接减少${\mathrm{{CO}}}_{2}$排放的一个重要技术选择是碳捕获、利用与封存(CCUS),特别是在当前通过节能和提高能源效率间接减少${\mathrm{{CO}}}_{2}$排放的一系列技术的边际效应已日益耗尽之后。我们必须提前规划。因为在未来40年里,目标不再是低碳,而是碳中性。
In line with the above, this chapter looks at the steel sector as a critical part of China’s strategy for developing a green economy. The chapter is structured into four sections. Section 1 provides an overview of the growth trends of China’s steel sector, in terms of production, consumption, and ${\mathrm{{CO}}}_{2}$ emissions. Section 2 examines various policy instruments by the Chinese government to decarbonize the steel sector, in light of the country’s new pledge to cap ${\mathrm{{CO}}}_{2}$ emissions prior to 2030 and achieve carbon neutrality in 2060. In Section 3, we introduce a simulation model in connection with CCUS for the steel sector to plan ahead and shift from indirect to direct ${\mathrm{{CO}}}_{2}$ emission reductions. Section 4 concludes by presenting a roadmap for the development of CCUS in the steel sector, as an indispensable part of the country’s strategy to achieve carbon neutrality in 2060.
基于上述内容,本章将钢铁行业视为中国绿色经济发展战略的关键部分。本章分为四个部分。第一部分概述了中国钢铁行业在生产、消费和${\mathrm{{CO}}}_{2}$排放方面的增长趋势。第二部分根据中国在2030年前控制${\mathrm{{CO}}}_{2}$排放并在2060年实现碳中和的新承诺,研究了中国政府为钢铁行业脱碳而采取的各种政策工具。在第三部分中,我们引入了一个与钢铁行业碳捕集、利用与封存相关的模拟模型,以便提前规划并从间接${\mathrm{{CO}}}_{2}$减排转向直接${\mathrm{{CO}}}_{2}$减排。第四部分通过提出钢铁行业碳捕集、利用与封存的发展路线图进行总结,这是中国在2060年实现碳中和战略中不可或缺的一部分。
1 Overview of China’s Steel Sector
1 中国钢铁行业概述
1.1 Steel Production
1.1钢铁生产
Since China started the reform and opening-up strategy in 1978, the economy witnessed tremendous growth with real GDP on average growing around 9% annually, which together with the large size of the economy has led to the explosive growth of steel production in China. The annual production of crude steel in China on average grows around 11% during 1978-2020, increasing from 31.78 million tons (around 4.4% of world production) in 1978 to 1.05 billion tons in 2020.3
自1978年中国启动改革开放战略以来,经济实现了巨大增长,实际国内生产总值平均每年增长约9%,加上庞大的经济规模,导致中国钢铁产量呈爆发式增长。1978 - 2020年期间,中国粗钢年产量平均增长约11%,从1978年的3178万吨(约占世界产量的4.4%)增至2020年的10.5亿吨。
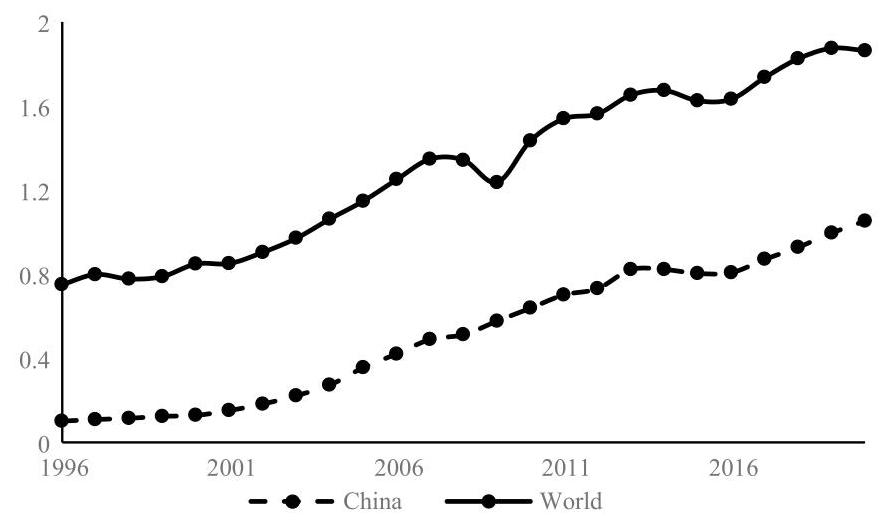
Fig. 1 Total Production of Crude Steel (billion tons), 1996-2020
图1 1996 - 2020年粗钢总产量(十亿吨)
China surpassed Japan as the world largest producer of crude steel in 1996 and has overwhelmingly dominated the worlds’ steel industry afterwards by keeping astonishing production growth. The total production of crude steel in 2020 is 10.4 times the total production in 1996. The global share of China’s production of crude steel has continuously increased from 15.1% in 1996 to 56.5% in 2020. By contrast, the global share of crude steel production from the second largest producer to the 6th largest producer, EU, India, Japan, Russia and U.S., is 7.4%, 5.3%, 4.5%, 3.9% and 3.9% respectively in 2020.
1996年中国超过日本成为世界最大粗钢生产国,此后凭借惊人的产量增长在全球钢铁行业占据绝对主导地位。2020年粗钢总产量是1996年的10.4倍。中国粗钢产量的全球份额从1996年的15.1%持续增至2020年的56.5%。相比之下,2020年第二大至第六大生产国欧盟、印度、日本、俄罗斯和美国的粗钢产量全球份额分别为7.4%、5.3%、4.5%、3.9%和3.9%。
Figure 1 shows a clear trend of China’s production of crude steel in the past two decades. Driven by the new round economic boom especially after China joined the WTO, the growth rate of annual production of crude steel in China reached to a historic high, 21% on average during 2001-2007. After the global financial crisis in 2008, the average growth rate of annual production of crude steel in China fell to 9% during 2008-2013.
图1清晰显示了中国过去二十年粗钢产量的趋势。受新一轮经济繁荣尤其是中国加入世贸组织后的推动,中国粗钢年产量增长率达到历史高位,2001 - 2007年期间平均为21%。2008年全球金融危机后,2008 - 2013年中国粗钢年产量平均增长率降至9%。
Largely due to weak demand, the steel sector was rather dismal during 2014- 2016, in which the growth rate of annual production of crude steel was 0.04%, -2.25% and 0.47% respectively in 2014, 2015 and 2016. Chinese steel producers experienced their worst year in 2015, when the capacity utilization rate of the whole steel sector was only 65% and around half of China’s steel mills made loss with many struggling to exit from the sector. The sector has since been under enormous pressures to shift towards a quality-over-quantity and low-carbon development path.
主要由于需求疲软,2014 - 2016年钢铁行业相当低迷,2014、2015和2016年粗钢年产量增长率分别为0.04%、 - 2.25%和0.47%。2015年中国钢铁生产商经历了最艰难的一年,当时整个钢铁行业产能利用率仅65%,约半数中国钢厂亏损,许多钢厂艰难求生。此后该行业面临巨大压力,转向质量优先和低碳发展道路。
3 The data on steel production in different countries used in this paper are from World Steel Statistical Yearbook published by World Steel Association, unless otherwise stated.
除非另有说明,本文中不同国家钢铁产量数据来自世界钢铁协会发布的《世界钢铁统计年鉴》。
At that time, China government unveiled a series of policies to resolve the steel industry overcapacity problem, such as Opinions on Reducing Overcapacity and Removing Development Obstacles in the Iron/Steel Sector (No.6 [2016] of the State Council). These policies aimed to phase out backward and highly polluting capacity and curtail capacity expansion by setting new higher standards. In total, 100-150 million tons of crude steel production capacity were closed down during the 13th Fifth Year Plan period (2016-2020).
当时,中国政府出台了一系列政策解决钢铁行业产能过剩问题,如《国务院关于化解产能严重过剩矛盾的指导意见》(国发〔2013〕41号)。这些政策旨在淘汰落后和高污染产能,并通过设定更高新标准限制产能扩张。“十三五”期间(2016 - 2020年)共关停1 - 1.5亿吨粗钢产能。
The steel sector recovered quickly after the aggressive policy intervention and is keeping a stable growth rate during 2017-2020. The production of crude steel grows around 6.86% per year in this most recent period. Even when the economy growth was slowed down by the COVID-19 pandemic, the total production of crude steel in China still kept a high growth rate, 5.69%, in 2020. Given the expectation that China may retain average annual real GDP growth rate around 4%-5% in the next three decades (until 2050) and the urbanization rate may increase from 60% in 2020 to 80% in 2050 (United Nations, 2018; Wang, 2020), it is quite likely that China’s steel production would keep steady growth in the foreseeable future. In international perspective, in 2020, steel output per capita in China was about 10 tons, 25 tons in the U.S. and 45 tons in Japan.
经过积极政策干预后,钢铁行业迅速复苏,并在2017 - 2020年保持稳定增长率。最近这段时间粗钢产量每年增长约6.86%。即使在新冠疫情导致经济增长放缓的情况下,2020年中国粗钢总产量仍保持较高增长率5.69%。鉴于预计未来三十年(至2050年)中国可能保持年均实际国内生产总值增长率约4% - 5%,且城镇化率可能从2020年的60%增至2050年的80%(联合国,2018;王,2020),中国钢铁产量在可预见未来很可能保持稳定增长。从国际角度看,2020年中国的人均钢铁产量约为10吨,美国为25吨,日本为45吨。
1.2 Steel Consumption
1.2钢铁消费
Figure 2 presents the apparent steel use in China and the whole world between 1996 and 2019. Not surprisingly, as the steel output is mainly consumed by domestic users, Fig. 2 has exactly the same pattern as Fig. 1. In 2019, the global share of apparent steel use of the world’s 6 largest steel users, China, EU, Indian, USA, Japan and South Korea, is respectively 50%, 9.13%, 5.76%, 5.74%, 3.69% and 2.94%. Evidently China is not only the largest producer but also the largest consumer, dominating the world steel consumption market.
图2展示了1996年至2019年期间中国和全球的表观钢铁消费量。不出所料,由于钢铁产量主要由国内用户消费,图2与图1的模式完全相同。2019年,全球六大钢铁消费国(中国、欧盟、印度、美国、日本和韩国)的表观钢铁消费量占全球份额分别为50%、9.13%、5.76%、5.74%、3.69%和2.94%。显然,中国不仅是最大的生产国,也是最大的消费国,主导着世界钢铁消费市场。
Moreover, the difference between the global shares of production and consumption of the steel in China also reveals that China is the largest net exporter in the world steel market. It need to note that the total domestic production of crude steel was always lower than the total amount of apparent steel use in China until 2005. That is, China has become a net steel exporter since (including) 2006.
此外,中国钢铁生产和消费的全球份额差异也表明,中国是世界钢铁市场上最大的净出口国。需要注意的是,直到2005年,中国国内粗钢总产量一直低于中国表观钢铁消费总量。也就是说,自2006年(包括2006年)以来,中国已成为钢铁净出口国。
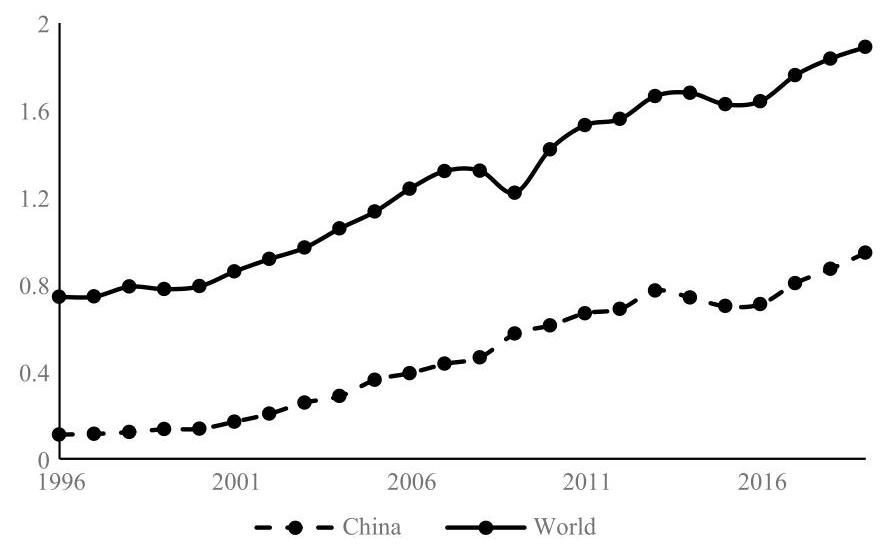
Fig. 2 Steel Use (crude steel equivalent, billion tons), 1996-2019
图2 1996 - 2019年钢铁消费量(粗钢当量,十亿吨)
1.3 Energy Use
1.3 能源使用
Given the explosive growth of steel production and consumption in China, the energy use and carbon emissions from the steel sector are great challenges not only for the sector but also for the whole economy. Fortunately, the energy intensity, measured by the energy consumption per ton of steel, has declined significantly, especially since the 1990s, largely due to policy-induced process restructuring and optimization.
鉴于中国钢铁生产和消费的迅猛增长,钢铁行业的能源使用和碳排放不仅对该行业,而且对整个经济都是巨大挑战。幸运的是,以每吨钢铁的能源消耗来衡量的能源强度已大幅下降,特别是自20世纪90年代以来,这主要归功于政策引导的工艺重组和优化。
The energy consumption per ton of steel was 2040 kgce in 1980 and almost halved to 1240 kgce in 1999. As shown in Fig. 2, the engery intensity of the steel production fell by 39% during 2000-2019, decreasing from 906 kgce/t in 2000 to 553 kgce/t in 2019. However, given the fast growth of the steel production in the period, the total energy use of the steel sector was increased by 8.6 times, from 116 mtce in 2000 to 996 mtce in 2019. ${}^{4}$ As a consequence, the steel sector has become an increasingly large source of air pollutant emissions and carbon emissions.
1980年每吨钢铁的能源消耗为2040千克标准煤,到1999年几乎减半至1240千克标准煤。如图2所示,2000 - 2019年期间钢铁生产的能源强度下降了39%,从2000年的906千克标准煤/吨降至2019年的553千克标准煤/吨。然而,鉴于该时期钢铁产量的快速增长,钢铁行业的总能源使用量增长了8.6倍,从2000年的1.16亿吨标准煤增至2019年的9.96亿吨标准煤。${}^{4}$ 因此,钢铁行业已成为越来越大的空气污染物排放和碳排放源。
Since 2000, under the obligatory energy saving and emission reduction policies, the steel’s energy intensity in China kept decreasing significantly until 2006. On average, the energy intensity decreased by 8.6 per year during 2000-2006.
自2000年以来,在强制性节能减排政策下,中国钢铁的能源强度在2006年之前持续显著下降。2000 - 2006年期间,能源强度平均每年下降率为8.6%。
${}^{4}$ The total energy use is calculated by multiplying the total production of crude steel with the energy intensity.
${}^{4}$ 总能源使用量是通过粗钢总产量乘以能源强度来计算的。
The decreasing trend of the energy intensity slowed down after 2006. In terms of energy intensity, it only fell at 1.11% per year during 2007-2019 and reached at 553 kgce/ton in 2019. By comparison, the world average energy intensity of crude steel production was ${678}\mathrm{{kgce}}/$ ton in ${2019.}^{5}$ Thus, the current level of the energy intensity in China is not only much lower than the world average but also close to that in developed countries. That said, both the trend and the level of the energy intensity also indicate that there is limited room for China’s steel sector to improve the energy efficiency. Hence, unless there are technological breakthroughs, we expect that the growth of the energy use in China’s steel sector would keep pace with the growth of the steel production.
2006年之后能源强度的下降趋势放缓。就能源强度而言,2007 - 2019年期间仅以每年1.11%的速度下降,2019年降至553千克标准煤/吨。相比之下,世界粗钢生产的平均能源强度为${678}\mathrm{{kgce}}/$ 吨,在${2019.}^{5}$ 因此,中国目前的能源强度水平不仅远低于世界平均水平,而且接近发达国家水平。也就是说,能源强度的趋势和水平也表明中国钢铁行业提高能源效率的空间有限。因此,除非有技术突破,我们预计中国钢铁行业的能源使用增长将与钢铁产量增长同步。
1.4 Carbon Emissions
1.4 碳排放
China has surpassed U.S. as the world largest carbon emitter since 2005. In 2019, China’s ${\mathrm{{CO}}}_{2}$ emissions are almost twice of ${\mathrm{{CO}}}_{2}$ emissions in U.S., and China alone was responsible for ${29}\%$ of global ${\mathrm{{CO}}}_{2}$ emissions (BP,2020). China’s steel sector is a resource- and energy-intensive industry, and the afore-mentioned explosive growth of the production and energy use lead to the rapid growth of ${\mathrm{{CO}}}_{2}$ emissions in the sector. China’s steel sector is now emitting around 15% of the country’s total ${\mathrm{{CO}}}_{2}$ emissions, right after the largest industry emitter, power sector, which accounts for around ${50}\%$ of total ${\mathrm{{CO}}}_{2}$ emissions in China. The steel industry is under great pressure to curtain the growth of ${\mathrm{{CO}}}_{2}$ emissions.
自2005年以来,中国已超过美国成为全球最大的碳排放国。2019年,中国的${\mathrm{{CO}}}_{2}$排放量几乎是美国的两倍,仅中国就占全球${\mathrm{{CO}}}_{2}$排放量的${29}\%$(英国石油公司,2020年)。中国钢铁行业是资源和能源密集型产业,上述产量和能源使用的爆发式增长导致该行业${\mathrm{{CO}}}_{2}$排放量迅速增长。中国钢铁行业目前的${\mathrm{{CO}}}_{2}$排放量约占全国总排放量的15%,仅次于最大的行业排放源——电力行业,后者约占中国${\mathrm{{CO}}}_{2}$排放总量的${50}\%$。钢铁行业在遏制${\mathrm{{CO}}}_{2}$排放增长方面面临巨大压力。
It is understood that ${\mathrm{{CO}}}_{2}$ emission from the blast furnaces (BFs) steelmaking process is about around 2-2.2 tonnes for per tonne of steel, while that from the electric arc furnace (EAF) process is far lower at ${800}\mathrm{\;{kg}}$ per tonne of steel. The BFs steelmaking process (alternatively known as long process) however accounts for around 90% of China’s steel capacity. On Dec. 31, 2020, the Ministry of Information and Technology released guidelines for the domestic steel industrial development for 2021-2025. According to the guidelines, EAF steelmaking should be lifted to ${15}\%$ or ${20}\%$ by ${2025.}^{6}$ However, since the products of EAFs do not well fit into the steel demand of manufacturing industries which are the key end users in China, there is also limited room for further expansion of the proportion of EAFs.
据了解,高炉炼钢过程的${\mathrm{{CO}}}_{2}$排放量约为每吨钢2 - 2.2吨,而电弧炉炼钢过程的排放量则低得多,为每吨钢${800}\mathrm{\;{kg}}$。然而,高炉炼钢法(又称长流程)约占中国钢铁产能的90%。2020年12月31日,工业和信息化部发布了《2021 - 2025年国内钢铁工业发展指南》。根据该指南,到${2025.}^{6}$,电弧炉炼钢占比应提高到${15}\%$或${20}\%$。然而,由于电弧炉产品不太适合中国制造业这一关键终端用户的钢铁需求,电弧炉占比进一步扩大的空间也有限。
${}^{5}$ Data source: Sustainable steel—Indicators 2020 and steel applications, World Steel Association.
${}^{5}$ 数据来源:《2020年可持续钢铁指标及钢铁应用》,世界钢铁协会。
${}^{6}$ At the present, EAF steelmaking in China accounts for about ${10}\%$ ; and the rest is long process. By international comparison, EAF accounts for about 47% globally (excluding China). That for many advanced economies such as the US has reached 90%, indicating significant scope for the Chinese steel sector to reduce ${\mathrm{{CO}}}_{2}$ emissions in this area, i.e. from long process to EAF, in the years to come.
${}^{6}$ 目前,中国电弧炉炼钢约占${10}\%$;其余为长流程炼钢。经国际比较,电弧炉炼钢在全球(不包括中国)约占47%。在美国等许多发达经济体,这一比例已达90%,这表明中国钢铁行业在未来几年通过从长流程炼钢转向电弧炉炼钢来减少${\mathrm{{CO}}}_{2}$排放的空间很大。
Recently, Chinese President Xi Jinping announced aggressive actions to tackle climate changes. In particular, China will peak ${\mathrm{{CO}}}_{2}$ emissions before 2030, increase non-fossil fuel around ${25}\%$ by 2030 and cut its ${\mathrm{{CO}}}_{2}$ emissions per unit of GDP, or carbon intensity, by more than 65% from 2005 levels by 2030. By comparison, the earlier targets that the Chinese government had pledged in 2015 were to peak ${\mathrm{{CO}}}_{2}$ emissions around 2030 (could be after 2030), increase non-fossil fuel around 20% by 2030 and lower carbon intensity by 60-65% by 2030. In line with China’s new pledge of climate targets, China has launched national carbon trading market for the power sector in early 2021 and it is expected to cover the steel sector in the near future. ${}^{7}$ And given the fact that the marginal effects of existing technologies on raising energy efficiency and reducing carbon intensity has been on decline, the industry has to explore new ways to decarbonize iron and steel making, such as EAF and hydrogen metallurgy in the short run. ${}^{8}$ But in the long run, CCUS remains another promising option to decarbonize the steel sector.
最近,中国国家主席习近平宣布了应对气候变化的积极行动。特别是,中国将在2030年前实现${\mathrm{{CO}}}_{2}$排放达峰,到2030年非化石能源占比提高约${25}\%$,并将单位GDP${\mathrm{{CO}}}_{2}$排放量(即碳强度)比2005年水平降低65%以上。相比之下,中国政府在2015年承诺的早期目标是在2030年左右(可能在2030年之后)实现${\mathrm{{CO}}}_{2}$排放达峰,到2030年非化石能源占比提高20%左右,到2030年碳强度降低60 - 65%。根据中国新的气候目标承诺,中国于2021年初启动了电力行业全国碳排放交易市场,预计不久后将覆盖钢铁行业。${}^{7}$ 鉴于现有技术提高能源效率和降低碳强度的边际效应一直在下降,该行业必须在短期内探索钢铁制造脱碳的新方法,如电弧炉炼钢和氢冶金。${}^{8}$ 但从长远来看,碳捕获、利用与封存(CCUS)仍是钢铁行业脱碳的另一个有前景的选择。
2 Review of Low Carbon Policy
2 低碳政策回顾
2.1 Low-Carbon Policy for the Steel Sector
2.1 钢铁行业低碳政策
During the 11th FYP (2006-2010), the steel sector in China expanded rapidly, and the policies focused on energy saving and emission reduction. During the 12th FYP (2011-2015), to resolve the overcapacity problem resulted from the great expansion of the steel sector in the 11th FYP, the policies focused on cutting excess capacity, which was regarded as a representative example of “supply-side reforms” at that time. A key component of the 13th FYP (2016-2020) was “eco-civilization”, which translated into action plans for industrial firms, means decarbonization and green growth.
在“十一五”规划(2006 - 2010年)期间,中国钢铁行业迅速扩张,政策重点是节能减排。在“十二五”规划(2011 - 2015年)期间,为解决“十一五”规划中钢铁行业大规模扩张导致的产能过剩问题,政策重点是削减过剩产能,这在当时被视为“供给侧改革”的一个典型例子。“十三五”规划(2016 - 2020年)的一个关键组成部分是“生态文明”,这转化为针对工业企业的行动计划,意味着脱碳和绿色增长。
${}^{7}$ For more on the development of China’s carbon market or ETS (emissions trading system), see Chapters 5 and 6 and this study.
${}^{7}$ 关于中国碳市场或排放交易体系(ETS)的更多发展情况,见第5章和第6章以及本研究。
${}^{8}$ HBIS, China’s second largest steel group company in collaboration with TENOVA, an Italian corporation, has been exploring ways to deploy hydrogen technologies in steel-making since 2019. If successful, the new technology can produce steel at a much lower rate of ${\mathrm{{CO}}}_{2}$ emissions, about ${125}{\mathrm{{kgCO}}}_{2}/$ ton, which is approximately $1/{12}$ of the current rate of ${\mathrm{{CO}}}_{2}$ emissions in long-process steelmaking in China. This is strong indication that, in addition to CCUS, China has been exploring all BATS (best available technologies) to reduce ${\mathrm{{CO}}}_{2}$ emissions.
${}^{8}$ 中国第二大钢铁集团公司河钢集团自2019年以来一直与意大利公司达涅利合作,探索在炼钢中应用氢技术的方法。如果成功,这项新技术可以以低得多的${\mathrm{{CO}}}_{2}$排放率生产钢铁,约为${125}{\mathrm{{kgCO}}}_{2}/$吨,这大约是中国长流程炼钢目前${\mathrm{{CO}}}_{2}$排放率的$1/{12}$。这有力地表明,除了碳捕获、利用与封存(CCUS)技术外,中国一直在探索所有最佳可行技术(BATS)以减少${\mathrm{{CO}}}_{2}$排放。
The policies imposed on the steel sector in the last two decades could be summarized in three categories:
过去二十年对钢铁行业实施的政策可归纳为三类:
(1) Restructuring the steel industry by resolving the over-capacity. Most policies belonged to this category focused on eliminating existing backward production capacity. ${}^{9}$ These policies generally set a target on existing production capacity that could not meet a certain standard and should be closed down. Some policies might specifically aimed to close down backward processes and backward products. ${}^{10}$ Some policies, such as Opinions on Reducing Overcapacityand Removing Development Obstacles in Iron/SteelSector rleased by State Council in 2016, were issued to curtail the expansion of new capacity.
(1) 通过解决产能过剩问题来重组钢铁行业。大多数属于这一类别的政策侧重于淘汰现有的落后生产能力。${}^{9}$ 这些政策通常针对不符合一定标准应关闭的现有生产能力设定目标。一些政策可能专门旨在关闭落后工艺和落后产品。${}^{10}$ 一些政策,如2016年国务院发布的《关于钢铁行业化解过剩产能实现脱困发展的意见》,旨在遏制新产能的扩张。
(2) Enhancing the energy efficiency of steel production. The policies in this category generally set the steel sector’s environmental standards and energy use standards, such as standards of pollutant emissions, energy intensity, energy saving and energy use in major production processes. ${}^{11}$
(2) 提高钢铁生产的能源效率。这一类别的政策通常设定钢铁行业的环境标准和能源使用标准,如污染物排放标准、能源强度、主要生产过程中的节能和能源使用标准。${}^{11}$
9 Development Policies for Iron/Steel Industry, NDRC, 2005; Notice on Controlling Total Production Capacity, Eliminating Backward Production Capacity and Accelerating Restructuring in Steel Sector, NDRC, 2006; Notice on Accelerating Restructuring Industries with Excess Capacity, State Council, 2006; Notice on Accelerating Industrial Restructuring with Excess Capacity, State Council, 2006; Notice on Comprehensive Work Plan for Energy Saving and Emission Reduction, State Council, 2007; Letter of Responsibility for Closedown and Elimination of Backward Production Capacity, NDRC, et al., 2007; Regarding Curbing Overcapacity, Redundancy, and Guiding Sound Development in Some Industries, forwarded by State Council, 2009; Notice on Further Stepping up the Efforts to Eliminate Backward Production Capacity, State Council, 2010; Notice on Further Efforts to Ensure Energy Conservation and Emission Reduction Targets during the 11th FYP, State Council, 2010; Opinion on Further Efforts to Achieve Energy Saving, Emissions Reduction Emissions, and Acceleration of Restructuring in the Steel Sector, State Council, 2010; Notice on Checking up Iron/Steel Projects, State Council, et al. 2010; Guiding Opinion on Resolving Contradictions of Serious Overcapacity, State Council, 2013; Notice on Effectively Conducting Production Capacity Replacement for Some Industries with Serious Overcapacity, MIIT, 2014; Notice on Formulating Targets and Plans for Elimination of Backward and Excessive Capacity in Key Industries in the 13th FYP, 2014, MIIT, 2014; Notice of Measures for Capacity Replacement in Sectors with Serious Overcapacity, MIIT, 2015.
9 《钢铁产业发展政策》,国家发展和改革委员会,2005年;《关于控制钢铁行业生产总量淘汰落后生产能力加快结构调整的通知》,国家发展和改革委员会,2006年;《关于加快推进产能过剩行业结构调整的通知》,国务院,2006年;《关于加快推进产能过剩行业结构调整的通知》,国务院,2006年;《节能减排综合性工作方案》,国务院,2007年;《关于下达关停淘汰落后生产能力责任书的通知》,国家发展和改革委员会等,2007年;《关于抑制部分行业产能过剩和重复建设引导产业健康发展的若干意见》,国务院转发,2009年;《关于进一步加大工作力度确保完成“十一五”节能减排目标的通知》,国务院,2010年;《关于进一步加大工作力度实现节能减排目标加快钢铁行业结构调整的意见》,国务院,2010年;《关于开展钢铁项目清理工作的通知》,国务院等,2010年;《关于化解产能严重过剩矛盾的指导意见》,国务院,2013年;《关于做好部分产能严重过剩行业产能置换工作的通知》,工业和信息化部,2014年;《关于制定“十三五”重点行业淘汰落后和过剩产能目标计划的通知》,工业和信息化部,2014年;《关于印发部分产能严重过剩行业产能置换实施办法的通知》,工业和信息化部,2015年。
10 Industrial Restructuring Guidance-Catalogues. NDRC, 2005; Guidance Catalogue for Elimination of Backward Processes, Equipment, and Products in Some Industries, MIIT, 2010; Industrial Restructuring Guidance Catalogue. NDRC (2011), 2011; Catalogue of Value-Added Tax Preferences for Products and Services in Comprehensive Use of Resources, 2015. State Council, MOF, STA.
10 《产业结构调整指导目录》,国家发展和改革委员会,2005年;《部分工业行业淘汰落后生产工艺装备和产品指导目录》,工业和信息化部,2010年;《产业结构调整指导目录》,国家发展和改革委员会(2011年),2011年;《资源综合利用产品和劳务增值税优惠目录》,国务院,财政部,国家税务总局,2015年。
11 The Norm of Energy Consumption per Unit Product of Major Individual Process of Crude Steel Manufacturing Process, 2008, Standardization Administration of China; Access Conditions and Management Measures for Production and Operation of Existing Iron and Steel Enterprises, 2009, MIIT; Norms and Conditions for Production and Operation of Iron and
11 《粗钢生产主要工序单位产品能源消耗限额》,2008年,中国国家标准化管理委员会;《现有钢铁企业生产经营准入条件及管理办法》,2009年,工业和信息化部;《钢铁行业生产经营规范条件》
(3) Changing the energy mix in steel production toward low carbon mix. The policies in this category mainly aimed to promote the development of EAFs technology in steel production, such as proposing the proportion of EAFs that should be used in the steel production and setting an upper limit for energy intensity of the EAF technology. ${}^{12}$
(3) 在钢铁生产中改变能源结构,向低碳结构转变。此类政策主要旨在促进电弧炉技术在钢铁生产中的发展,例如提出电弧炉在钢铁生产中应使用的比例,并设定电弧炉技术的能源强度上限。${}^{12}$
Many policy initiatives could be traced back to the 12th FYP or even earlier, but they were intensively issued during the 13th FYP right after China government signed Paris Agreement in 2015. Given the above mentioned upgrade of China’s 2030 climate change targets, we expect more low-carbon policies will be made and enforced in the steel sector.
许多政策举措可以追溯到“十二五”规划甚至更早,但在2015年中国政府签署《巴黎协定》后,它们在“十三五”规划期间密集出台。鉴于上述中国2030年气候变化目标的升级,我们预计钢铁行业将制定并实施更多低碳政策。
2.2 Policy Effects
2.2 政策效果
Under the intensive policy implementation, the steel sector succeeded in cutting excessive capacity dramatically since the 11th FYP (2006-2010). 72.24 million tons of inefficient capacity was slashed during the 11th FYP. Another 94.86 million tons of inefficient steel capacity was phased out during the 12th FYP (2011-2015). During the 13th FYP, 100-150 million tons of capacity, including 90 million tons of backward capacity, were eliminated.
在密集的政策实施下,自“十一五”规划(2006 - 2010年)以来,钢铁行业成功大幅削减了过剩产能。“十一五”规划期间削减了7224万吨低效产能。“十二五”规划(2011 - 2015年)期间又淘汰了9486万吨低效钢铁产能。“十三五”规划期间,淘汰了1亿 - 1.5亿吨产能,其中包括9000万吨落后产能。
Steel Industry, 2010, MIIT; Guiding Opinions on Mergers and Reorganizations in the Iron and Steel Industry, 2010, MIIT; Design Criterion for Energy Saving of Iron and Steel Industry, 2010, the Ministry of Housing and Urban-Rural Development (MOHURD); Guiding Opinions on Energy Conservation and Emission Reduction in the Iron and Steel Industry, 2010, MIIT; The Notice on Printing and Issuing the Development Strategy and Immediate Action Plan for Circular Economy, 2013, the State Council; The Norm of Energy Consumption per Unit Product of Major Individual Process of Crude Steel Manufacturing Process (GB21256), 2014; Access Conditions for the Coking Industry (Revised in 2014), 2014, MIIT; Norms and Conditions for the Iron and Steel Industry (Revised in 2015), 2015, MIIT; Requirements of the Greenhouse Gas Emission Accounting and Reporting: Iron and Steel Production Enterprises, 2016, NDRC; Code for Design of Energy Saving of Iron and Steel Industry (Draft for Comment), 2017, MOHURD; The Norm of Energy Consumption per Unit Product of Coke (GB21342); The Norm of Energy Consumption per Unit Product of Steel Making Electric Arc Furnace (GB 32,050-2015).
《钢铁行业规范条件(2010年修订)》,工业和信息化部;《关于促进钢铁企业兼并重组的指导意见》,工业和信息化部;《钢铁工业节能设计规范》,住房和城乡建设部;《关于钢铁行业节能减排的指导意见》,工业和信息化部;《关于印发循环经济发展战略及近期行动计划的通知》,国务院;《粗钢生产主要工序单位产品能源消耗限额》(GB21256),2014年;《焦化行业准入条件(2014年修订)》,工业和信息化部;《钢铁行业规范条件(2015年修订)》,工业和信息化部;《温室气体排放核算与报告要求:钢铁生产企业》,国家发展和改革委员会;《钢铁工业节能设计规范(征求意见稿)》,住房和城乡建设部;《焦炭单位产品能源消耗限额》(GB21342);《炼钢电炉单位产品能源消耗限额》(GB 32050 - 2015)。
12 Interim Measures for the Management of Financial Incentive Funds for Energy Saving Technological Transformation, 2007, MOF, NDRC; The 13th Five-Year Plan for the Development of the Scrap Iron and Steel Industry, 2016, China Association of Metalscrap Utilization (CAMU); The Standard of Energy Consumption per Unit Product of Steel Making Electric Arc Furnace, 2016, General Administration of Quality Supervision, Inspection and Quarantine.
《节能技术改造财政奖励资金管理暂行办法》,财政部、国家发展和改革委员会;《废钢铁行业“十三五”发展规划》,中国废钢铁应用协会;《炼钢电炉单位产品能源消耗限额》,国家质量监督检验检疫总局。
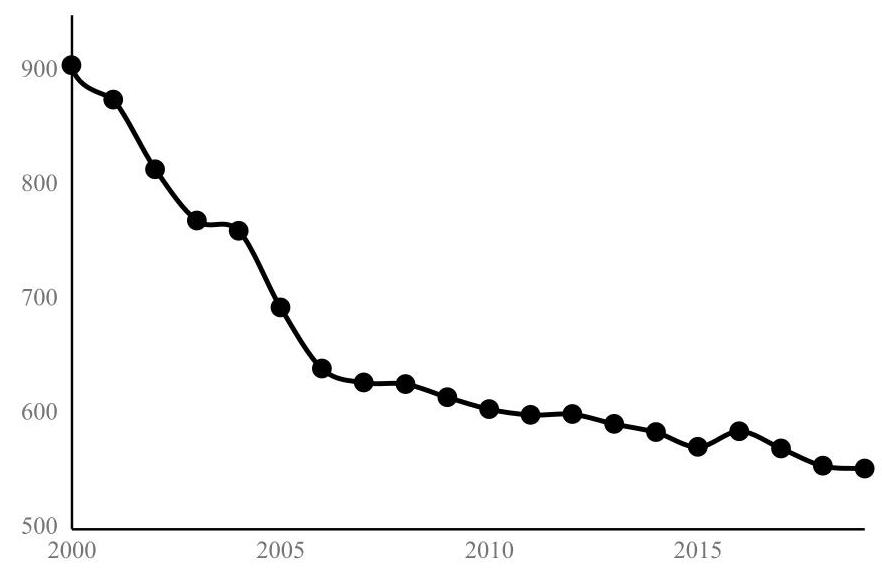
Fig. 3 Energy consumption of Steel in China (Kgce/t), 2000-2019 (data source China Steel Industry Yearbook)
图3 2000 - 2019年中国钢铁能耗(千克标准煤/吨)(数据来源:《中国钢铁工业年鉴》)
In the meantime, more advanced production facilities with better technologies were put into use. As the result, energy efficiency was significantly increased. During the 11th FYP, large- and medium-sized steel plants witnessed a 12.9% drop in energy intensity, falling to 605 kgce in 2010. The energy intensity further decreased to 572 kgce/t in the end of the 12th FYP and 553 kgce/t in 2019. During the 13th FYP, an ${18}\% {\mathrm{{CO}}}_{2}$ emission reduction per unit of value added was set as a mandatory target in the steel sector.
与此同时,更多技术更先进的生产设施投入使用。结果,能源效率显著提高。“十一五”规划期间,大中型钢铁厂能源强度下降了12.9%,2010年降至605千克标准煤。“十二五”规划期末,能源强度进一步降至572千克标准煤/吨,2019年降至553千克标准煤/吨。“十三五”规划期间,钢铁行业设定了单位增加值${18}\% {\mathrm{{CO}}}_{2}$减排的强制性目标。
2.3 Policies Regarding CCUS
2.3 关于碳捕集、利用与封存的政策
Comparing to fossil fuel saving technologies which indirectly reduce the ${\mathrm{{CO}}}_{2}$ emissions, CCUS is the only available end-of-pipe technology capable of directly reducing ${\mathrm{{CO}}}_{2}$ emissions, although it is not commercial yet. ${}^{13}$ The Chinese government takes CCUS as an emerging and strategical technology, and has been actively promoting the development. So far, the government has published more than 26 CCUS-related policy documents at the national level. ${}^{14}$
与间接减少${\mathrm{{CO}}}_{2}$排放的化石燃料节约技术相比,碳捕集、利用与封存是唯一可用的能够直接减少${\mathrm{{CO}}}_{2}$排放的末端技术,尽管它尚未商业化。${}^{13}$中国政府将碳捕集、利用与封存视为一项新兴战略技术,并一直在积极推动其发展。到目前为止,政府已在国家层面发布了26份以上与碳捕集、利用与封存相关的政策文件。${}^{14}$
13 We will further elaborate CCUS in a systematical and technical fashion in Chapters 3 and 4.
13我们将在第3章和第4章以系统和技术的方式进一步详细阐述碳捕集、利用与封存。
14 They included rules, plans, notices and opinions released by the State Council and different ministries and commissions, which can be classified into five categories, namely technology promoting, demonstration support, target setting, environmental management, and others.
14它们包括国务院和不同部委发布的规则、计划、通知和意见,可分为五类,即技术推广、示范支持、目标设定、环境管理等。
During the 12th FYP (2011-2015), the MOST promulgated the National Special Plan for Development of CCUS Technology in 2013. The Plan set out priorities for CCUS pilots and demonstrations. In the same year, NDRC issued a Circular on Promoting Experiment and Demonstration of CCUS. The Circular provided support and guidance for CCUS tests and demonstrations. Also in 2013, MEP issued a Circular on Strengthening Environmental Protection of CCUS Projects. MEP’s Circular aimed to enhance environmental protection of CCUS projects, including environmental impact assessment (EIA), monitoring, risk prevention, and damage controls. In 2016, NDRC published the Action Plan for Innovations in Energy Technology Revolution (2016-2030). The Action Plan puts CCUS on its roadmap of key innovations in the energy sector for the 2016-2050 period.
在“十二五”规划(2011 - 2015年)期间,科技部于2013年发布了《碳捕集、利用与封存技术发展专项规划》。该规划确定了碳捕集、利用与封存试点和示范的优先事项。同年,国家发展和改革委员会发布了《关于推进碳捕集、利用与封存试验示范的通知》。该通知为碳捕集、利用与封存的测试和示范提供了支持和指导。同样在2013年,环境保护部发布了《关于加强碳捕集、利用与封存项目环境保护工作的通知》。环境保护部的通知旨在加强碳捕集、利用与封存项目的环境保护,包括环境影响评价(EIA)、监测、风险预防和损害控制。2016年,国家发展和改革委员会发布了《能源技术革命创新行动计划(20(16 - 2030年)》。该行动计划将碳捕集、利用与封存列入了2016 - 2050年能源领域关键创新路线图。
3 Simulation of Deployment of CCUS Technology
3 CCUS技术部署模拟
3.1 SACC with CCUS
3.1 中国气候战略分析与碳捕集、利用与封存(CCUS)
In this section, we present Strategy Analysis of Climate in China (SACC) in connection with CCUS. SACC is a simulation model developed by the National Center for Climate Change Strategy and International Cooperation (NCSC) in China. NCSC researchers ${}^{15}$ collaborated closely with Peking University researchers on this study to figure out the long-term trends of energy use and ${\mathrm{{CO}}}_{2}$ emissions. Key parameters of SACC in connection CCUS in the steel sector are illustrated in Figs. 3, 4 and 5.
在本节中,我们介绍与碳捕集、利用与封存(CCUS)相关的中国气候战略分析(SACC)。SACC是中国国家应对气候变化战略研究和国际合作中心(NCSC)开发的一个模拟模型。NCSC的研究人员${}^{15}$在本研究中与北京大学的研究人员密切合作,以确定能源使用和${\mathrm{{CO}}}_{2}$排放的长期趋势。钢铁行业中与CCUS相关的SACC关键参数如图3、图4和图5所示。
The mechanics of SACC-CCUS simulation model works as follows: (1) the model first calculates end energy consumption ${}^{16}$ based on macroeconomic data on GDP, population, industrial structure, and urbanization; (2) the model projects forward with different scenarios of energy mix, given priorities to non-fossil fuels over fossil fuels; (3) the model makes policy recommendations on different paths to achieving carbon neutrality in ${2060.}^{17}$ For projections, the base year is set at 2015.
SACC-CCUS模拟模型的运行机制如下:(1)该模型首先根据国内生产总值、人口、产业结构和城市化等宏观经济数据计算终端能源消耗${}^{16}$;(2)该模型在不同能源结构情景下进行预测,优先考虑非化石燃料而非化石燃料;(3)该模型针对${2060.}^{17}$中实现碳中和的不同路径提出政策建议。对于预测,基年设定为2015年。
15 NCSC project team was previouoly led by Liu Qiang and is now led by Cai Qimin.
15 NCSC项目团队之前由刘强领导,现在由蔡奇敏领导。
${}^{16}$ For consistency between model data and China’s energy balance sheets, this study incorporates the end energy consumption in agriculture and construction sectors into that in industrial sectors.
${}^{16}$ 为使模型数据与中国能源平衡表保持一致,本研究将农业和建筑部门的终端能源消耗纳入工业部门的终端能源消耗。
17 Data for the model comes mainly from China Electricity Council, China Energy Statistical Yearbooks, and China Statistical Yearbooks.
17 该模型的数据主要来自中国电力企业联合会、《中国能源统计年鉴》和《中国统计年鉴》。
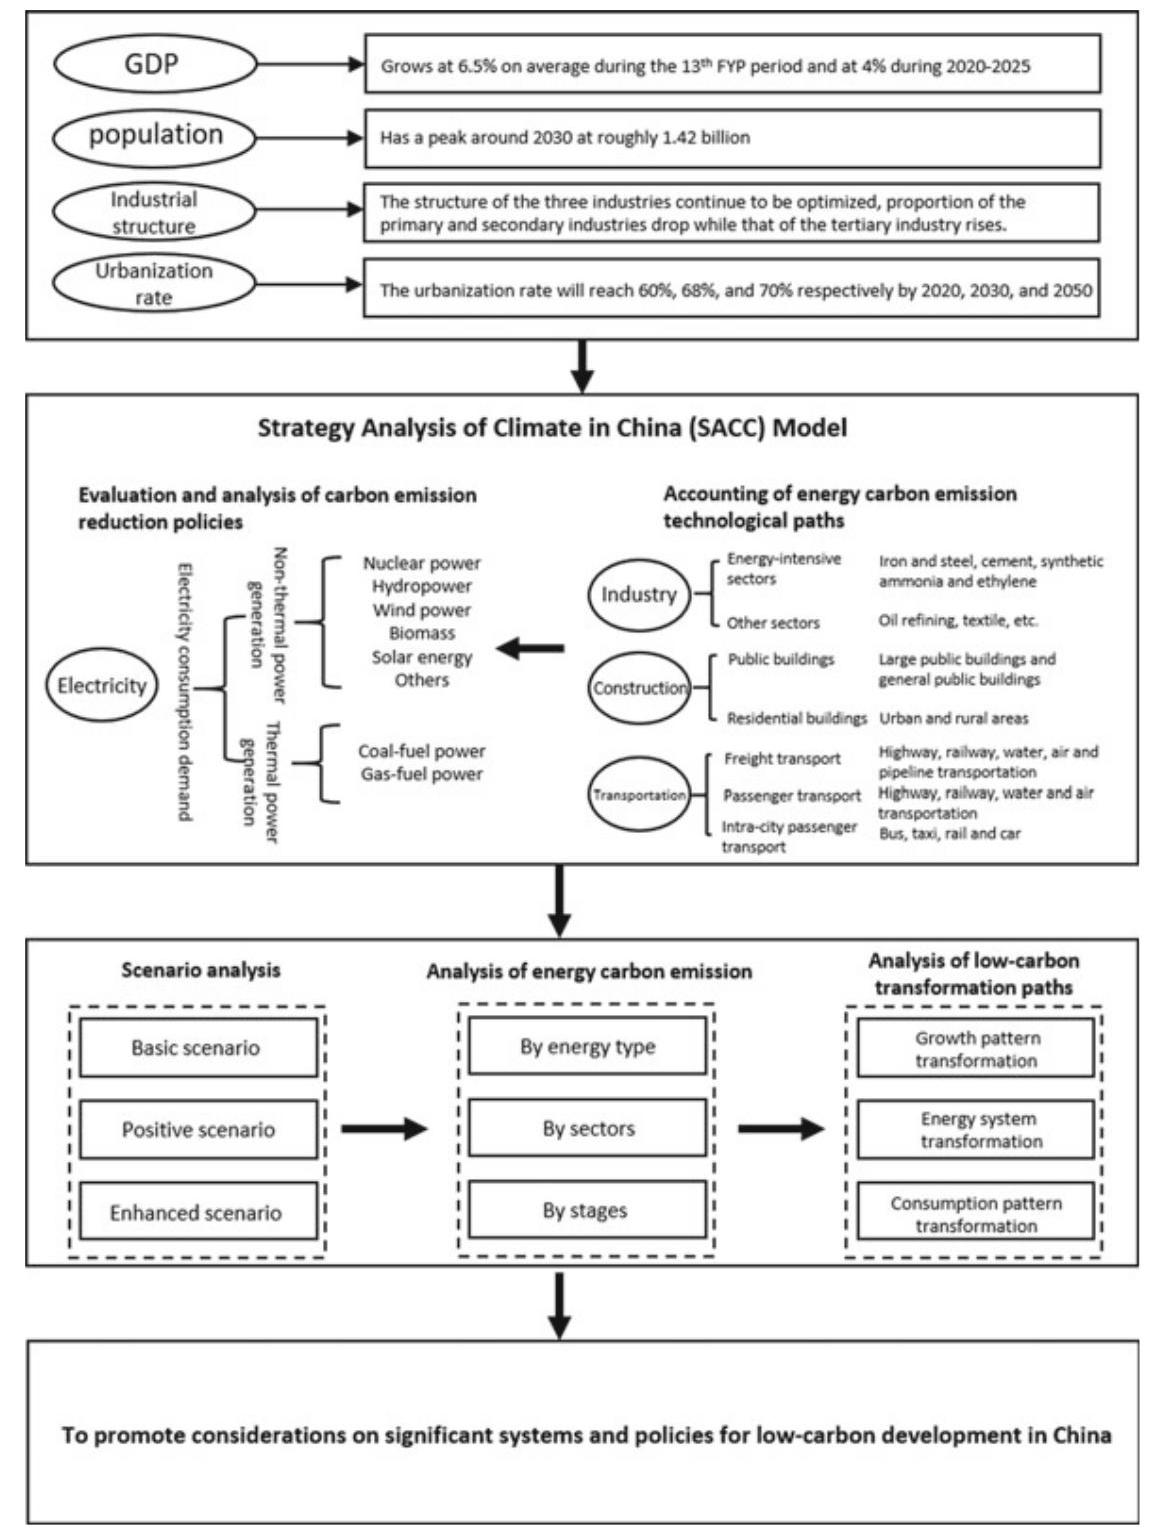
Fig. 4 Framework of the SACC model
图4 SACC模型框架
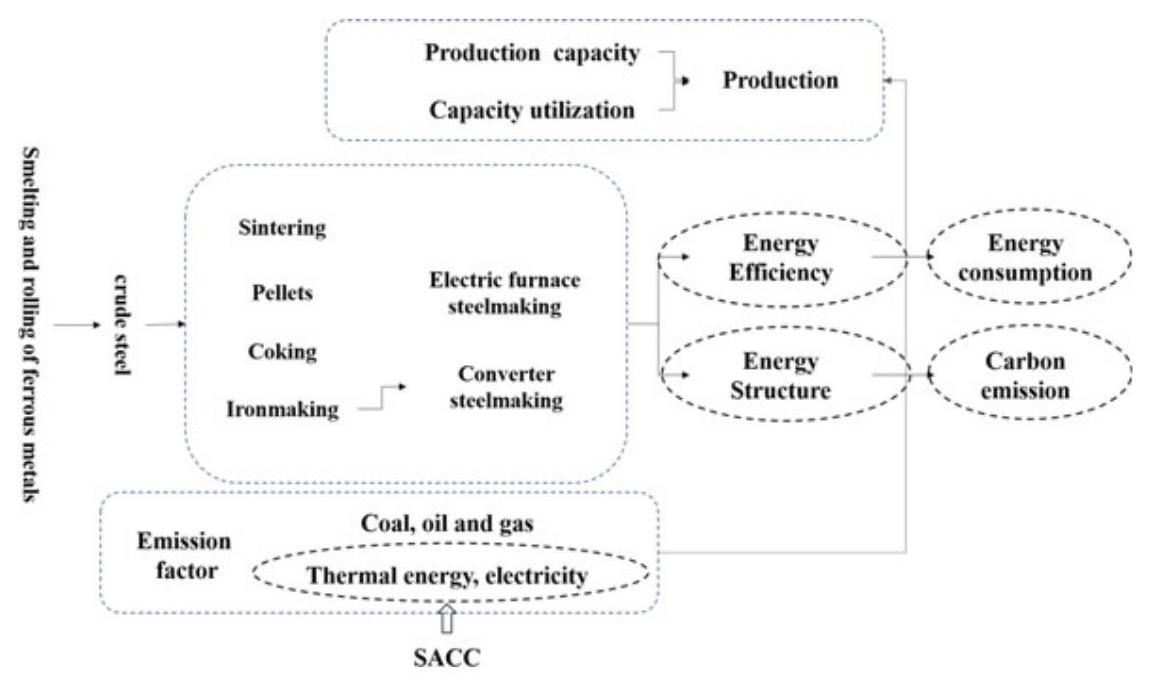
Fig. $5{\mathrm{{CO}}}_{2}$ Emission Reduction Model for the Steel Sector. Source NCSC
图$5{\mathrm{{CO}}}_{2}$ 钢铁行业减排模型。来源:NCSC
Specific to the steel sector, the SACC-CCUS model takes into account sector-specific variables, which presumably will affect ${\mathrm{{CO}}}_{2}$ emission rates in the steelmaking processes. Key parameters affected by CCUS application to steelmaking processes are circled in red in Figure 10. Here, some of CCUS-specific parameters in the model are calculated as follows:
具体到钢铁行业,SACC-CCUS模型考虑了特定行业变量,这些变量可能会影响炼钢过程中的${\mathrm{{CO}}}_{2}$排放率。CCUS应用于炼钢过程所影响的关键参数在图10中用红色圈出。在此,模型中一些特定于CCUS的参数计算如下:
Energy consumption of converter steel making $= \sum$ (energy efficiency of large and medium - sized processes ${}_{i} \; \times$ the proportion of such processes ${}_{i}$ efficiency of small processes ${}_{i} \; \times$ the proportion of such processes ${}_{i}$
转炉炼钢能耗$= \sum$(大中型工艺的能源效率${}_{i} \; \times$此类工艺的比例${}_{i}$小型工艺的效率${}_{i} \; \times$此类工艺的比例${}_{i}$
where $i$ represents different processes, namely sintering, pelletizing, coking, ironmaking and converter steelmaking.
其中$i$代表不同工艺,即烧结、球团、焦化、炼铁和转炉炼钢。
Energy consumption of EAF steelmaking $=$ Energy efficiency of large and medium
电弧炉炼钢能耗$=$大中型电弧炉炼钢工艺的能源效率
sized EAF steelmaking processes
× the proportion of such processes
×此类工艺的比例
- energy efficiency of small EAF steelmaking processes
+小型电弧炉炼钢工艺的能源效率
× the proportion of such processes,
×此类工艺的比例,
Carbon emissions $= \sum$ (energy consumption of converter steelmaking ${}_{j} \times {\text{ emission factor }}_{j}$
碳排放$= \sum$(转炉炼钢能耗${}_{j} \times {\text{ emission factor }}_{j}$)
$$
- \text{ energy consumption of EAF steelmaking }{}{j} \times {\text{ emission factor }}{j}\text{ ) } $$
where $j$ represents different energy types, namely coal, oil, gas, heat and electricity. Emission factors of coal, oil and gas are calculated and estimated based on the The People’s Republic of China National Greenhouse Gas Inventory while those of heat and electricity are input from the SACC model.
其中$j$代表不同能源类型,即煤炭、石油、天然气、热力和电力。煤炭、石油和天然气的排放因子根据《中华人民共和国国家温室气体清单》计算和估算,而热力和电力的排放因子则从SACC模型输入。
3.2 Simulation: 3 Scenarios
3.2 模拟:三种情景
Based on the SACC-CCUS model of simulation, we set three scenarios of decarbonization for the steel sector, namely a baseline scenario, a low-carbon scenario, and a near net-zero carbon scenario. The basic features of the three scenarios are as follows:
基于SACC-CCUS模拟模型,我们设定了钢铁行业脱碳的三种情景,即基准情景、低碳情景和近净零碳情景。三种情景的基本特征如下:
Base-Line Scenario
基线情景
In the baseline scenario, it is assumed that all energy saving and low-carbon policies introduced thus far will be followed. Specific to the steel sector, all targets set by the 13th FYP will be achieved and low-carbon policies already in place will continue beyond the 13th FYP. But no major technological breakthroughs will be made by 2050, and key low-carbon technologies, including CCUS, are not applied on a large scale.
在基线情景中,假定迄今出台的所有节能和低碳政策都将得到执行。具体到钢铁行业,“十三五”规划设定的所有目标都将实现,并且现行的低碳政策在“十三五”规划之后仍将继续实施。但到2050年不会有重大技术突破,包括CCUS在内的关键低碳技术也不会大规模应用。
Low Carbon Scenario
低碳情景
In the low carbon scenario, it is assumed that beyond the 13th FYP, more robust policies will be pursued to reduce carbon emissions than the baseline scenario. Specific to the steel sector, energy conservation and energy efficiency will be further improved. Crucially, the steel sector will go from indirect abatement of ${\mathrm{{CO}}}_{2}$ emission to direct abatement, which means that CCUS will be deployed in the steel sector, as the technology matures over time.
在低碳情景中,假设在“十三五”规划之后,将推行比基准情景更为有力的政策以减少碳排放。具体到钢铁行业,节能和能源效率将得到进一步提高。关键的是,钢铁行业将从间接减排${\mathrm{{CO}}}_{2}$排放转向直接减排,这意味着随着技术的逐渐成熟,碳捕获、利用与封存(CCUS)技术将在钢铁行业得到应用。
Near Zero Carbon Scenario
近零碳情景
In the near zero carbon scenario, it is assumed that all else being equal with the low-carbon scenario, electrification in each of energy end-user sectors will be intensified, and the energy structure will be further optimized. Compared to the baseline scenario, in the steel sector, better production processes such as EAF steelmaking, including an improved auxiliary system of scrap steel recycling, will replace the old long process of steelmaking aggressively, and deployment of CCUS will be taken into full consideration as well.
在近零碳情景中,假设在与低碳情景其他条件相同的情况下,各能源终端用户部门的电气化将得到加强,能源结构将进一步优化。与基准情景相比,在钢铁行业,电弧炉炼钢等更好的生产工艺,包括改进的废钢回收辅助系统,将积极取代旧的长流程炼钢工艺,同时也将充分考虑碳捕集、利用与封存(CCUS)的部署。
3.3 Simulation Results
3.3 模拟结果
Baseline Scenario
基准情景
China’s carbon intensity per unit of GDP in 2020 and 2030 will decline by roughly 49% and 67% respectively over the 2005 level, in both cases exceeding the targets set by the government. Industrial carbon emissions will peak around 2025 at approximately 6.3 billion tons of ${\mathrm{{CO}}}_{2}$ , which will further decrease to 2.1 billion and 2 billion tons of ${\mathrm{{CO}}}_{2}$ in 2035 and 2050 respectively. In the steel sector, carbon emissions will decrease from 1.33 billion tons in 2015 to 1.2 billion, 0.78 billion and 0.46 billion tons of ${\mathrm{{CO}}}_{2}$ in 2025,2035 and 2050 respectively. By 2050, carbon emissions will be about a third of the 2015 level. Crude steel production will be at a high plateau in 2015-2025 period, and then drop gradually to 0.5 billion tons in 2050.
2020年和2030年中国单位GDP碳强度将分别比2005年水平下降约49%和67%,均超过政府设定的目标。工业碳排放将在2025年左右达到峰值,约为63亿吨${\mathrm{{CO}}}_{2}$,到2035年和2050年将分别进一步降至21亿吨和20亿吨${\mathrm{{CO}}}_{2}$。在钢铁行业,碳排放将从2015年的13.3亿吨降至2025年、2035年和2050年的12亿吨、7.8亿吨和4.6亿吨${\mathrm{{CO}}}_{2}$。到2050年,碳排放将约为2015年水平的三分之一。粗钢产量将在2015 - 2025年期间处于高位平稳状态,然后在2050年逐渐降至5亿吨。
Low Carbon Scenario
低碳情景
China’s carbon intensity per unit of GDP in 2020 and 2030 will decline by about 51% and 71% respectively over the 2005 level, in both cases substantially exceeding the targets set by the government. Industrial carbon emissions will peak around 2025 at approximately 6.5 billion tons of ${\mathrm{{CO}}}_{2}$ , and will further decrease to 2 billion and 1.7 billion tons of ${\mathrm{{CO}}}_{2}$ in 2035 and 2050 respectively. In the steel sector, carbon emissions will decrease from 1.33 billion tons in 2015 to 1.1 billion, 0.72 billion and 0.08 billion tons of ${\mathrm{{CO}}}_{2}$ in 2025,2035 and 2050 respectively. Approximately 0.1 billion and 0.2 billion tons of carbon emissions will be captured by CCUS in 2035 and 2050 respectively. In this scenario, under more stringent policies to control production capacity, crude steel production will gradually decline to the 2010 level by 2030 and drop to 0.45 billion tons in 2050.
2020年和2030年中国单位GDP碳强度相对于2005年水平将分别下降约51%和71%,均大幅超过政府设定的目标。工业碳排放将在2025年左右达到峰值,约为65亿吨${\mathrm{{CO}}}_{2}$,并在2035年和2050年分别进一步降至20亿吨和17亿吨${\mathrm{{CO}}}_{2}$。在钢铁行业,碳排放将从2015年的13.3亿吨分别降至2025年的11亿吨、2035年的7.2亿吨和2050年的0.8亿吨${\mathrm{{CO}}}_{2}$。2035年和2050年分别约有1亿吨和2亿吨碳排放将通过碳捕集、利用与封存(CCUS)技术捕获。在这种情景下,在更严格的产能控制政策下,粗钢产量到2030年将逐渐降至2010年水平,并在2050年降至4.5亿吨。
Near Zero Carbon Scenario
近零碳情景
China’s carbon intensity per unit of GDP in 2020 and 2030 will decline by roughly 53% and 76% respectively over the level of 2005, in both cases substantially exceeding the targets set by the government. Industrial carbon emissions will peak around 2025 at approximately 6.3 billion tons of ${\mathrm{{CO}}}_{2}$ , which will further decrease to 1.7 billion and 1.3 billion tons of ${\mathrm{{CO}}}_{2}$ in 2035 and 2050 respectively. In the steel sector, carbon emissions will decrease from 1.33 billion tons in 2015 to 1 billion, 0.57 billion and 0.03 billion tons of ${\mathrm{{CO}}}_{2}$ respectively in 2025,2035 and 2050. Approximately 0.05-0.1 billion and 0.1-0.2 billion tons of carbon emissions will be captured by CCUS in 2035 and 2050 respectively. In this scenario, carbon emissions cut by CCUS, however, may be less than in the second scenario. The reason is that replacement of old steelmaking processes by EAF steelmaking methods will reduce the application of CCUS in the steel sector, although not necessarily for the whole country.
2020年和2030年中国单位GDP碳强度相对于2005年水平将分别下降约53%和76%,均大幅超过政府设定的目标。工业碳排放将在2025年左右达到峰值,约为63亿吨${\mathrm{{CO}}}_{2}$,到2035年和2050年将分别进一步降至17亿吨和13亿吨${\mathrm{{CO}}}_{2}$。在钢铁行业,碳排放将从2015年的13.3亿吨分别降至2025年、2035年和2050年的10亿吨、5.7亿吨和0.3亿吨${\mathrm{{CO}}}_{2}$。到2035年和2050年,CCUS分别捕获约0.05 - 0.1亿吨和0.1 - 0.2亿吨碳排放。然而,在这种情景下,CCUS减少的碳排放可能低于第二种情景。原因是电弧炉炼钢法取代旧的炼钢工艺将减少CCUS在钢铁行业的应用,尽管不一定适用于整个国家。
3.4 CO2 Reduction Potential of CCUS in China
3.4 中国碳捕集、利用与封存(CCUS)的二氧化碳减排潜力
Figure 11 exhibits forecasts by different studies on emission reduction potential of CCUS for China as a whole. The range of emission reductions in the near (2020), medium (2035) and long (2050) term is listed below (Table 11). These studies show that through CCUS, China can reduce 10-200 million tons of ${\mathrm{{CO}}}_{2}$ emissions in 2020 and 100-2240 million tons of ${\mathrm{{CO}}}_{2}$ emissions in 2035. To achieve a higher range of emission reductions, i.e., 1000-3840 million tons of ${\mathrm{{CO}}}_{2}$ emissions in 2050, CCUS will have to be extensively deployed beyond 2035. By 2050, CCUS can be put into commercial use on a large scale, and achieving near-zero carbon emissions means large demand for CCUS technologies (Table 1).
图11展示了不同研究对中国整体CCUS减排潜力的预测。近(2020年)、中(2035年)、长期(2050年)的减排范围如下(表11)。这些研究表明,通过CCUS,中国在2020年可减少1000 - 2亿吨${\mathrm{{CO}}}_{2}$排放,在2035年可减少1 - 22.4亿吨${\mathrm{{CO}}}_{2}$排放。为实现更高的减排范围,即2050年减排10 - 38.4亿吨${\mathrm{{CO}}}_{2}$排放,CCUS必须在2035年后广泛部署。到2050年,CCUS可大规模商业化应用,实现近零碳排放意味着对CCUS技术的巨大需求(表1)。
Table 1 Forecasts of ${\mathrm{{CO}}}_{2}$ reduced by CCUS in China (mtCO2)
表1 中国CCUS减少的${\mathrm{{CO}}}_{2}$预测(百万吨二氧化碳)
| Year | 2020 | 2035 | 2050 |
| Range of emission reductions | 10-200 | 100-2240 | 1000-3840 |
Sources ADB, Study of China’s Carbon Capture and Storage Demonstration and Promotion Roadmap, 2015; IEA, WEO 2015 Special Report on Energy and Climate Change, 2015; Nie Ligong et al., A Study of the Path to Global Commercialization of CCS Technology, 2016; OECD/IEA, Energy Technology Analysis—Prospects for CO2 Capture and Storage, 2004
来源:亚洲开发银行,《中国碳捕集与封存示范及推广路线图研究》,2015年;国际能源署,《2015年能源与气候变化特别报告》,2015年;聂立功等,《CCS技术全球商业化路径研究》,2016年;经合组织/国际能源署,《能源技术分析——二氧化碳捕集与封存前景》,2004年
Table $2{\mathrm{{CO}}}_{2}$ Reduction potential of CCUS in the steel sector
表$2{\mathrm{{CO}}}_{2}$ 钢铁行业CCUS的减排潜力
| 2030 | 2035 | 2040 | 2045 | 2050 | |
| Emission reduction potential $\left( {\mathrm{{mtCO}}}_{2}\right)$ | 10 | 15 | 50 | 75-100 | 100-200 |
Source NCSC
来源:国家碳捕集与封存中心(NCSC)
3.5 CO2 Reduction Potential of CCUS in the Steel Sector
3.5 钢铁行业碳捕集、利用与封存(CCUS)的二氧化碳减排潜力
In light of the above, and based on our stimulations of low carbon and near-zero carbon shown in Table 11. In the near term, the steel sector will see little emission reduction effects of CCUS. However, the emission reduction potential of CCUS in the steel sector can reach ${10}{\mathrm{{mtCO}}}_{2}$ by 2030 and ${15}{\mathrm{{mtCO}}}_{2}$ in 2035, accounting for ${0.6} - {15}\%$ of the national total, and register ${50}{\mathrm{{mtCO}}}_{2}$ in 2040. Up to this period of time, however, CCUS technologies will not have scale effect in the steel sector. However, by 2045, as industrial cluster and infrastructure of transport and storage significantly improve, the emission reduction potential of CCUS in the sector can also increase, reaching ${75} - {100}{\mathrm{{mtCO}}}_{2}$ in 2045, and climbing further to 100-200 ${\mathrm{{mtCO}}}_{2}$ in 2050, accounting for ${5.2}\% - {10}\%$ of the national total (Table 2).
鉴于上述情况,并基于我们在表11中所示的低碳和近零碳模拟。短期内,钢铁行业的碳捕集、利用与封存(CCUS)减排效果甚微。然而,钢铁行业的碳捕集、利用与封存(CCUS)减排潜力到2030年可达${10}{\mathrm{{mtCO}}}_{2}$,2035年可达${15}{\mathrm{{mtCO}}}_{2}$,占全国总量的${0.6} - {15}\%$,2040年可达${50}{\mathrm{{mtCO}}}_{2}$。不过,在此期间,碳捕集、利用与封存(CCUS)技术在钢铁行业不会产生规模效应。然而,到2045年,随着产业集群以及运输和储存基础设施的显著改善,该行业的碳捕集、利用与封存(CCUS)减排潜力也会增加,2045年达到${75} - {100}{\mathrm{{mtCO}}}_{2}$,到2050年进一步攀升至100 - 200${\mathrm{{mtCO}}}_{2}$,占全国总量的${5.2}\% - {10}\%$(表2)。
4 Strategic Roadmap for CCUS in the Steel Sector
4 钢铁行业碳捕集、利用与封存战略路线图
According to the IEA, to achieve the global energy and climate goals in light of the Paris agreement, direct carbon emissions from the steel sector will have to decrease by more than ${50}\%$ by 2050 from the 2019 levels, and ${\mathrm{{CO}}}_{2}$ emissions will have to go down to 0.6 tons of ${\mathrm{{CO}}}_{2}$ per ton of crude steel produced, and then move further down towards zero emissions. To make that happen, CCUS has increasingly been recognized as a technology of direct ${\mathrm{{CO}}}_{2}$ emission reduction on industrial scale, and yet, worldwide, the technology, by and large, is still at the early stage of pilots and demonstrations.
根据国际能源署的说法,为了根据《巴黎协定》实现全球能源和气候目标,到2050年,钢铁行业的直接碳排放必须比2019年的水平减少超过${50}\%$,并且${\mathrm{{CO}}}_{2}$排放量必须降至每吨粗钢生产0.6吨${\mathrm{{CO}}}_{2}$,然后进一步降至零排放。为了实现这一目标,碳捕集、利用与封存越来越被认为是一种在工业规模上直接减少${\mathrm{{CO}}}_{2}$排放的技术,然而,在全球范围内,这项技术总体上仍处于试点和示范的早期阶段。
In China, the situation is similar. So far there are about 30 CCUS projects under operation or under construction-mostly in energy or coal-fired power plants but none has existed in the steel sector. In September 2020, China pledged to the world to peak ${\mathrm{{CO}}}_{2}$ emissions prior to 2030 and to achieve carbon neutrality in 2060. In view of the new pledge and the significant role of the steel sector in China’s low carbon strategy, it becomes increasingly relevant to consider, and indeed promote, CCUS in the steel sector as well. Although very costly now, CCUS is expected to be commercially viable on a large scale by the middle of this century, and when combined with technologies of biomass and EOR (enhanced oil recovery), the technology even has the potential to achieve negative ${\mathrm{{CO}}}_{2}$ emissions. Given the simulation results in the previous section, we develop and indeed recommend a strategic roadmap for CCUS development in China’s steel sector. The roadmap has three phases, namely the 14th FYP (2021-2025), 2025- 2035, and 2035-2060 (see Fig. 6). We highlight the key points of each of the three phases below:
在中国,情况类似。到目前为止,大约有30个碳捕集、利用与封存项目正在运行或建设中,大部分在能源或燃煤发电厂,但钢铁行业还没有。2020年9月,中国向世界承诺在2030年前实现${\mathrm{{CO}}}_{2}$排放达峰,并在2060年实现碳中和。鉴于这一新承诺以及钢铁行业在中国低碳战略中的重要作用,在钢铁行业考虑并切实推广碳捕集、利用与封存变得越来越重要。尽管目前成本非常高,但预计到本世纪中叶,碳捕集、利用与封存将在大规模上具有商业可行性,并且当与生物质和提高采收率(EOR)技术相结合时,该技术甚至有可能实现负${\mathrm{{CO}}}_{2}$排放。鉴于上一节的模拟结果,我们制定并确实推荐了中国钢铁行业碳捕集、利用与封存发展的战略路线图。该路线图有三个阶段,即“十四五”规划(2021 - 2025年)、2025 - 2035年和2035 - 2060年(见图6)。我们在下面突出了三个阶段各自的关键点:
Phase I (2021-2025)
第一阶段(2021 - 2025年)
Phase I overlaps with China’s 14th FYP, and it is a preparatory phase on our strategic roadmap. In this preparatory phase, China should get CCUS started in the iron/steel sector on the basis of on-going CCUS projects in other sectors. First of all, by way of by top-level design, China should work out an overall action plan to make sure the iron/steel sector, among many other industrial sectors, peak ${\mathrm{{CO}}}_{2}$ emissions by 2030. ${}^{18}$ And in line with that action plan, China should increase policy support for large-scale CCUS pilot and demonstration projects. Authorities, both at national and local levels, should explore and develop ways to support CCUS projects.
第一阶段与中国的第十四个五年规划重叠,是我们战略路线图中的一个准备阶段。在这个准备阶段,中国应在其他行业现有碳捕集、利用与封存(CCUS)项目的基础上,在钢铁行业启动CCUS。首先,通过顶层设计,中国应制定一个总体行动计划,确保钢铁行业与许多其他工业部门一道,在2030年前实现${\mathrm{{CO}}}_{2}$排放峰值。${}^{18}$ 并且根据该行动计划,中国应加大对大规模CCUS试点和示范项目的政策支持。国家和地方各级政府应探索并制定支持CCUS项目的方式。
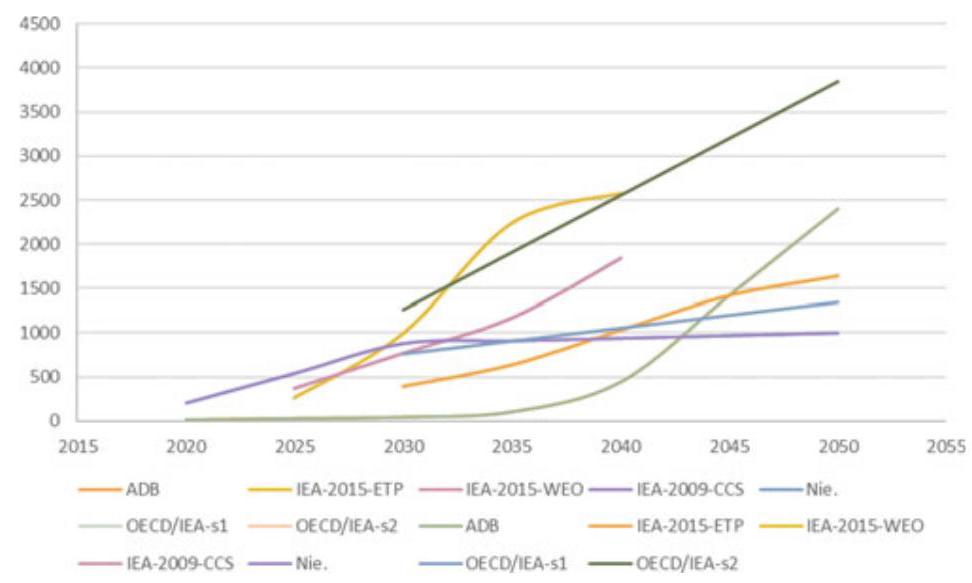
Fig. 6 Forecasts of ${\mathrm{{CO}}}_{2}$ Reduced by CCUS in China (mtCO ${}_{2}$ ). Sources ADB, Study of China’s Carbon Capture and Storage Demonstration and Promotion Roadmap, 2015; IEA, WEO 2015 Special Report on Energy and Climate Change, 2015; Nie Ligong et al., A Study of the Path to Global Commercialization of CCS Technology, 2016; OECD/IEA, Energy Technology Analysis-Prospects for ${\mathrm{{CO}}}_{2}$ Capture and Storage,2004
图6 中国CCUS减排${\mathrm{{CO}}}_{2}$预测(百万吨二氧化碳${}_{2}$)。来源:亚洲开发银行《中国碳捕集与封存示范及推广路线图研究》,2015年;国际能源署《2015年能源与气候变化特别报告》,2015年;聂立功等《碳捕集与封存技术全球商业化路径研究》,2016年;经合组织/国际能源署《能源技术分析——碳捕集与封存前景》,2004年
For example, ${\mathrm{{CO}}}_{2}$ emissions captured and stored by enterprises retrofitted with CCUS should be provided with tax credits and subsidies, including CCER (Chinese Certified Emission Reduction) and be traded in the national ETS. Specific to the steel sector, a few firms should be chosen for CCUS pilot and demonstration projects during the 14th FYP period. In the meantime, public funding to the CCUS-retrofitted firms should go beyond mere R&D money.
例如,对采用CCUS进行改造的企业所捕获和封存的${\mathrm{{CO}}}_{2}$排放,应给予税收抵免和补贴,包括中国核证自愿减排量(CCER),并在国家碳排放交易体系中进行交易。具体到钢铁行业,在第十四个五年规划期间应选择几家公司开展CCUS试点和示范项目。与此同时,对采用CCUS进行改造的企业的公共资金投入不应仅仅局限于研发资金。
Phase II (2025-2035)
第二阶段(2025 - 2035年)
Phase II, from 2025 to 2035, will be to consolidate the groundwork for imporved operations of CCUS. The focus during this period should be on three areas: (a) better technologies; (b) enhanced clusters and infrastructure for large-scale full-chain CCUS operations; and (c) improved financing schemes. In terms of technology, China should increase investment in R&D of CCUS, and give stronger support to the integration of CCUS with technologies such as ULCOS and TGR-BF. In terms of infrastructure construction, China should beef up effort to develop CCUS-related industrial clusters, including infrastructure of transport and storage with optimal ${\mathrm{{CO}}}_{2}$ sink-source matching. Specific to the steel sector, during this period, the steel sector should be included in the national ETS so as to open up more channels for financing of, or give more incentives to, the deployment of CCUS for the steel sector. As in Phase I, international cooperation should be encouraged to develop CCUS in China’s industrial sectors, including the steel sector, in Phase II and beyond.
2025年至2035年的第二阶段将巩固碳捕集、利用与封存(CCUS)改进运营的基础。这一时期的重点应放在三个方面:(a)更好的技术;(b)加强大规模全链CCUS运营的集群和基础设施;(c)改进融资方案。在技术方面,中国应增加对CCUS研发的投资,并更有力地支持CCUS与超低二氧化碳排放炼钢(ULCOS)和氢气竖炉-高炉(TGR-BF)等技术的整合。在基础设施建设方面,中国应加大力度发展与CCUS相关的产业集群,包括具备最佳${\mathrm{{CO}}}_{2}$汇-源匹配的运输和储存基础设施。具体到钢铁行业,在此期间,钢铁行业应纳入国家碳排放交易体系(ETS),以便为钢铁行业CCUS的部署开辟更多融资渠道或提供更多激励措施。与第一阶段一样,应鼓励国际合作,在第二阶段及以后在中国包括钢铁行业在内的工业部门发展CCUS。
Phase III (2035-2060)
第三阶段(2035 - 2060年)
Phase III, 2035-2060, is a phase of great expansion of CCUS in China’s iorn/steel sector, now that the technogoly is relatively mature, and many CCUS-related clusters and infrastructure are ready for operations. During this phase, a sector-wide technological path for near-zero emissions should be established involving both low-carbon steelmaking technologies and CCUS as technologies of direct reductions of ${\mathrm{{CO}}}_{2}$ emissions. That aside, a new focus of the phase is to enhance international cooperations. This would invovling maintaining international standards, building level-playing field, and exploring ways to include carbon emissions reduced through CCUS in the steel sector in international ETSs, such that CCUS has a better chance to be widely applied in the pursuit of near-zero carbon emissions in the steel sector (Fig. 7).
2035 - 2060年的第三阶段是中国钢铁行业碳捕集、利用与封存(CCUS)大幅扩张的阶段,因为该技术相对成熟,且许多与CCUS相关的集群和基础设施已准备好投入运营。在此阶段,应建立全行业近零排放的技术路径,包括低碳炼钢技术和作为直接减少${\mathrm{{CO}}}_{2}$排放技术的CCUS。除此之外,该阶段的一个新重点是加强国际合作。这将涉及维持国际标准、营造公平竞争环境,并探索将钢铁行业通过CCUS减少的碳排放纳入国际排放交易体系(ETS)的方法,以便CCUS在追求钢铁行业近零碳排放方面有更好的机会得到广泛应用(图7)。
${}^{18}$ A more optimistic prospect is that as an action plan in the making for the 14th FYP, the iron/steel sector has been planning to peak ${\mathrm{{CO}}}_{2}$ emissions by 2025 and reduce ${\mathrm{{CO}}}_{2}$ emissions by ${30}\%$ from the peak level by 2030.
${}^{18}$ 一个更乐观的前景是,作为正在制定的“十四五”规划的一项行动计划,钢铁行业计划到2025年实现${\mathrm{{CO}}}_{2}$排放达峰,并到2030年将${\mathrm{{CO}}}_{2}$排放从峰值水平降低${30}\%$。
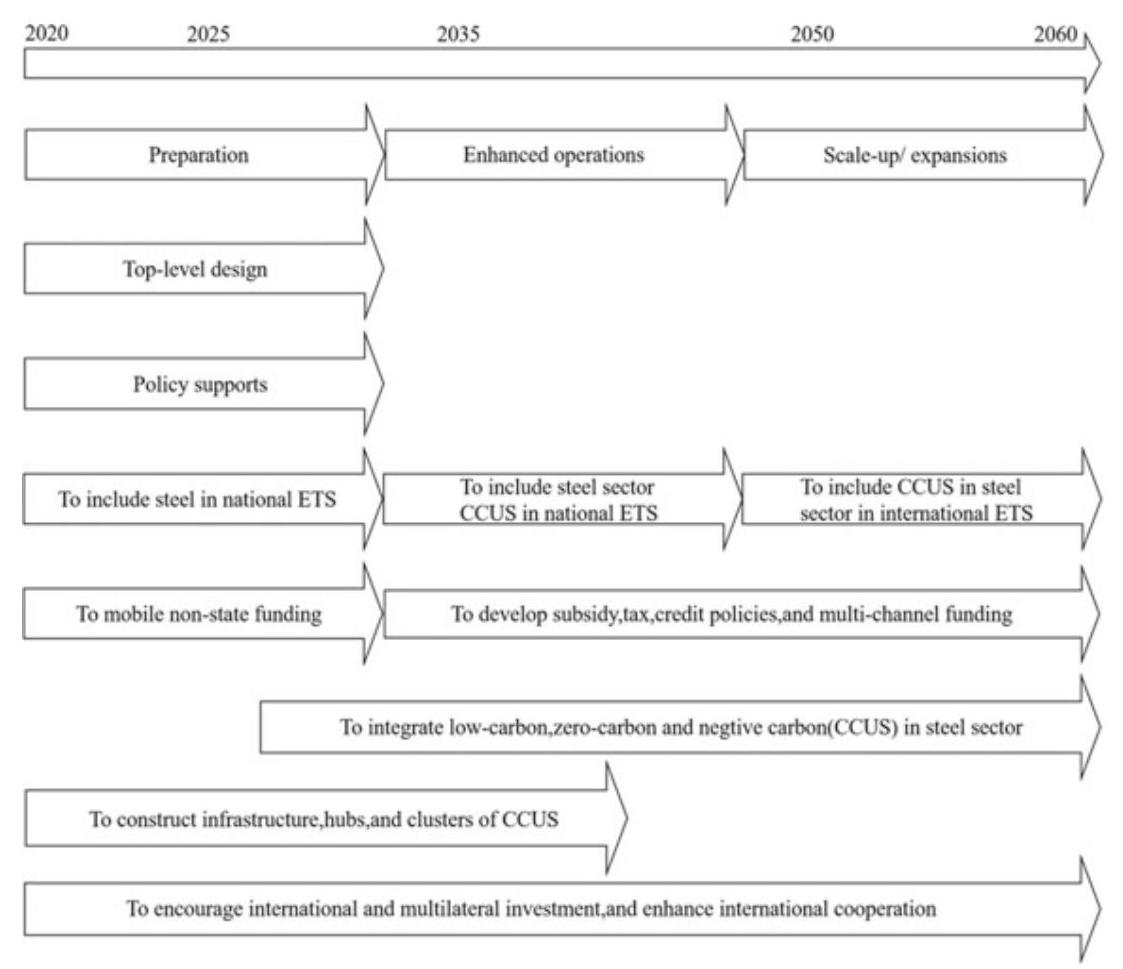
Fig. 7 A phased CCUS Policy Roadmap for Steel Sector
图7 钢铁行业分阶段CCUS政策路线图
Acronym Full spelling
首字母缩写 全称
BATs Best available technologies
最佳可用技术 BATs
BFs Blast Furnaces Steelmaking
高炉炼钢 BFs
CAMU China Association of Metalscrap Utilization
中国金属再生资源协会 CAMU
CCER China certified emission reduction
中国核证自愿减排量 CCER
CCUS Barbon capture, utilization and storage
碳捕集、利用与封存 CCUS
EAF Electric are Furnace
电弧炉 EAF
EIA Environmental Impact Assessment
环境影响评估 EIA
ETS Emission-trading system
排放交易体系 ETS
FYP Five Year Plan
五年计划 FYP
MEP Ministry of Environment Protection
环境保护部 MEP
MOF Ministry of Finance
财政部 MOF
MOST Ministry of Science and Technology
科学技术部
NCSC National Center for Climate Strategy and International Cooperation
国家应对气候变化战略研究和国际合作中心
NDRC National Development and Reform Commission
国家发展和改革委员会
TGR-BF Top gas recycling blast furnace
顶煤气循环高炉
ULCOS Ultra low ${\mathrm{{CO}}}_{2}$ steelmaking
超低${\mathrm{{CO}}}_{2}$炼钢
WTO World Trade Organization
世界贸易组织
References
参考文献
Asian Development of Bank. (2015) National Development and Reform Commission of China. Roadmap Research on Demonstration and Promotion of China’s Carbon Capture and Storage.
Cai, B., Pang, L., Cao, L., Li, Q., Liu, G., Zhong, P., Zhang, X., Yang, Y., Chen, F., Li, Q., Yang, X., Sun, Y., Li, Y., & Zhang, H. (2019). Two-year implementation assessment (2016-2018) of China’s technical guideline on environmental risk assessment for carbon dioxide capture, utilization and storage (on trial). Environmental Engineering, 37(02), 1-7. Global CCS Institute. Global Status of CCS Report: 2019 [EB/OL]. https://www.globalccsinstitute.com/resources/publications-rep orts-research/global-status-of-ccs-report-2019/. Accessed December 09, 2019.
China Metallurgical Industry Planning and Research Institute. (2019) Low-carbon emissions from the iron & steel industry and prospects [restricted data].
China Metallurgical Industry Planning and Research Institute. (2019). Report on energy conservation and low-carbon development in China’s iron & steel industry.
Department of Energy Statistics, National Bureau of Statistics. (2019). China energy statistical yearbook 2018. China Statistics Press.
Department of Science and Technology for Social Development, Ministry of Science and Technology, Administrative Center for China’s Agenda 21. (2019). Roadmap for carbon capture, utilization and storage technology development in China. Beijing: Science Press.
He, X., Huang, Y., & Liao, C. (2014). Review and analysis of CCS policies in domestic overseas. Advances in New and Renewable Energy, 2(2), 157-163.
IEA. (2020). Energy technology perspective 2020 [EB/OL]. https://www.iea.org/reports/ene rgy-technology-perspectives-2020. Accessed September, 2020
IEA. (2020). World Energy Outlook 2020 [EB/OL]. https://www.iea.org/reports/world-ene rgy-outlook-2020. Accessed October, 2020
IEA. (2020). Iron and steel technology roadmap [EB/OL]. https://www.iea.org/reports/iron-and-steel-technology-roadmap.Accessed October, 2020
IPCC. Special report on global warming of 1.5 [EB/OL]. https://www.ipcc.ch/sr15/
Li, X., Zhang, J., Li, Q., Liu, G., Zhang, X., & Wei, F. (2018). Implementation status and gap analysis of china’s carbon dioxide capture, utilization and geological storage technology roadmap (2011). Science & Technology Review, 36(04), 85-95.
Li, X. (2019). Roadmap to high-quality development of iron and steel industry in new age. Iron and Steel, 54(01), 1-7.
Li, X., & Li, H. Deep decarburization path for high-quality iron and steel development. China Science Daily, 003. Accessed November 10, 2020.
Ministry of Science and Technology. (2013). Notice on issuing the national 12th five-year plan for the development of carbon capture, utilization and storage [EB/OL]. http://www.gov.cn/zwgk/2013-03/11/content_2351242.htm..Accessed February 16, 2020
Ministry of ecology and environment. notice on issuing the technical guideline on environmental risk assessment for carbon dioxide capture, utilization and storage (on trial) [EB/OL]. http://www.mee.gov.cn/gkml/hbb/bgt/201606/t20160624_356016.htm.Accessed June 21, 2016.
National Bureau of Statistics. (2019). China statistical yearbook 2018. China Statistics Press.
National Bureau of Statistics. (2020). Statistical communique of the People’s Republic of China on the 2019 National Economic and Social Development [EB/OL]. http://www.stats.gov.cn/tjsj/zxfb/202002/t20200228_1728913.html.Accessed March 2020.
National Development and Reform Commission. (2013). Notice on promoting experiment and demonstration of carbon capture, utilization and storage [EB/OL]. http://www.gov.cn/zwgk/2013-05/09/content_2398995.htm.Accessed April 27, 2013.
Peng, S. (2013). Implementation of domestic and international carbon capture, utilization and storage (CCUS) projects and development of relevant policies. Low Carbon World, 1, 18-21.
United Nations. (2018). World urbanization prospects (The 2018 revision, online edition). Department of Economic and Social Affairs, Population Division
World Resources Institute. (2017). Lessons from international practices for the development of CCSL legal & regulatory framework in China [EB/OL]. https://www.wri.org.cn/CCS_ legal_and_regulatory_framework_CN. Accessed March 2017.
World Steel Association. (2020). Steel statistical yearbook 2020 [EB/OL]. https://www.wor ldsteel.org/zh/
World Steel Association. (2020). Global crude steel output decreases by 0.9% in 2020 [EB/OL]. https://www.worldsteel.org/media-centre/press-releases/2021/Global-crude-steel-output-decreases-by-0.9--in-2020.html
Wang, X. (2018). Theory and practice on energy conservation and emission reduction in China’s iron & steel industry under low carbon economy. Wuhan University Press.
Wang, X. (2020). Convergence and prospects, china 2049: economic challenges of a rising global power . Brooking Institution Press.
Yang, H., & Guo, M. (2019). Opportunities and guidelines for steel enterprises to reduce greenhouse gas emissions. China: Economic Press.
Zhang, J., Zhang, L. (2020). Preliminary discussion on the development of carbon capture, utilization and storage for carbon neutralization [J/OL]. Thermal Power Generation, 1-6. Accessed December 05, 2020.
Part II Technology
第二部分 技术
Carbon Capture, Utilization & Storage: A General Overview
碳捕获、利用与封存:概述
Dongxiao Zhang, Ruqiang Zou, Xidong Wang, Jin Liu, and Fanyang Mo
董晓张、邹如强、王西东、刘进、莫凡洋
With rapid increase in anthropogenic ${\mathrm{{CO}}}_{2}$ emissions, greenhouse effect has been more and more severe and climate change becomes a threat that influences all live beings on earth. In order to mitigate ${\mathrm{{CO}}}_{2}$ emissions, Paris Agreement was signed in 2015 which requires all countries to contribute their efforts in order to limit the global average temperature increase below $2{}^{ \circ }\mathrm{C}$ by 2050. The Paris Agreement underlines the urgent need to end the increasing trend of ${\mathrm{{CO}}}_{2}$ emissions and suggests that all technologies, either traditional or novel, should be used in reducing the emissions.
随着人为${\mathrm{{CO}}}_{2}$排放的迅速增加,温室效应日益严重,气候变化成为影响地球上所有生物的威胁。为了减少${\mathrm{{CO}}}_{2}$排放,2015年签署了《巴黎协定》,要求所有国家共同努力,到2050年将全球平均气温升幅限制在$2{}^{ \circ }\mathrm{C}$以下。《巴黎协定》强调迫切需要遏制${\mathrm{{CO}}}_{2}$排放的增长趋势,并建议采用所有技术,包括传统技术和新技术,来减少排放。
Carbon capture, utilization and storage (CCS) comes as an effective method to solve the problem, especially in fossil fuel-intensive industries. For instance, CCS in steel industry has gain more attention due to the future rising costs of carbon emissions. CCS is projected to account for 33% emission mitigation in industry by 2050, of which more than 80% the carbon dioxide captured is projected to come from steel and cement industries (IEA, 2016).
碳捕获、利用与封存(CCS)是解决该问题的有效方法,特别是在化石燃料密集型行业。例如,由于未来碳排放成本上升,钢铁行业的CCS受到了更多关注。预计到2050年,CCS将占工业减排的33%,其中超过80%的捕获二氧化碳预计将来自钢铁和水泥行业(国际能源署,2016年)。
This chapter gives a general review of carbon capture, utilization and storage, as well as ${\mathrm{{CO}}}_{2}$ transportation. The chapter contains four sections: Section 1 generally introduces the layout of a typical iron/steel plant. Section 2 provides a review of the most appropriate carbon capture technologies in steelmaking. Section 3 covers emerging technologies of ${\mathrm{{CO}}}_{2}$ utilization, including ${\mathrm{{CO}}}_{2}$ -EOR (Enhanced Oil Recovery) and BECCS (Bio-Energy CCS). We look at appropriate options for COs transport and storage in Section 4.
本章对碳捕获、利用与封存以及${\mathrm{{CO}}}_{2}$运输进行了综述。本章包含四个部分:第1节总体介绍典型钢铁厂的布局。第2节回顾了炼钢中最合适的碳捕获技术。第3节涵盖了${\mathrm{{CO}}}_{2}$利用的新兴技术,包括${\mathrm{{CO}}}_{2}$ -提高采收率(EOR)和生物能源CCS(BECCS)。我们在第4节探讨了二氧化碳运输和封存的合适选择。
D. Zhang $\left( \square \right) \cdot$ R. Zou $\cdot$ X. Wang $\cdot$ J. Liu $\cdot$ F. Mo
董晓张$\left( \square \right) \cdot$邹如强$\cdot$王西东$\cdot$刘进$\cdot$莫凡洋
College of Engineering, Peking University, Beijing, China
中国北京大学工学院
Review of Typical Iron and Steel Plant Layout
典型钢铁厂布局综述
Steel production consists of both a long process and a short process. The long process consists of mineral processing, sintering, ironmaking, steelmaking, and the steel rolling process. The short process begins with steel. It refers to compact production process of the combination electric arc furnace, continuous casting and continuous rolling. The main performance is the compact process of raw materials preparation, electric arc furnace melting, refining, continuous casting and rolling Current steel technology gives priority to the long process. The primary technological process in producing steel is shown in Fig. 1. The following sections will describe the long process which includes raw material preparation, ironmaking, steelmaking and steel rolling.
钢铁生产包括长流程和短流程。长流程包括选矿、烧结、炼铁、炼钢和轧钢过程。短流程以钢为起点。它指的是电弧炉、连铸和连轧相结合的紧凑生产流程。主要特点是原料准备、电弧炉熔化、精炼、连铸和轧制的紧凑流程。当前的钢铁技术优先采用长流程。钢铁生产的主要工艺流程如图1所示。以下各节将描述包括原料准备、炼铁、炼钢和轧钢的长流程。
1.1 The Preparation of the Raw Material
1.1 原材料的制备
1.1.1 Mineral Processing
1.1.1 矿物加工
Mineral processing of low-grade raw ore occurs via the processes of magnetic separation, flotation and re-election, followed by high grade iron concentrate in preparation for the next step of smelting. Main production processes include: crushing iron ore, grinding, mineral processing, drying, and ore concentrate powder.
低品位原矿的矿物加工通过磁选、浮选和重选等工艺进行,随后得到高品位铁精矿,为下一步冶炼做准备。主要生产流程包括:铁矿石破碎、研磨、矿物加工、干燥以及矿精粉。
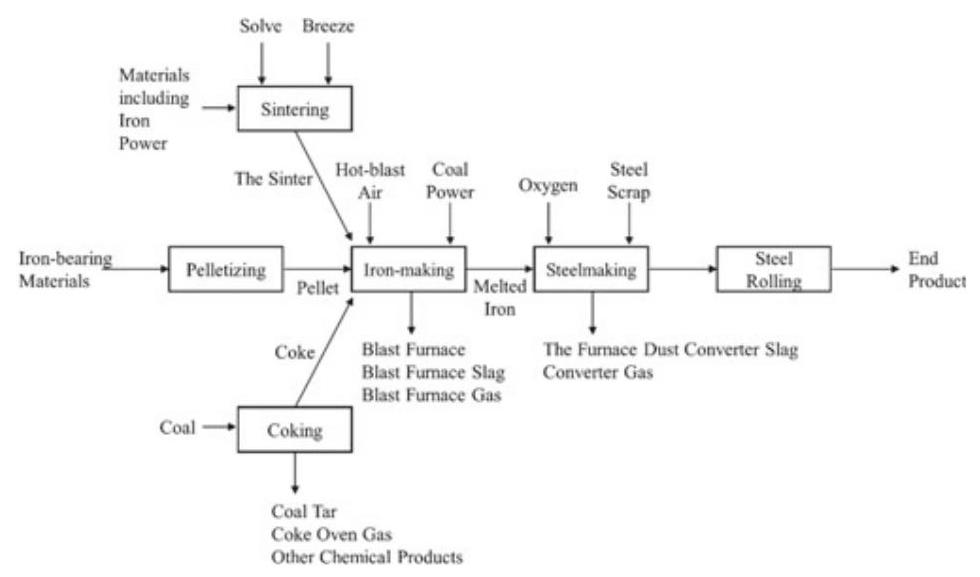
Fig. 1 Main technological processes in producing steel
图1 钢铁生产的主要工艺流程
1.1.2 Sintering and Pelletizing
1.1.2烧结和球团
Sintering production is the process of mixing iron powder, solvent and fuel in specific proportion and then tiling the mixture to a sintering car and ignition. This process causes solution water to evaporate and leads to a series of chemical reactions to occur, ultimately resulting in a partial liquid phase bonding with sufficient strength and granularity. Finally, after crushing, cooling and screening, we produce the finished sinter. Main production processes include burden, first-mixing, second-mixing, sintering, crushing, sieving, cooling and the finished sinter. The production of sintering generates flue gas with high sulfur content, which needs further desulfurization process.
烧结生产是将铁粉、溶剂和燃料按特定比例混合,然后将混合物平铺在烧结车上并点火的过程。这个过程会使溶液中的水分蒸发,并引发一系列化学反应,最终形成具有足够强度和粒度的部分液相粘结。最后,经过破碎、冷却和筛分,我们生产出成品烧结矿。主要生产过程包括配料、一次混合、二次混合、烧结、破碎、筛分、冷却和成品烧结矿。烧结生产会产生高硫烟气,需要进一步进行脱硫处理。
1.1.3 Coking
1.1.3 炼焦
Coke oven gas is a primary fuel type that is produced by sintering, coking, ironmaking, steelmaking and steel rolling processing and is used for blast furnace smelting. Coking production is the process of mixing and crushing specific coal types, and placing them in a coke oven to produce both hot and crude coke gas through the retorting process. The coking process will produce both coking gas and various other chemical products.
焦炉煤气是一种主要燃料类型,由烧结、炼焦、炼铁、炼钢和轧钢加工产生,用于高炉冶炼。炼焦生产是将特定类型的煤进行混合和粉碎,然后放入焦炉中,通过干馏过程产生热的粗焦炉煤气的过程。炼焦过程会产生焦炉煤气和各种其他化学产品。
The coke is produced through the carbonization process, in which clean coal is heated in the vacuum-sealed carbonization chamber of the coke oven. The red-hot coke is then sent to a coke quenching tower to be cooled, crushed, sieved and classified. Following this procedure, we are able to get different particle sizes of the coke products.
焦炭是通过碳化过程生产的,在这个过程中,洁净煤在焦炉的真空密封碳化室内加热。然后将炽热的焦炭送入焦炭淬火塔进行冷却、粉碎、筛分和分级。按照这个程序,我们能够得到不同粒度的焦炭产品。
1.2 Ironmaking
1.2 炼铁
Blast furnace ironmaking is used to make iron ore or iron-bearing materials into the qualified liquid iron by using a reducing agent (such as coke, coal, etc.) at high temperature.
高炉炼铁是利用还原剂(如焦炭、煤等)在高温下将铁矿石或含铁原料制成合格的液态铁。
The production process for blast furnace ironmaking is mainly composed of a blast furnace stack and a number of auxiliary systems. The body of blast furnace consists of a furnace throat, stack, bosh, belly, and hearth (moving from top to base of the structure). The auxiliary system consists primarily of feeding, air-supply, coal powder injection control, blast furnace cooling, iron slag and gas purification systems.
高炉炼铁的生产流程主要由高炉炉体和多个辅助系统组成。高炉炉体由炉喉、炉身、炉腰、炉腹和炉缸(从结构顶部到底部)组成。辅助系统主要由供料、送风、喷煤控制、高炉冷却、铁渣及煤气净化系统组成。
The blast furnace ironmaking process begins with the mixing of sinter, pellets, raw ore and other materials in prescribed proportions, sending the mixture to the top of a charging device via a belt or car, and keeping the material surface at a specific height. In this environment, the materials will form ore and coke in alternating layers within the furnace. The coke with then reacts with oxygen, forming carbon monoxide and hydrogen by blowing high-pressure, hot air from the tuyere around hearth. Descending furnace charge and rising coal gas will transfer heat, resulting in reduction, melting, decarburization of the coke to generate the raw iron and slag. Both the molten iron and slag are alternatively expelled from the base of the hearth. The slag and iron are then separated by the skimmer. Molten iron is poured into torpedo ladles or hot metal packages and are sent to steelmaking plants. After the quenching process by water, blast furnace slag can find its use in construction to produce cement. After various processing steps (gravity precipitation, bag dedusting and Top-Pressure Recovery Turbine Plant (TRT) power generation), the coal gas formed at the top furnace can be incorporated into a gas pipe network.
高炉炼铁过程始于将烧结矿、球团矿、原矿等物料按规定比例混合,通过皮带或小车将混合物输送至装料装置顶部,并使物料表面保持在特定高度。在此环境下,物料在炉内形成矿石和焦炭交替的层状结构。然后,焦炭与氧气反应,通过从炉缸风口周围鼓入高压热风形成一氧化碳和氢气。下降的炉料和上升的煤气进行热量传递,导致焦炭还原、熔化、脱碳,生成生铁和炉渣。铁水和炉渣交替从炉缸底部排出。炉渣和铁水随后通过撇渣器分离。铁水倒入鱼雷罐或铁水包中,送往炼钢厂。高炉炉渣经水淬处理后可用于建筑生产水泥。经过重力沉降、布袋除尘和余压透平发电装置(TRT)发电等各种处理步骤后,炉顶形成的煤气可并入煤气管网。
1.3 Steelmaking
1.3炼钢
The steelmaking process is divided into four processes: molten iron pretreatment, converter steelmaking, refining outside the furnace and continuous casting. The basic tasks of the steelmaking process require the removal of a number of elemental compounds (carbon, phosphorus, sulfur, nitrogen and hydrogen) and the removal the non-metallic inclusions. After this purification process, the material is then heated and molded.
炼钢过程分为四个工序:铁水预处理、转炉炼钢、炉外精炼和连铸。炼钢过程的基本任务是去除多种元素化合物(碳、磷、硫、氮和氢)并去除非金属夹杂物。经过此提纯过程后,材料再进行加热和成型。
1.3.1 Molten Iron Pretreatment
1.3.1 铁水预处理
Molten iron pretreatment is the preparation process for the molten iron of the blast furnace before it is sent to the steel furnace. Without an additional heat source, active substances in the treatment agents will react rapidly with sulfur, phosphorus and silicon. Thus, these elements are removed from the molten iron to form a stable slag phase separate from the molten iron. This process simplifies the steelmaking process and improves the quality of steel.
铁水预处理是高炉铁水在送入炼钢炉之前的准备过程。在没有额外热源的情况下,处理剂中的活性物质会与硫、磷和硅迅速反应。因此,这些元素从铁水中被去除,形成与铁水分离的稳定渣相。这个过程简化了炼钢工艺,提高了钢的质量。
1.3.2 The Converter Steelmaking
1.3.2 转炉炼钢
The oxygen converter allows high-speed oxygen to oxidize with the carbon, phosphorus, sulfur, nitrogen and hydrogen in steel to produce slag. The oxidation process also removes non-metallic elements and provides a heat source. The process of steel tapping includes charging and converting the material, deoxidizing steel tapping, slag-splashing for furnace protection and, finally, pouring the slag.
氧气转炉使高速氧气与钢中的碳、磷、硫、氮和氢发生氧化反应以产生炉渣。氧化过程还会去除非金属元素并提供热源。出钢过程包括装料与兑料、钢水脱氧、溅渣护炉,最后是倒渣。
1.3.3 Refining Outside the Furnace Process
1.3.3 炉外精炼工艺
Steel refining outside the furnace begins by converting the molten steel produced from primary smelting and pouring the converted steel into ladles. The steel proceeds to undergo deoxidization, desulphurization, decarbonization, and degassing. Non-metallic inclusions are then removed and liquid steel compositions are exposed to high temperatures and undergoes further smelting.
炉外钢精炼始于将初炼产生的钢水进行转化,并将转化后的钢水倒入钢包。钢水接着进行脱氧、脱硫、脱碳和脱气。然后去除非金属夹杂物,液态钢成分在高温下进一步熔炼。
1.3.4 Continuous Casting Process
1.3.4连铸工艺
The continuous casting process is to transform steel from molten state to solid state by use of molds during solid-state phase transformation. The liquid - solid phase change occurs when cool water reacts with the surface of the casting billet, causing the molten steel to undergo the processes of crystallization and casting. In the continuous casting process, the steel will undergo phase transformation and the ingot may experiences bending, correction and some other changes.
连铸工艺是在固态相变过程中利用结晶器将钢水由液态转变为固态。当冷水与铸坯表面发生反应时,会发生液 - 固相变,使钢水经历结晶和铸造过程。在连铸过程中,钢会发生相变,铸坯可能会经历弯曲、矫直等其他变化。
1.4 Steel Rolling
1.4 钢材轧制
The process of steel rolling places rolled pieces of steel into a high-speed roller to generate a desired shape. According to the product types of steel rolling, it can be divided into shaped steel, wire rod, sheet metal and pipe steel. According to production methods, it can be divided into hot rolling and cold rolling.
钢材轧制过程是将轧制好的钢坯放入高速轧辊中以形成所需形状。根据钢材轧制的产品类型,可分为型钢、线材、板材和管材。根据生产方法,可分为热轧和冷轧。
During the hot rolling process, steel is rolled at temperatures above the recrystallization temperature. This process includes: heating, dephosphorization, roughing rolling, top cutting, precision rolling, laminar cooling, crimp, finishing and plate cutting or heavy rolling.
在热轧过程中,钢在再结晶温度以上进行轧制。此过程包括:加热、脱磷、粗轧、切头、精轧、层流冷却、卷曲、精整和板材切割或重轧。
Cold rolling is steel rolling that occurs at temperatures below the recrystallization temperature. This process includes: dephosphorization with acid pickling, cold rolling, degreasing, annealing, leveling, skin rolling, classifying and packaging.
冷轧是在再结晶温度以下进行的钢材轧制。此过程包括:酸洗脱磷、冷轧、脱脂、退火、平整、光整轧制、分级和包装。
2 Review of Most Appropriate Carbon Capture and Utilization Technology
2最适用的碳捕获与利用技术综述
2.1 Carbon Capture Technology
2.1 碳捕获技术
The most appropriate technologies used to capture ${\mathrm{{CO}}}_{2}$ can be classified as five types (Carpenter, 2012):
用于捕获${\mathrm{{CO}}}_{2}$的最合适技术可分为五种类型(Carpenter,2012):
Adsorption;
吸附;
Chemical or physical absorption, or the combination;
化学或物理吸收,或两者结合;
Physical separation;
物理分离;
Phase separation;
相分离;
Chemical bonding.
化学键合。
2.1.1 Adsorption Capture Technology
2.1.1 吸附捕集技术
Adsorption is a mass transfer process where molecules from gas phase are attracted to the surface of a solid material. Adsorption technology in carbon capture involves the passing of a gas stream containing ${\mathrm{{CO}}}_{2}$ through a series of adsorbent beds, where ${\mathrm{{CO}}}_{2}$ are adsorbed. To achieve a desired carbon capture rate, multiple adsorbent cascades are usually used. Once the first adsorbent bed is saturated, the stream is sent to the second bed. The fully loaded bed can be regenerated for recycle use (Wilcox et al., 2014). Therefore, adsorption-based carbon capture is a cyclic process where adsorption and desorption operations are alternately applied. Based on the desorption technique, adsorption technology can be divided into two main categories: the pressure swing adsorption (PSA) (or vacuum pressure swing adsorption, VPSA) and the temperature swing adsorption (TSA) (Olajire, 2010; Wilcox et al., 2014). For PSA, bed regeneration is achieved via reducing the pressure. While for TSA, the adsorbent bed is recycled via increasing the temperature. PSA technology is usually to treat gas stream with high ${\mathrm{{CO}}}_{2}$ concentration, and when the concentration of ${\mathrm{{CO}}}_{2}$ is insignificant, TSA method is favored (Carpenter, 2012; Wilberforce et al., 2019).
吸附是一个传质过程,气相中的分子被吸引到固体材料的表面。碳捕集中的吸附技术涉及使含有${\mathrm{{CO}}}_{2}$的气流通过一系列吸附剂床层,其中${\mathrm{{CO}}}_{2}$被吸附。为了达到所需的碳捕集率,通常使用多个吸附剂级联。一旦第一个吸附剂床层饱和,气流就会被送到第二个床层。满载的床层可以再生以供循环使用(Wilcox等人,2014年)。因此,基于吸附的碳捕集是一个循环过程,其中吸附和解吸操作交替进行。根据解吸技术,吸附技术可分为两大类:变压吸附(PSA)(或真空变压吸附,VPSA)和变温吸附(TSA)(Olajire,2010年;Wilcox等人,2014年)。对于PSA,通过降低压力实现床层再生。而对于TSA,吸附剂床层通过升高温度进行循环。PSA技术通常用于处理高${\mathrm{{CO}}}_{2}$浓度的气流,当${\mathrm{{CO}}}_{2}$浓度较低时,更倾向于使用TSA方法(Carpenter,2012年;Wilberforce等人,2019年)。
Zeolites are crystalline aluminosilicate materials that have a highly ordered porous structure with pore sizes at sub-nanometer scales (Figueroa et al., 2008). Zeolites are widely used as commercial adsorbents for ${\mathrm{{CO}}}_{2}$ capture. Especially, Zeolite-13X is considered as a benchmark for ${\mathrm{{CO}}}_{2}$ adsorption under relatively low temperature (Bui et al., 2018; Hao et al., 2011). Early research has shown that the primary adsorption mechanism for zeolites is physical adsorption, while some studies report that the chemical adsorption mechanism also exists (Spigarelli &Kawatra,2013). To remove both physically and chemically adsorbed ${\mathrm{{CO}}}_{2}$ , the fully loaded zeolites are usually regenerated via a TSA method. The main virtue of zeolites as ${\mathrm{{CO}}}_{2}$ adsorbents are: (1) it has high ${\mathrm{{CO}}}_{2}$ capacity with fast adsorption kinetics; (2) the adsorption performance can be operated under relatively mild conditions $\left( {0 - {100}{}^{ \circ }\mathrm{C},0,1 - 1\text{ bar }{\mathrm{{CO}}}_{2}}\right)$ (Spigarelli &Kawatra,2013). The main drawback of zeolites is that zeolites are very sensitive to impurities such as ${\mathrm{{NO}}}_{\mathrm{x}}$ , ${\mathrm{{SO}}}_{\mathrm{x}}$ , and ${\mathrm{H}}_{2}\mathrm{O}$ . These impurities can strongly interact with zeolites, which significantly decrease the uptake of ${\mathrm{{CO}}}_{2}$ . Therefore, the flue gas needs to be scrubbed prior to zeolite adsorption process in order to remove any gaseous impurities.
沸石是结晶铝硅酸盐材料,具有高度有序的多孔结构,孔径在亚纳米尺度(Figueroa等人,2008年)。沸石被广泛用作商业${\mathrm{{CO}}}_{2}$捕集吸附剂。特别是,13X沸石被认为是相对低温下${\mathrm{{CO}}}_{2}$吸附的基准(Bui等人,2018年;Hao等人,2011年)。早期研究表明,沸石的主要吸附机制是物理吸附,而一些研究报告也存在化学吸附机制(Spigarelli & Kawatra,2013年)。为了去除物理和化学吸附的${\mathrm{{CO}}}_{2}$,满载的沸石通常通过TSA方法再生。沸石作为${\mathrm{{CO}}}_{2}$吸附剂的主要优点是:(1)具有高${\mathrm{{CO}}}_{2}$容量和快速吸附动力学;(2)吸附性能可以在相对温和的条件$\left( {0 - {100}{}^{ \circ }\mathrm{C},0,1 - 1\text{ bar }{\mathrm{{CO}}}_{2}}\right)$下运行(Spigarelli & Kawatra,2013年)。沸石的主要缺点是对${\mathrm{{NO}}}_{\mathrm{x}}$、${\mathrm{{SO}}}_{\mathrm{x}}$和${\mathrm{H}}_{2}\mathrm{O}$等杂质非常敏感。这些杂质会与沸石强烈相互作用,显著降低${\mathrm{{CO}}}_{2}$的吸附量。因此,在沸石吸附过程之前,需要对烟气进行洗涤以去除任何气态杂质。
Activated carbon is widely used as a physical adsorption material for ${\mathrm{{CO}}}_{2}$ capture (Lee & Park, 2015). It processes an advantage over other adsorbents for its low-cost and high thermal stability (Spigarelli & Kawatra, 2013). In addition, the pore size of activated can be easily adjusted via changing the material preparation and activation methods (Lee & Park, 2015). The structure of activated carbon can be further functionalized to improve the ${\mathrm{{CO}}}_{2}$ capacity and selectivity of the adsorbent.
活性炭被广泛用作${\mathrm{{CO}}}_{2}$捕集的物理吸附材料(Lee & Park,(2015))。它相对于其他吸附剂具有低成本和高热稳定性的优势(Spigarelli & Kawatra,2013年)。此外,通过改变材料制备和活化方法,可以很容易地调整活性炭的孔径(Lee & Park,2015年)。活性炭的结构可以进一步功能化,以提高吸附剂的${\mathrm{{CO}}}_{2}$容量和选择性。
Metal oxides such as $\mathrm{{CaO}}$ and $\mathrm{{MgO}}$ are common chemical adsorbents for ${\mathrm{{CO}}}_{2}$ separation. They can isolate ${\mathrm{{CO}}}_{2}$ through the formation of carbonates. MgO, in particular, has the advantages of low-cost, high abundancy, and low toxicity (Lee & Park, 2015). However, compared to zeolite and activated carbon, the ${\mathrm{{CO}}}_{2}$ capacity of $\mathrm{{MgO}}$ is relatively low, especially under dry conditions.
金属氧化物如$\mathrm{{CaO}}$和$\mathrm{{MgO}}$是用于${\mathrm{{CO}}}_{2}$分离的常见化学吸附剂。它们可以通过形成碳酸盐来分离${\mathrm{{CO}}}_{2}$。特别是MgO,具有低成本、高丰度和低毒性的优点(Lee & Park,2015年)。然而,与沸石和活性炭相比,$\mathrm{{MgO}}$的${\mathrm{{CO}}}_{2}$容量相对较低,特别是在干燥条件下。
2.1.2 Absorption Capture Technology
2.1.2 吸收捕集技术
Absorption is a chemical or physical process in which molecules of absorbate are dissolved in a bulk absorbent solution. It is a different process from adsorption as absorption is a bulk phase phenomenon whereas adsorption means accumulation of molecules at the surface. Absorption process is a commonly used technology in industry as well as in power plants to isolate ${\mathrm{{CO}}}_{2}$ from flue and fuel gases.
吸收是一种化学或物理过程,在此过程中,被吸收物的分子溶解在大量的吸收剂溶液中。它与吸附是不同的过程,因为吸收是一种体相现象,而吸附意味着分子在表面的积累。吸收过程是工业以及发电厂中用于从烟道气和燃料气中分离${\mathrm{{CO}}}_{2}$的常用技术。
Chemical Absorption
化学吸收
Chemical adsorption is known as the most mature and reliable strategy for ${\mathrm{{CO}}}_{2}$ separation (Leung et al.,2014). It is suitable for large scale ${\mathrm{{CO}}}_{2}$ removal and can be applied even with low flue gas concentration. As ${\mathrm{{CO}}}_{2}$ is an acidic gas, the chemical absorbents used for ${\mathrm{{CO}}}_{2}$ capture are usually amine-based solvents such as solutions of alkanolamines. During absorption process, flue gas containing ${\mathrm{{CO}}}_{2}$ is introduced from the bottom of a packed absorber column, and the absorbent is introduced from the top of the column. When the flue gas encounters the absorbent, they react with each other, forming an ${\mathrm{{CO}}}_{2}$ -rich stream. This stream is then sent to a regenerator unit, where ${\mathrm{{CO}}}_{2}$ can be stripped and absorbent solvent can be recycled through heating $\left( {{100} - {200}^{ \circ }\mathrm{C}}\right)$ . Amine absorption technology (amine scrubbing) with monoethanolamine (MEA) is a commercialized technology and is considered as the most mature ${\mathrm{{CO}}}_{2}$ capture technology in natural gas industry (Olajire, 2010). MEA process benefits from high reaction rate, low cost, and easy amine regeneration. The ${\mathrm{{CO}}}_{2}$ recycle rate can reach to ${98}\%$ (Olajire, 2010). However, this method suffers from several disadvantages such as (1) limited ${\mathrm{{CO}}}_{2}$ loading capacity (0.5 mol/mol amine) (Mondal et al.,2012); (2) high equipment corrosion rate; (3) amine loss due to ${\mathrm{{SO}}}_{2},{\mathrm{{NO}}}_{2},\mathrm{{HCl}},\mathrm{{HF}}$ , and oxygen in atmosphere; (4) high energy consumption during solvent regeneration.
化学吸附是${\mathrm{{CO}}}_{2}$分离最成熟、最可靠的策略(Leung等人,2014年)。它适用于大规模${\mathrm{{CO}}}_{2}$去除,即使在低烟气浓度下也可应用。由于${\mathrm{{CO}}}_{2}$是一种酸性气体,用于${\mathrm{{CO}}}_{2}$捕集的化学吸收剂通常是基于胺的溶剂,如链烷醇胺溶液。在吸收过程中,含${\mathrm{{CO}}}_{2}$的烟气从填料吸收塔底部引入,吸收剂从塔顶引入。当烟气与吸收剂相遇时,它们相互反应,形成富含${\mathrm{{CO}}}_{2}$的物流。然后该物流被送至再生单元,在那里${\mathrm{{CO}}}_{2}$可以被汽提,吸收剂溶剂可以通过加热$\left( {{100} - {200}^{ \circ }\mathrm{C}}\right)$进行循环。单乙醇胺(MEA)的胺吸收技术(胺洗涤)是一种商业化技术,被认为是天然气行业中最成熟的${\mathrm{{CO}}}_{2}$捕集技术(Olajire,2010年)。MEA工艺具有反应速率高、成本低和胺再生容易的优点。${\mathrm{{CO}}}_{2}$循环率可达${98}\%$(Olajire,2010年)。然而,该方法存在几个缺点,如(1)${\mathrm{{CO}}}_{2}$负载能力有限(0.5 mol/mol胺)(Mondal等人,2012年);(2)设备腐蚀速率高;(3)由于${\mathrm{{SO}}}_{2},{\mathrm{{NO}}}_{2},\mathrm{{HCl}},\mathrm{{HF}}$和大气中的氧气导致胺损失;(4)溶剂再生过程中能耗高。
Physical Absorption
物理吸收
For physical absorption, ${\mathrm{{CO}}}_{2}$ capture is based on the solubility of ${\mathrm{{CO}}}_{2}$ within the organic solvent, rather than the acid-base reaction. A high-temperature, low-pressure condition is favored to reach to an appropriate ${\mathrm{{CO}}}_{2}$ solubility. A typical absorbent used for physical absorption technology is Selexol. Selexol process has been commercially applied since 1969 to remove both ${\mathrm{{CO}}}_{2}$ and ${\mathrm{H}}_{2}\mathrm{\;S}$ from natural gas (Olajire,2010). The absorption process take place at $0 - {5}^{ \circ }\mathrm{C}$ . And Selexol solvent can be recycled via decreasing the pressure or bubbling air through the solution. The advantages of Selexol technology include: (1) low operation cost; (2) low heat rise; (3) gas is dry after selexaol treatment; (4) low energy required for solvent regeneration; (5) absorption can be conducted under low pressure. The main weakness of Selexol process include: (1) solvent degradation due to hydrocarbon loss; (2) the process is more efficient under high pressure.
对于物理吸收,${\mathrm{{CO}}}_{2}$ 的捕集基于其在有机溶剂中的溶解度,而非酸碱反应。高温、低压条件有利于达到合适的${\mathrm{{CO}}}_{2}$ 溶解度。物理吸收技术中使用的一种典型吸收剂是聚乙二醇二甲醚(Selexol)。自1969年以来,聚乙二醇二甲醚法已在商业上应用于从天然气中去除${\mathrm{{CO}}}_{2}$ 和${\mathrm{H}}_{2}\mathrm{\;S}$(奥拉吉尔,2010年)。吸收过程在$0 - {5}^{ \circ }\mathrm{C}$ 进行。聚乙二醇二甲醚溶剂可通过减压或向溶液中鼓入空气进行循环利用。聚乙二醇二甲醚技术的优点包括:(1)运行成本低;(2)热增量低;(3)经聚乙二醇二甲醚处理后的气体是干燥的;(4)溶剂再生所需能量低;(5)可在低压下进行吸收。聚乙二醇二甲醚法的主要缺点包括:(1)由于烃类损失导致溶剂降解;(2)该工艺在高压下效率更高。
2.1.3 Membranes Capture Technology
2.1.3 膜捕获技术
Membranes are selective barriers that act as filters to isolate specific gas molecules from the feed matrix (Favre, 2011; Merkel et al., 2010). Membrane technology is a relatively new approach that can be used to separate ${\mathrm{{CO}}}_{2}$ from flue gas, natural gas or hydrogen. It could also serve as another option besides cryogenic method to obtain pure oxygen from nitrogen (Mondal et al., 2012; Olajire, 2010). There are three main possible mechanisms for membrane separation: the Knudsen diffusion mechanism, the molecular sieving mechanism, and the solution diffusion mechanism (Giorno et al., 2015; Inagaki & Kang, 2014). Knudsen mechanism is based on the phenomenon that the gas molecules have more interactions with the pore wall than with each other if the pore diameter is smaller than the mean free path length of the diffusing gas molecules (Giorno et al., 2015). This method can be used to separate gases with different molecular weights. When a mixture of heavy gases and light gases enter the pore, the heavy gases will have more collision with the pore wall and lose more energy than the light gases. As a result, the heavy gases will pass through the membrane slower the light gasses. In this way, gas isolation can be achieved. Molecular sieving method separates gases on the basis of size. Molecular sieves are materials with very small pores. If the size of gas molecule is smaller than the pore size of molecular sieves, the gas can permeate, otherwise, the gas is stopped. The adsorption rate of gases highly depends on the pore size of molecular sieves. In addition, temperature also plays an important role in determining the adsorption rate of gas molecules (Inagaki & Kang, 2014). The solution diffusion mechanism is mainly applied to polymer membranes (Ismail et al., 2005). In solution diffusion model, gases are dissolved in membrane material and diffuse through the membrane, forming a concentration gradient. A separation is achieved owing to the differences in the solubility of gases in the membrane material and the diffusion rate of gas molecules.
膜是一种选择性屏障,起到过滤器的作用,将特定气体分子与进料基质分离(法夫尔,2011年;默克尔等人,2010年)。膜技术是一种相对较新的方法,可用于从烟道气、天然气或氢气中分离${\mathrm{{CO}}}_{2}$。它也可以作为除低温法之外从氮气中获得纯氧的另一种选择(蒙达尔等人,2012年;奥拉吉尔,2010年)。膜分离主要有三种可能的机制:克努森扩散机制、分子筛机制和溶液扩散机制(乔尔诺等人,2015年;稻垣和康,2014年)。克努森机制基于这样一种现象:如果孔径小于扩散气体分子的平均自由程长度,气体分子与孔壁的相互作用比它们之间的相互作用更多(乔尔诺等人,2015年)。这种方法可用于分离不同分子量的气体。当重气体和轻气体的混合物进入孔时,重气体与孔壁的碰撞比轻气体更多,损失的能量也更多。因此,重气体通过膜的速度比轻气体慢。通过这种方式,可以实现气体分离。分子筛方法根据尺寸分离气体。分子筛是具有非常小孔的材料。如果气体分子的尺寸小于分子筛的孔径,气体就可以渗透,否则气体就会被阻挡。气体的吸附速率高度取决于分子筛的孔径。此外,温度在决定气体分子的吸附速率方面也起着重要作用(稻垣和康,2014年)。溶液扩散机制主要应用于聚合物膜(伊斯梅尔等人,2005年)。在溶液扩散模型中,气体溶解在膜材料中并通过膜扩散,形成浓度梯度。由于气体在膜材料中的溶解度和气体分子的扩散速率不同,从而实现分离。
Membranes can be made of either organic (polymeric) or inorganic (metallic, ceramic, zeolite, carbon) materials (Olajire, 2010). Generally, polymeric membranes are primarily based on the solution-diffusion mechanism. Some of the polymers that have been studied and applied in membrane technology include polysulfones, polyamides, polyacetylenes, polyanilines, etc. (Lee & Park, 2015; Olajire, 2010). Inorganic membranes mainly rely on the Knudsen diffusion and molecular sieving mechanisms. Inorganic membranes can be divided into two categories: nonporous (dense) inorganic and porous inorganic membranes (Seoane et al., 2015). Nonporous inorganic membranes are generally utilized for selective separation of hydrogen (through palladium alloys) or oxygen (through perovskite materials). Porous inorganic membranes such as carbon and zeolites can be functionalized with a layer of ${\mathrm{{CO}}}_{2}$ -philic compound to improve their affinities towards ${\mathrm{{CO}}}_{2}$ . Membrane technology benefits from its process simplicity, high flexibility, low energy use, and low requirements for chemical addition (Lee & Park, 2015). However, membrane is not suitable for large-scale filtration. And the durability of membrane material is relatively low. Therefore, a multistage configuration is usually applied in membranes-based system to achieve continuous separation and obtain ${\mathrm{{CO}}}_{2}$ with desired purity (Faruque Hasan et al.,2014).
膜可以由有机(聚合物)或无机(金属、陶瓷、沸石、碳)材料制成(奥拉吉尔,2010年)。一般来说,聚合物膜主要基于溶液扩散机制。一些已在膜技术中研究和应用的聚合物包括聚砜、聚酰胺、聚乙炔、聚苯胺等(李和帕克,2015年;奥拉吉尔,2010年)。无机膜主要依赖克努森扩散和分子筛机制。无机膜可分为两类:无孔(致密)无机膜和多孔无机膜(塞奥阿内等人,2015年)。无孔无机膜通常用于氢气(通过钯合金)或氧气(通过钙钛矿材料)的选择性分离。多孔无机膜如碳和沸石可以用一层${\mathrm{{CO}}}_{2}$亲水性化合物进行功能化处理,以提高它们对${\mathrm{{CO}}}_{2}$的亲和力。膜技术因其工艺简单、灵活性高、能耗低和对化学添加要求低而具有优势(李和帕克,2015年)。然而,膜不适合大规模过滤。并且膜材料的耐久性相对较低。因此,基于膜的系统通常采用多级配置来实现连续分离并获得所需纯度的${\mathrm{{CO}}}_{2}$(法鲁克·哈桑等人,2014年)。
2.1.4 Cryogenics Capture Technology
2.1.4 低温捕集技术
Cryogenic distillation method is another commercially available approach for ${\mathrm{{CO}}}_{2}$ separation (Mondal et al., 2012; Olajire, 2010). It is a process that involves cooling and compression of gases, and is commonly used to produce liquid phase ${\mathrm{{CO}}}_{2}$ . Cryogenic technology is suitable for capture ${\mathrm{{CO}}}_{2}$ with relatively high concentration. During cryogenic process, ${\mathrm{{CO}}}_{2}$ gas is cooled at a very low temperature and desublimates to solid phase. The solid ${\mathrm{{CO}}}_{2}$ is isolated from the gaseous matrix and the separation is achieved. The frozen ${\mathrm{{CO}}}_{2}$ is then melted with lifting temperature to obtain purified liquid ${\mathrm{{CO}}}_{2}$ .
低温蒸馏法是另一种可用于${\mathrm{{CO}}}_{2}$分离的商业方法(Mondal等人,2012年;Olajire,2010年)。这是一个涉及气体冷却和压缩的过程,通常用于生产液相${\mathrm{{CO}}}_{2}$。低温技术适用于捕集浓度相对较高的${\mathrm{{CO}}}_{2}$。在低温过程中,${\mathrm{{CO}}}_{2}$气体在非常低的温度下冷却并凝华成固相。将固体${\mathrm{{CO}}}_{2}$与气态基质分离,从而实现分离。然后通过升高温度使冷冻的${\mathrm{{CO}}}_{2}$融化,以获得纯化的液态${\mathrm{{CO}}}_{2}$。
Cryogenic process is a method with high reliability and low investigation cost. It can be applied as an alternative to chemical scrubbing method because it requires less water during operation and generates fewer chemical pollutions. In addition, the cost for cryogenic distillation is relatively low and the device for cryogenic system is more corrosion resistant (Lee & Park, 2015; Wilberforce et al.,2019). As the obtained ${\mathrm{{CO}}}_{2}$ is a cryogenic liquid, they can be easily transported. In fact, in terms of transporting ${\mathrm{{CO}}}_{2}$ by ship, it is most convenient and economically friendly to transport ${\mathrm{{CO}}}_{2}$ in a liquid form (Boot-Handford et al., 2014). Although cryogenic technology offers many advantages, it also suffers from several drawbacks (Olajire, 2010). First, the cooling and heating processes of cryogenic distillation need to consume a great amount of energy, which creates significant energy penalty for carbon capture. Second, impurities such as ${\mathrm{{SO}}}_{\mathrm{X}}$ , ${\mathrm{{NO}}}_{\mathrm{x}}$ , and ${\mathrm{H}}_{2}\mathrm{O}$ can have negative impact on the distillation process. These impurities can also cause corrosion and plugging to the equipment. The formation of ice from water molecules can block pipes and result in severe safety problems. Therefore, it is important to remove trace moisture from feed gas prior to the cryogenic approach, which increases the cost.
低温过程是一种可靠性高且研究成本低的方法。它可以作为化学洗涤法的替代方法,因为它在运行过程中需要的水较少,产生的化学污染也较少。此外,低温蒸馏的成本相对较低,低温系统的设备更耐腐蚀(Lee和Park,2015年;Wilberforce等人,2019年)。由于获得的${\mathrm{{CO}}}_{2}$是低温液体,它们可以很容易地运输。事实上,就通过船舶运输${\mathrm{{CO}}}_{2}$而言,以液体形式运输${\mathrm{{CO}}}_{2}$是最方便且经济上最有利的(Boot-Handford等人,2014年)。尽管低温技术有许多优点,但它也有几个缺点(Olajire,2010年)。首先,低温蒸馏的冷却和加热过程需要消耗大量能量,这给碳捕集带来了巨大的能量惩罚。其次,诸如${\mathrm{{SO}}}_{\mathrm{X}}$、${\mathrm{{NO}}}_{\mathrm{x}}$和${\mathrm{H}}_{2}\mathrm{O}$等杂质会对蒸馏过程产生负面影响。这些杂质还会导致设备腐蚀和堵塞。水分子形成的冰会堵塞管道并导致严重的安全问题。因此,在采用低温方法之前,从原料气中去除微量水分很重要,这增加了成本。
2.1.5 Gas Hydrate-Based Capture Technology
2.1.5基于气体水合物的捕集技术
Hydrate-based ${\mathrm{{CO}}}_{2}$ capture (HBCC) technology is a relatively novel ${\mathrm{{CO}}}_{2}$ capture process. Due to numerous advantages over conventional capture technologies, HBCC has drawn lots of attention from academia and industry. Advantages include mild operational temperature, easy recycling of aqueous solution, allowance of large-scale operation and most importantly, economic advantage (Dashti et al.,2015). The capture mechanism is rather simple. When ${\mathrm{{CO}}}_{2}$ contacts with water under certain condition (below equilibrium temperature and above equilibrium pressure), it forms gas hydrate in which ${\mathrm{{CO}}}_{2}$ concentration is much higher than the gas phase. Subsequently, gas hydrate is separated from the gas and ${\mathrm{{CO}}}_{2}$ is collected from the hydrates in a dissociation reactor, either by heating or depres-surization. The water remained is recycled and used in the gas hydrate formation process again. In practice, the whole process is repeated several times to increase the purity of ${\mathrm{{CO}}}_{2}$ . Also, chemical additives are needed to reduce the equilibrium pressure (thermodynamic promoters) and increase the hydrate formation rate (kinetic promoters). The chemical additives receive lots of research interests. Propane, cyclopentane, tetrahydrofuran and tetra-n-butyl ammonium bromide are most investigated thermodynamic promoters while dodecyl-trimethyl-ammonium chloride, sodium dodecyl sulphate, and Tween-80 are commonly used kinetic promoters.
基于水合物的${\mathrm{{CO}}}_{2}$捕集(HBCC)技术是一种相对新颖的${\mathrm{{CO}}}_{2}$捕集工艺。由于相较于传统捕集技术具有诸多优势,HBCC已引起学术界和工业界的广泛关注。优势包括操作温度温和、水溶液易于循环利用、可大规模运行,最重要的是具有经济优势(Dashti等人,2015年)。捕集机制相当简单。当${\mathrm{{CO}}}_{2}$在特定条件下(低于平衡温度且高于平衡压力)与水接触时,会形成气体水合物,其中${\mathrm{{CO}}}_{2}$的浓度远高于气相。随后,将气体水合物与气体分离,并在解离反应器中通过加热或减压从水合物中收集${\mathrm{{CO}}}_{2}$。剩余的水被循环利用并再次用于气体水合物形成过程。在实际操作中,整个过程会重复多次以提高${\mathrm{{CO}}}_{2}$的纯度。此外,还需要化学添加剂来降低平衡压力(热力学促进剂)并提高水合物形成速率(动力学促进剂)。化学添加剂受到了大量研究关注。丙烷、环戊烷、四氢呋喃和四丁基溴化铵是研究最多的热力学促进剂,而十二烷基三甲基氯化铵、十二烷基硫酸钠和吐温80是常用的动力学促进剂。
2.1.6 Mineral Carbonation Capture Technology
2.1.6 矿物碳酸化捕集技术
Slags are by-products produced after desired metal has been separated from its own ore. In iron and steel making process, slags are composed of silicates, free lime and other minerals and thus are capable of reacting with ${\mathrm{{CO}}}_{2}$ . For example, calcium oxide in the slags could react with ${\mathrm{{CO}}}_{2}$ to form calcite. Such reaction is called mineral carbonation by which ${\mathrm{{CO}}}_{2}$ is captured and permanently stored. Generally, two types of carbonation processes are developing (Baciocchi et al., 2010). The direct carbonation involves ${\mathrm{{CO}}}_{2}$ reacting with slags directly, either in the aqueous phase or at the gas-solid interface. However, in the indirect carbonation process, the metal in slags is firstly extracted with hydrochloric acid (Kunzler et al., 2011), acetic acid (Eloneva et al., 2008; Teir et al., 2007), nitric acid (Doucet, 2010), hydroxides or ammonium salts (Fogelholm et al., 2009). Then ${\mathrm{{CO}}}_{2}$ reacts with extracted metal to form precipitate.
炉渣是在所需金属从其矿石中分离出来后产生的副产品。在钢铁制造过程中,炉渣由硅酸盐、游离石灰和其他矿物质组成,因此能够与${\mathrm{{CO}}}_{2}$发生反应。例如,炉渣中的氧化钙可以与${\mathrm{{CO}}}_{2}$反应形成方解石。这种反应被称为矿物碳酸化,通过它${\mathrm{{CO}}}_{2}$被捕获并永久储存。一般来说,有两种碳酸化工艺正在发展(巴乔基等人,2010年)。直接碳酸化涉及${\mathrm{{CO}}}_{2}$直接与炉渣反应,无论是在水相中还是在气固界面。然而,在间接碳酸化过程中,首先用盐酸(昆兹勒等人,2011年)、乙酸(埃洛内瓦等人,2008年;蒂尔等人,2007年)、硝酸(杜塞,2010年)、氢氧化物或铵盐(福格尔霍尔姆等人,2009年)从炉渣中提取金属。然后${\mathrm{{CO}}}_{2}$与提取的金属反应形成沉淀。
Capturing ${\mathrm{{CO}}}_{2}$ with mineral carbonation has its limitations. First of all, the process has large energy consumption and the solvent regeneration is expensive (Doucet, 2010). Additionally, the whole process itself generates large quantities of ${\mathrm{{CO}}}_{2}$ which makes the capture less efficient. However, the process has numerous advantages. Economically, produced products of the carbonation are profitable. For instance, the carbonates are highly demanded in agricultural and construction applications. Carbonates with high quality would enable its sale to the paper industry (Fogelholm et al., 2009). On the other hand, the process has environmental benefits. Carbonated slag blocks can be put into the ocean to promote the algae growth which will transform ${\mathrm{{CO}}}_{2}$ into ${\mathrm{O}}_{2}$ through photosynthesis (Baoshan Iron & Steel, 2008). The blocks can also be used in endangered reef areas to buffer the ocean acidification.
用矿物碳酸化捕集${\mathrm{{CO}}}_{2}$有其局限性。首先,该过程能耗大,溶剂再生成本高(杜塞,2010年)。此外,整个过程本身会产生大量的${\mathrm{{CO}}}_{2}$,这使得捕集效率降低。然而,该过程有许多优点。在经济上,碳酸化产生的产品是有利可图的。例如,碳酸盐在农业和建筑应用中有很高的需求。高质量的碳酸盐可以出售给造纸工业(福格尔霍尔姆等人,2009年)。另一方面,该过程有环境效益。碳酸化的炉渣块可以放入海洋中以促进藻类生长,藻类将通过光合作用将${\mathrm{{CO}}}_{2}$转化为${\mathrm{O}}_{2}$(宝山钢铁,2008年)。这些块也可以用于濒危珊瑚礁地区以缓冲海洋酸化。
2.1.7 Emerging Carbon Capture Technologies
2.1.7新兴碳捕集技术
In recent years, a great number of emerging carbon capture technologies have been reported as promising solutions to reduce ${\mathrm{{CO}}}_{2}$ emission. Some of the innovative low-carbon technologies have already been applied in demonstration scale or are in early commercialization stage (ADB, 2020). For example, solid sorbent technology, as a new ${\mathrm{{CO}}}_{2}$ capture process that can isolate over ${90}\%$ of ${\mathrm{{CO}}}_{2}$ from the post-combustion flue gas stream, has been commercialized through the ViennaGree ${\mathrm{{CO}}}_{2}$ project, and will be used in pilot plants in Netherlands. A following TuilpGreen ${\mathrm{{CO}}}_{2}$ demonstration project is also in progress to upscale this technology to full commercial stage. A ${\mathrm{{CO}}}_{2}$ capture system proposed by Francois Marechal team aims to separate ${\mathrm{{CO}}}_{2}$ from internal combustion engine. This proposed system is still in research stage, but it shows great potential to be applied in Asia and other regions. Another ${\mathrm{{CO}}}_{2}$ capture technology that is highly relevant for implementation in Asia is called the Compact Carbon Capture system. The size of this system can be up to ${75}\%$ smaller than conversional amine capture systems, which means that the Compact Carbon Capture system can be built in many of the existing power plants where CCS model was not designed in advance. Recently, Carbon Infinity, a company that was founded by research experts at Shanghai Jiao Tong University, developed a direct air capture (DAC) system that enables the removal of ${\mathrm{{CO}}}_{2}$ from gas mixture and convert ${\mathrm{{CO}}}_{2}$ to value-added carbon-based industrial products. DAC system has attracted the attention of the Abu Dhabi government, and there has been increasing interests across Asia in bringing this system to market.
近年来,大量新兴碳捕集技术被报道为降低${\mathrm{{CO}}}_{2}$排放的可行解决方案。一些创新的低碳技术已进入示范规模应用阶段或处于早期商业化阶段(亚洲开发银行,2020年)。例如,固体吸附剂技术作为一种新型的${\mathrm{{CO}}}_{2}$捕集工艺,能够从燃烧后烟道气流中分离出超过${90}\%$的${\mathrm{{CO}}}_{2}$,已通过维也纳绿色${\mathrm{{CO}}}_{2}$项目实现商业化,并将在荷兰的试点工厂中使用。随后的郁金香绿色${\mathrm{{CO}}}_{2}$示范项目也在推进,以将该技术提升至全面商业阶段。弗朗索瓦·马雷夏尔团队提出的一种${\mathrm{{CO}}}_{2}$捕集系统旨在从内燃机中分离${\mathrm{{CO}}}_{2}$。该系统仍处于研究阶段,但在亚洲和其他地区具有巨大的应用潜力。另一种与在亚洲实施高度相关的${\mathrm{{CO}}}_{2}$捕集技术称为紧凑型碳捕集系统。该系统的尺寸比传统胺捕集系统小多达${75}\%$,这意味着紧凑型碳捕集系统可以安装在许多未预先设计CCS模式的现有发电厂中。最近,由上海交通大学研究专家创立的Carbon Infinity公司开发了一种直接空气捕集(DAC)系统,该系统能够从混合气体中去除${\mathrm{{CO}}}_{2}$,并将${\mathrm{{CO}}}_{2}$转化为增值碳基工业产品。DAC系统已引起阿布扎比政府的关注,亚洲各地对将该系统推向市场的兴趣也在不断增加。
2.1.8 Carbon Capture Recommendation
2.1.8 碳捕获建议
Carbon capture face some limitations. As can be seen, many capture technologies suffer from high energy consumption and, where used, steam consumption. A potential solution is to utilize waste heat from other on-site processes to regenerate the capture solvents. Another limitation is economical. By far, ${\mathrm{{CO}}}_{2}$ capture is expensive which will hinder its widespread commercial deployment. There are two solutions towards this problem. First of all, promoting large CCS projects could be helpful in cutting costs since large-scale ${\mathrm{{CO}}}_{2}$ capture costs less. Furthermore, developing new technologies is another way forward. For example, HIsarna process, which is designed to generate a nitrogen-free and ${\mathrm{{CO}}}_{2}$ -rich off gas which will make ${\mathrm{{CO}}}_{2}$ capture easier and cheaper. If these two limitations are overcome, then CCS projects could be more widely deployed.
碳捕获面临一些限制。可以看出,许多捕获技术存在高能耗问题,并且在使用时还存在蒸汽消耗问题。一个潜在的解决方案是利用其他现场工艺产生的废热来再生捕获溶剂。另一个限制是经济性。到目前为止,${\mathrm{{CO}}}_{2}$捕获成本高昂,这将阻碍其广泛的商业部署。针对这个问题有两种解决方案。首先,推动大型碳捕集与封存项目可能有助于降低成本,因为大规模${\mathrm{{CO}}}_{2}$捕获成本更低。此外,开发新技术是另一条前进的道路。例如,希萨纳法(HIsarna process)旨在产生无氮且富含${\mathrm{{CO}}}_{2}$的废气,这将使${\mathrm{{CO}}}_{2}$捕获更容易且更便宜。如果克服了这两个限制,那么碳捕集与封存项目就可以更广泛地部署。
3 Carbon Utilization Technology
3 碳利用技术
Millions of tonnes of ${\mathrm{{CO}}}_{2}$ are used in industry each year, and the idea that combining ${\mathrm{{CO}}}_{2}$ utilization with $\mathrm{{CCS}}$ is quite appealing. Instead of disposing ${\mathrm{{CO}}}_{2}$ as a waste, delivering it to willing buyers is a better way on an economic analysis. However, ${\mathrm{{CO}}}_{2}$ utilization could only act as a driving force to develop CCS but cannot replace geological storage. The reason is that the uses are rather limited when considered to be applied to CCS. For instance, the global beverage industry consumes nearly 8 million tonnes ${\mathrm{{CO}}}_{2}$ per year, which is only ${0.5}\%$ of the ${\mathrm{{CO}}}_{2}$ need to be captured and stored by 2030. Therefore, the ${\mathrm{{CO}}}_{2}$ demand of different approaches should be considered in order to match the capture capacity. The emission reductions and financial contribution should also be analyzed.
每年有数百万吨的${\mathrm{{CO}}}_{2}$被用于工业,并且将${\mathrm{{CO}}}_{2}$利用与$\mathrm{{CCS}}$相结合的想法很有吸引力。从经济分析的角度来看,将${\mathrm{{CO}}}_{2}$交付给有意愿的买家,而不是将其作为废物处理,是更好的方式。然而,${\mathrm{{CO}}}_{2}$利用只能作为发展碳捕集与封存(CCS)的驱动力,而不能取代地质封存。原因在于,考虑将其应用于CCS时,其用途相当有限。例如,全球饮料行业每年消耗近800万吨${\mathrm{{CO}}}_{2}$,这仅占2030年需要捕集和封存的${\mathrm{{CO}}}_{2}$的${0.5}\%$。因此,为了匹配捕集能力,应考虑不同方法的${\mathrm{{CO}}}_{2}$需求。还应分析减排量和资金贡献。
3.1 CO2 Used for Enhanced Oil Recovery
3.1 用于提高石油采收率的二氧化碳
Enhanced oil recovery is the major source of ${\mathrm{{CO}}}_{2}$ utilization, with ${70}\mathrm{{Mt}}{\mathrm{{CO}}}_{2}$ used annually, which is also called tertiary oil recovery. ${\mathrm{{CO}}}_{2}$ -EOR technology is injecting ${\mathrm{{CO}}}_{2}$ into an underground geologic zone that contains hydrocarbons to produce the oil. The ${\mathrm{{CO}}}_{2}$ is produced together with oil and then recycled back to recover more oil.
提高石油采收率是${\mathrm{{CO}}}_{2}$利用的主要来源,每年使用${70}\mathrm{{Mt}}{\mathrm{{CO}}}_{2}$,也称为三次采油。${\mathrm{{CO}}}_{2}$-EOR技术是将${\mathrm{{CO}}}_{2}$注入含有碳氢化合物的地下地质区域以开采石油。${\mathrm{{CO}}}_{2}$与石油一起产出,然后循环回注以开采更多石油。
The United States began to conduct relevant projects decades ago and has sequestrated millions of tonnes of ${\mathrm{{CO}}}_{2}$ underground. However, only around one-third of quantities of ${\mathrm{{CO}}}_{2}$ are from anthropogenic sources. Additionally, at present the main concern of ${\mathrm{{CO}}}_{2}$ -EOR is to enhance oil recovery. Therefore, EOR technology should be improved when used either primarily or secondarily for CCS. For example, incorporating monitoring and validation systems into EOR could help ensure the long-term retention of ${\mathrm{{CO}}}_{2}$ .
美国在几十年前就开始开展相关项目,已在地下封存了数百万吨的${\mathrm{{CO}}}_{2}$。然而,其中只有约三分之一的${\mathrm{{CO}}}_{2}$来自人为源。此外,目前${\mathrm{{CO}}}_{2}$ -EOR的主要关注点是提高石油采收率。因此,在将EOR技术主要或次要用于CCS时,都应加以改进。例如,在EOR中纳入监测和验证系统有助于确保${\mathrm{{CO}}}_{2}$的长期封存。
Sequestrating ${\mathrm{{CO}}}_{2}$ in reservoirs can not only enhance oil and gas recovery, but could have the added benefit of reducing ${\mathrm{{CO}}}_{2}$ emission. However, when we use numerical models to simulate the process of ${\mathrm{{CO}}}_{2}$ -EOR, a problem arises when ${\mathrm{{CO}}}_{2}$ sequestration and EOR should be co-optimized at the same time. Jahangiri and Zhang (2012) proposed the ensemble-based optimization (EnOpt) method to optimize ${\mathrm{{CO}}}_{2}$ storage and oil recovery process simultaneously.
将${\mathrm{{CO}}}_{2}$封存于油藏不仅可以提高油气采收率,还能额外减少${\mathrm{{CO}}}_{2}$排放。然而,当我们使用数值模型来模拟${\mathrm{{CO}}}_{2}$-EOR过程时,会出现一个问题,即${\mathrm{{CO}}}_{2}$封存和EOR需要同时进行协同优化。Jahangiri和Zhang(2012年)提出了基于系综的优化(EnOpt)方法,以同时优化${\mathrm{{CO}}}_{2}$储存和原油采收过程。
This study takes both ${\mathrm{{CO}}}_{2}$ storage and oil production into account and uses net present value of the CCS project as the optimization objective function. The proposed methodology presented in this work can be achieved with most reservoir simulators and thus designing and co-optimizing the coupled ${\mathrm{{CO}}}_{2}$ sequestration and EOR is possible.
本研究兼顾了${\mathrm{{CO}}}_{2}$封存和石油生产,并将CCS项目的净现值作为优化目标函数。本工作中提出的方法可以通过大多数油藏模拟器实现,因此耦合${\mathrm{{CO}}}_{2}$封存和提高采收率的设计与协同优化是可行的。
3.2 CO2 Used in Iron Making Process
3.2 炼铁过程中使用的二氧化碳
Hong (2012) from Northeastern University China applied ${\mathrm{{CO}}}_{2}$ as a desiliconizing agent for hot metal. The experiments were carried out in a laboratory induction furnace, with 1 kg of material prepared using a pig iron with iron silicide with silicon content around ${0.745}\mathrm{{wt}}\% .{\mathrm{{CO}}}_{2}$ is injected into hot metal through a quartz tube for desiliconizing under different temperatures ranging from 1300 to ${1500}{}^{ \circ }\mathrm{C}$ , and different gas flow rates ranging between 0.2 and ${0.6}\mathrm{\;L}{\mathrm{\;{min}}}^{-1}$ . The results showed that the mass transfer of gas is the rate-limiting step of desi-liconizing reaction with ${\mathrm{{CO}}}_{2}$ . Under constant temperature, higher gas flow rate will give better desilication. On the contrary, at certain gas flow rate, higher temperature leads to lesser desilication. This is in conformity with thermodynamic analysis since desilication is an exothermic reaction and lower temperature would favour desilication.
中国东北大学的Hong(2012年)将${\mathrm{{CO}}}_{2}$用作铁水的脱硅剂。实验在实验室感应炉中进行,使用含硅化铁且硅含量约为${0.745}\mathrm{{wt}}\% .{\mathrm{{CO}}}_{2}$的生铁制备1千克物料,通过石英管在1300至${1500}{}^{ \circ }\mathrm{C}$的不同温度以及0.2至${0.6}\mathrm{\;L}{\mathrm{\;{min}}}^{-1}$的不同气体流速下将其注入铁水进行脱硅。结果表明,气体传质是使用${\mathrm{{CO}}}_{2}$进行脱硅反应的限速步骤。在恒温下,较高的气体流速会带来更好的脱硅效果。相反,在一定气体流速下,较高温度会导致脱硅较少。这与热力学分析一致,因为脱硅是放热反应,较低温度有利于脱硅。
Guo et al. (2010) patented the use ${\mathrm{{CO}}}_{2}$ as the transmission medium for pulverized coal injection into a blast furnace instead of ${\mathrm{N}}_{2}$ or compressed air. Pulverized coal was first transferred by ${\mathrm{{CO}}}_{2}$ from bins to pipes then injected into BF with ${\mathrm{{CO}}}_{2}$ as the carrier. This was expected to enhance the proportion of $\mathrm{{CO}}$ in the BF gas, hence increase the quality and reducing the coke rate. This is in part due to ${\mathrm{{CO}}}_{2}$ concentrations around tuyeres being very high, and the reaction $\mathrm{C}\left( \mathrm{s}\right) + \; {\mathrm{O}}_{2}\left( \mathrm{\;g}\right) = {\mathrm{{CO}}}_{2}\left( \mathrm{\;g}\right)$ will be restrained while the reaction ${\mathrm{{CO}}}_{2}\left( \mathrm{\;g}\right) + \mathrm{C}\left( \mathrm{s}\right) = 2\mathrm{{CO}}\left( \mathrm{g}\right)$ will be promoted. One should notice that it is essential to control the ${\mathrm{{CO}}}_{2}$ proportion in the mixed gas, because higher ${\mathrm{{CO}}}_{2}$ will increase the potential energy of the coke reaction. This will result in large amounts of cracks and pores within the coke, decreasing the coke strength. In this case, it will deteriorate the permeability of stock column during the descending process.
郭等人(2010年)获得了一项专利,该专利使用${\mathrm{{CO}}}_{2}$作为将煤粉喷入高炉的输送介质,以替代${\mathrm{N}}_{2}$或压缩空气。煤粉首先由${\mathrm{{CO}}}_{2}$从料仓输送至管道,然后以${\mathrm{{CO}}}_{2}$作为载体喷入高炉。这有望提高高炉煤气中$\mathrm{{CO}}$的比例,从而提高质量并降低焦比。部分原因是风口周围的${\mathrm{{CO}}}_{2}$浓度非常高,反应$\mathrm{C}\left( \mathrm{s}\right) + \; {\mathrm{O}}_{2}\left( \mathrm{\;g}\right) = {\mathrm{{CO}}}_{2}\left( \mathrm{\;g}\right)$将受到抑制,而反应${\mathrm{{CO}}}_{2}\left( \mathrm{\;g}\right) + \mathrm{C}\left( \mathrm{s}\right) = 2\mathrm{{CO}}\left( \mathrm{g}\right)$将得到促进。需要注意的是,控制混合气体中的${\mathrm{{CO}}}_{2}$比例至关重要,因为${\mathrm{{CO}}}_{2}$含量过高会增加焦炭反应的势能。这将导致焦炭内部出现大量裂纹和孔隙,降低焦炭强度。在这种情况下,会使炉料柱在下降过程中的透气性变差。
Almost at the same time in 2010, Fu et al. (2010) invented a method of injecting carbon dioxide into BF with the aim to reduce the coke ratio. ${\mathrm{{CO}}}_{2}$ is produced from the exhaust gas of the hot blast stove or other exhaust gases which contain ${\mathrm{{CO}}}_{2}$ . Replacing the ${\mathrm{O}}_{2}$ -rich gas stream with ${\mathrm{{CO}}}_{2}$ will result in drastic decreases in temperature, hence the temperature of the injecting gas needs to be increased when introducing ${\mathrm{{CO}}}_{2}$ into the BF. There is no industrial application being reported for the above two patents, maybe because it is difficult to operate.
2010年几乎同时,Fu等人(2010年)发明了一种向高炉中注入二氧化碳以降低焦比的方法。${\mathrm{{CO}}}_{2}$由热风炉废气或其他含${\mathrm{{CO}}}_{2}$的废气产生。用${\mathrm{{CO}}}_{2}$替代富含${\mathrm{O}}_{2}$的气流将导致温度急剧下降,因此在将${\mathrm{{CO}}}_{2}$引入高炉时需要提高注入气体的温度。上述两项专利均未报道有工业应用,可能是因为操作困难。
3.3 CO2 Used in Steel Making Process
3.3 炼钢过程中使用的二氧化碳
3.3.1 CO2 Used in Converter Process
3.3.1 转炉工艺中使用的二氧化碳
Decarburization
脱碳
The use of ${\mathrm{{CO}}}_{2}$ for decarburization has a history of around 30 years in China. Back in 1985, Jin (1985), an industrial researcher from Shanghai’s No. 1 steel plant, reported the positive effects of ${\mathrm{N}}_{2} - {\mathrm{{CO}}}_{2}$ bottom blowing in a ${15}\mathrm{t}$ converter. It was reported that this application can enhance the decarburization efficiency and decrease the total iron oxide concentrations $\left( {\sum }^{\mathrm{{FeO}}}\right)$ in the final slag. However, the corrosion of the refractory around tuyere was found to be severe.
在中国,使用${\mathrm{{CO}}}_{2}$进行脱碳已有约30年的历史。早在1985年,上海第一钢铁厂的工业研究员金(1985年)报告了在${15}\mathrm{t}$转炉中进行${\mathrm{N}}_{2} - {\mathrm{{CO}}}_{2}$底吹的积极效果。据报道,这种应用可以提高脱碳效率,并降低终渣中总氧化铁浓度$\left( {\sum }^{\mathrm{{FeO}}}\right)$。然而,发现风口周围的耐火材料腐蚀严重。
Wang (1986, 1989) carried out a series studies during 1986-1989 on the bottom blowing of ${\mathrm{{CO}}}_{2}$ bearing gases. The high temperature experiments were carried out and the result showed that with ${\mathrm{{CO}}}_{2}$ bottom blowing, the decarburization rate is larger than other gases in the middle period of decarburization. Similar work was carried out elsewhere (Hara et al., 1986; Paules, 1987), aiming to investigate the effect of ${\mathrm{{CO}}}_{2}$ during bottom blowing. The results of these studies showed that ${\mathrm{{CO}}}_{2}$ is an effective alternative for ${\mathrm{N}}_{2}/\mathrm{{Ar}}$ bottom blowing, since it will not increase the nitrogen content in liquid steel. This would also be a superior alternative to bottom blowing ${\mathrm{O}}_{2}/{\mathrm{C}}_{x}{\mathrm{H}}_{y}$ in converter as the dissolved hydrogen content would not increase during the operation. The mechanism of bottom blown ${\mathrm{{CO}}}_{2}$ in the bath of combined blown converter was investigated in later stage (Guo & Chen,1993) by Chinese researchers and the industrial test of ${\mathrm{{CO}}}_{2}$ bottom blowing was carried out in a 180 t converter in Anshan Steel Plant (Li & Han, 1996). However, this technology could not be applied in the industry initially due to the short lifetime of the purge plug.
王(1986年、1989年)在1986 - 1989年期间对含${\mathrm{{CO}}}_{2}$气体的底吹进行了一系列研究。进行了高温实验,结果表明,在脱碳中期,采用${\mathrm{{CO}}}_{2}$底吹时,脱碳速率比其他气体大。其他地方也进行了类似的工作(原田等人,1986年;保尔斯,1987年),旨在研究底吹过程中${\mathrm{{CO}}}_{2}$的作用。这些研究结果表明,${\mathrm{{CO}}}_{2}$是${\mathrm{N}}_{2}/\mathrm{{Ar}}$底吹的有效替代方案,因为它不会增加钢液中的氮含量。这也是转炉中${\mathrm{O}}_{2}/{\mathrm{C}}_{x}{\mathrm{H}}_{y}$底吹的更优替代方案,因为在操作过程中溶解氢含量不会增加。中国研究人员在后期(郭 & 陈,1993年)研究了复吹转炉熔池中底吹${\mathrm{{CO}}}_{2}$的机理,并在鞍山钢铁厂的180吨转炉中进行了${\mathrm{{CO}}}_{2}$底吹的工业试验(李 & 韩,1996年)。然而,由于透气砖寿命短,这项技术最初无法在工业中应用。
During the experiment, it is found that the corrosion of the tuyere is severe just as Shanghai No. 1 steel’s practice (Jin, 1985). It was suggested that, during the progress of decarburization, the carbon content in the melt would be very low and, consequently, the carbon in refractory around tuyere will dissolve into the melt.
在实验过程中,发现风口腐蚀严重,就像上海第一钢铁厂的情况(金,1985年)一样。有人认为,在脱碳过程中,熔体中的碳含量会非常低,因此,风口周围耐火材料中的碳会溶解到熔体中。
Anshan Steel Plant carried out further research to solve the refractory problem and increase the lifetime of tuyere to 1500-2000 times of use. ${\mathrm{{CO}}}_{2}$ bottom blowing in converter had been used widely in this plant until the paper of (Li & Han,1996) was published. Sodium carbonate $\left( {{\mathrm{{Na}}}_{2}{\mathrm{{CO}}}_{3}}\right)$ solution absorption method was adopted by Anshan Steel Plant for ${\mathrm{{CO}}}_{2}$ production but the cost of ${\mathrm{{CO}}}_{2}$ preparation has not been reported.
鞍山钢铁厂进行了进一步研究以解决耐火材料问题,并将风口寿命提高到1500 - 2000次使用。在(李 & 韩,1996年)发表论文之前,转炉中的${\mathrm{{CO}}}_{2}$底吹在该厂已得到广泛应用。鞍山钢铁厂采用碳酸钠$\left( {{\mathrm{{Na}}}_{2}{\mathrm{{CO}}}_{3}}\right)$溶液吸收法生产${\mathrm{{CO}}}_{2}$,但${\mathrm{{CO}}}_{2}$制备成本未作报道。
Utilization of ${\mathrm{{CO}}}_{2}$ in metallurgical processes in China has been studied by Jin et al. (2007) and Yi et al. (2009). They started the work around 2004-2005 and named the new process the COMI $\left( {\mathrm{{CO}}}_{2}\right.$ and ${\mathrm{O}}_{2}$ Mixed Injection) process. In 2007, experimental study of steelmaking with ${\mathrm{{CO}}}_{2} - {\mathrm{O}}_{2}$ mixture was carried out by a ${10}\mathrm{\;{kg}}$ induction furnace, with the initial carbon content of around ${2.5}\mathrm{{wt}}\%$ . The result showed that it is feasible to decarburize the melt with ${\mathrm{{CO}}}_{2} - {\mathrm{O}}_{2}$ , and they pointed out that the maximum amount of ${\mathrm{{CO}}}_{2}$ introduction in converter is 13% (Jin et al., 2007).
金等人(2007年)和易等人(2009年)对中国冶金过程中${\mathrm{{CO}}}_{2}$的利用进行了研究。他们在2004 - 2005年左右开始这项工作,并将新工艺命名为COMI$\left( {\mathrm{{CO}}}_{2}\right.$和${\mathrm{O}}_{2}$混合喷吹)工艺。2007年,用${10}\mathrm{\;{kg}}$感应炉对初始碳含量约为${2.5}\mathrm{{wt}}\%$的${\mathrm{{CO}}}_{2} - {\mathrm{O}}_{2}$混合物炼钢进行了实验研究。结果表明,用${\mathrm{{CO}}}_{2} - {\mathrm{O}}_{2}$对熔体进行脱碳是可行的,他们指出转炉中${\mathrm{{CO}}}_{2}$的最大引入量为13%(金等人,2007年)。
The process was implemented in 2009 in industrial experiments (Yi et al., 2009) with ${\mathrm{{CO}}}_{2}$ addition ratio of around $7\%$ , and the results were very positive. The consumptions of lime, iron ore as well as oxygen with COMI process were all lower than that with conventional process. Additionally, the Total iron $\left( {\mathrm{T}}_{\mathrm{{Fe}}}\right)$ content in slag was decreased by 1.79 wt% compared to the conventional method.
该工艺于2009年在工业试验中实施(Yi等人,2009年),${\mathrm{{CO}}}_{2}$添加比例约为$7\%$,结果非常积极。与传统工艺相比,COMI工艺的石灰、铁矿石以及氧气消耗量均较低。此外,与传统方法相比,炉渣中的总铁$\left( {\mathrm{T}}_{\mathrm{{Fe}}}\right)$含量降低了1.79 wt%。
Dust Reduction
粉尘减排
One of the important achievements in Chinese research with regards to the benefit of using ${\mathrm{{CO}}}_{2}$ in the converter process is that it can reduce the generated amount of converter dust. The characteristics and mechanism of dust generation was also investigated by Bi et al. (2010). Both laboratory and industrial experiments have been carried out in China (Ning et al., 2009; Yin et al., 2009; Zhu et al., 2010) and the results showed that, with an increase in the ${\mathrm{{CO}}}_{2}$ ratio in the mixture gas, the dust generation is decreased.
中国在转炉工艺中使用${\mathrm{{CO}}}_{2}$的益处方面的重要研究成果之一是,它可以减少转炉粉尘的产生量。Bi等人(2010年)也对粉尘产生的特性和机理进行了研究。中国已经进行了实验室和工业实验(Ning等人,2009年;Yin等人,2009年;Zhu等人,2010年),结果表明,随着混合气体中${\mathrm{{CO}}}_{2}$比例的增加,粉尘产生量会减少。
Evaporation was considered as the main reason for fine (micro size) dust formation, which constitutes more than 60% of converter dust. The main content of the converter dust is ${\mathrm{{FeO}}}_{x}$ (around ${50}\%$ of total dust). With the oxygen injecting into hot metal, a fire zone forms with temperature higher than ${2500}{}^{ \circ }\mathrm{C}$ (maximum ${3000}{}^{ \circ }\mathrm{C}$ ). As the boiling point of iron is ${2750}{}^{ \circ }\mathrm{C}$ , iron will be oxidized and evaporate to form dust at lower temperatures. If one can decrease the temperature of the oxygen jet fire zone, dust generation is expected to decrease. Based on the endothermic nature of the Boudouard reaction, namely the reaction of ${\mathrm{{CO}}}_{2}$ and C, if ${\mathrm{{CO}}}_{2}$ is mixed with ${\mathrm{O}}_{2}$ to form the oxidizer gas mixture, the temperature of the fire zone will be lowered so as to decrease the oxidation evaporation of Fe.
蒸发被认为是细(微米级)粉尘形成的主要原因,细粉尘占转炉粉尘的60%以上。转炉粉尘的主要成分是${\mathrm{{FeO}}}_{x}$(约占总粉尘的${50}\%$)。随着氧气喷入铁水,会形成一个温度高于${2500}{}^{ \circ }\mathrm{C}$(最高${3000}{}^{ \circ }\mathrm{C}$)的火区。由于铁的沸点是${2750}{}^{ \circ }\mathrm{C}$,铁会在较低温度下被氧化并蒸发形成粉尘。如果能够降低氧气射流火区的温度,预计粉尘产生量会减少。基于布多尔反应的吸热性质,即${\mathrm{{CO}}}_{2}$与C的反应,如果将${\mathrm{{CO}}}_{2}$与${\mathrm{O}}_{2}$混合形成氧化剂气体混合物,火区的温度将会降低,从而减少铁的氧化蒸发。
The result obtained by Yin et al. (2009) has shown that, compared to the conventional steelmaking process, when ${\mathrm{{CO}}}_{2}$ volume ratio is $5\%$ , the dust amount is decreased by ${25}\%$ , while at the same time, the ${\mathrm{T}}_{\mathrm{{Fe}}}$ content in the dust is reduced by about 15.3 wt%.
Yin等人(2009年)得到的结果表明,与传统炼钢工艺相比,当${\mathrm{{CO}}}_{2}$体积比为$5\%$时,粉尘量减少了${25}\%$%,同时,粉尘中的${\mathrm{T}}_{\mathrm{{Fe}}}$含量降低了约15.3 wt%。
Dephosphorization
脱磷
The dephosphorization of BOF with the introduction of ${\mathrm{{CO}}}_{2}$ has been widely studied (Lv et al., ; Zhu et al., 2012). The dephosphorization of hot metal with high-Si and high-P in the converter is a serious technical problem during the steelmaking process. Normally, in order to enhance the dephosphorization efficiency, solid coolant is added during dephosphorization with the aim to control the temperature increase rate. However, solid coolant will lead to a partial-cooling of the bath. Consequently, the cooling effect would be non-uniform. Additionally, the impurity in solid coolant will affect the quality of steel production. In this case, ${\mathrm{{CO}}}_{2}$ could be a better choice as a temperature controlling agent. A ${30}\mathrm{t}$ converter was adopted for carrying out the ${\mathrm{{CO}}}_{2}$ cooling experiments (Yi et al.,2009).
转炉在引入${\mathrm{{CO}}}_{2}$的情况下进行脱磷已得到广泛研究(Lv等人,;Zhu等人,2012年)。在炼钢过程中,转炉内高硅高磷铁水的脱磷是一个严重的技术问题。通常,为了提高脱磷效率,在脱磷过程中会添加固体冷却剂,目的是控制温度上升速率。然而,固体冷却剂会导致熔池局部冷却。因此,冷却效果不均匀。此外,固体冷却剂中的杂质会影响钢的生产质量。在这种情况下,${\mathrm{{CO}}}_{2}$作为温度控制剂可能是更好的选择。采用了一个${30}\mathrm{t}$转炉进行${\mathrm{{CO}}}_{2}$冷却实验(Yi等人,2009年)。
The industrial trials showed that, with the introduction of ${\mathrm{{CO}}}_{2}$ (namely COMI process), the temperature of the dephosphorization period has been controlled better compared to the conventional process and ${\mathrm{{CO}}}_{2}$ bottom blowing is found to be beneficial for dephosphorization. The temperature of semisteel is around 1330- ${1350}^{ \circ }\mathrm{C}$ , and the phosphorous content in semisteel is lower than ${0.050}\mathrm{{wt}}\%$ . The average dephosphorization efficiency for semisteel using conventional processes is 53.10%, while it is 66.49% with COMI process. The P content for the first tapping is also decreased by ${23}\%$ , from 0.030 to 0.023 wt%.
工业试验表明,通过引入${\mathrm{{CO}}}_{2}$(即COMI工艺),与传统工艺相比,脱磷期的温度得到了更好的控制,并且发现${\mathrm{{CO}}}_{2}$底吹有利于脱磷。半钢温度在1330 - ${1350}^{ \circ }\mathrm{C}$左右,半钢中的磷含量低于${0.050}\mathrm{{wt}}\%$。使用传统工艺时半钢的平均脱磷效率为53.10%,而采用COMI工艺时为66.49%。第一次出钢时的磷含量也降低了${23}\%$,从0.030降至0.023 wt%。
To summarize the effects of ${\mathrm{{CO}}}_{2}$ used in converter process, the introduction of ${\mathrm{{CO}}}_{2}$ in the proper amount will be favourable to decarburization, dust reduction, reduction of materials consumption and dephosphorization. However, the amount or ratio of ${\mathrm{{CO}}}_{2}$ mixing must be calculated carefully, as too much ${\mathrm{{CO}}}_{2}$ can lead to skull of slag because of the endothermic reaction between ${\mathrm{{CO}}}_{2}$ and $\mathrm{C}$ .
总结转炉工艺中使用${\mathrm{{CO}}}_{2}$的效果,适量引入${\mathrm{{CO}}}_{2}$将有利于脱碳、降尘、降低材料消耗和脱磷。然而,${\mathrm{{CO}}}_{2}$的混合量或比例必须仔细计算,因为过多的${\mathrm{{CO}}}_{2}$会由于${\mathrm{{CO}}}_{2}$与$\mathrm{C}$之间的吸热反应导致炉渣结壳。
3.3.2 CO2 Used in AOD Process
3.3.2 AOD工艺中使用的二氧化碳
The application of ${\mathrm{{CO}}}_{2}$ in stainless steel making is extremely interesting. Currently, stainless steel is mostly produced through the argon oxygen decarburization (AOD) process. For ordinary stainless steel production, the Ar consumption is ${11} - {12}{\mathrm{\;m}}^{3}/\mathrm{t},{\mathrm{O}}^{2}$ consumption is ${14} - {24}{\mathrm{\;m}}^{3}/\mathrm{t}$ , while, $\operatorname{Ar}$ consumption is ${18} - {23}{\mathrm{\;m}}^{3}/\mathrm{t}$ in the case of smelting extra-low carbon stainless steel (Chen et al., 2008). It has economical profit if Ar could be replaced by cheaper gases, like ${\mathrm{N}}_{2}$ , steam, ${\mathrm{{CO}}}_{2}$ , etc. However, ${\mathrm{N}}_{2}$ will bring $\mathrm{N}$ and steam and will take $\mathrm{H}$ into the melt, both of which are harmful for certain steel grades. The use of ${\mathrm{{CO}}}_{2}$ could be ideal considering this aspect. The present authors have investigated the feasibility of ${\mathrm{{CO}}}_{2}$ application in the stainless steel making process, both in Sweden and in China.
${\mathrm{{CO}}}_{2}$在不锈钢制造中的应用极具吸引力。目前,不锈钢大多通过氩氧脱碳(AOD)工艺生产。对于普通不锈钢生产,氩气消耗为${11} - {12}{\mathrm{\;m}}^{3}/\mathrm{t},{\mathrm{O}}^{2}$,${14} - {24}{\mathrm{\;m}}^{3}/\mathrm{t}$消耗为${14} - {24}{\mathrm{\;m}}^{3}/\mathrm{t}$,而在冶炼超低碳不锈钢时,$\operatorname{Ar}$消耗为${18} - {23}{\mathrm{\;m}}^{3}/\mathrm{t}$(Chen等人,2008年)。如果能用更便宜的气体,如${\mathrm{N}}_{2}$、蒸汽、${\mathrm{{CO}}}_{2}$等替代氩气,将具有经济利润。然而,${\mathrm{N}}_{2}$会带来$\mathrm{N}$,蒸汽会将$\mathrm{H}$带入熔体,这两者对某些钢种都有害。从这方面考虑,使用${\mathrm{{CO}}}_{2}$可能是理想的。本文作者在瑞典和中国都研究了${\mathrm{{CO}}}_{2}$应用于不锈钢制造过程的可行性。
Wang et al. (2009, 2010) have carried out induction furnace experiments at the Royal Institute of Technology Sweden (KTH) during 2007-2010 and the results show that ${\mathrm{{CO}}}_{2}$ is effective for decarburization without the loss of chromium. After that, Zhu et al. (Li et al., 2015a) have carried out basic study of thermodynamics of ${\mathrm{{CO}}}_{2}$ applied for stainless steel smelting, and pointed out the maximum ${\mathrm{{CO}}}_{2}$ used in AOD process is ${9.13}\%$ . They stated that for carbon content over ${0.5}\mathrm{{wt}}\%$ , it is possible to use ${\mathrm{{CO}}}_{2} + {\mathrm{O}}_{2}$ mixture, while, at carbon level lower than ${0.5}\mathrm{{wt}}\%$ , it is better to use Ar to decrease partial pressure of $\mathrm{{CO}}\left( {\mathrm{P}}_{\mathrm{{CO}}}\right)$ . They also implemented experiments in China (Bi et al.,2012) and found when the ratio of ${\mathrm{{CO}}}_{2}$ increased from 0 to ${50}\%$ , the carbon content will decrease by ${12}\%$ while $\mathrm{{Cr}}$ content will increase by 19.93%. These authors have suggested the use of $5 - {11}{\mathrm{\;m}}^{3} \; {\mathrm{{CO}}}_{2}$ for one ton stainless steel production. The price of Ar is around 5-8 times that of ${\mathrm{{CO}}}_{2}$ . Consequently, the production cost will be decreased by 3-7 US$/t.
Wang等人(2009年、2010年)于2007 - 2010年期间在瑞典皇家理工学院(KTH)进行了感应炉实验,结果表明${\mathrm{{CO}}}_{2}$在不损失铬的情况下对脱碳有效。之后,Zhu等人(Li等人,2015a)对${\mathrm{{CO}}}_{2}$应用于不锈钢冶炼进行了热力学基础研究,并指出AOD工艺中使用的最大${\mathrm{{CO}}}_{2}$量为${9.13}\%$。他们指出,对于碳含量超过${0.5}\mathrm{{wt}}\%$的情况,可以使用${\mathrm{{CO}}}_{2} + {\mathrm{O}}_{2}$混合物,而在碳含量低于${0.5}\mathrm{{wt}}\%$时,最好使用氩气来降低$\mathrm{{CO}}\left( {\mathrm{P}}_{\mathrm{{CO}}}\right)$的分压。他们还在中国进行了实验(Bi等人,2012年),发现当${\mathrm{{CO}}}_{2}$的比例从0增加到${50}\%$时,碳含量将降低${12}\%$,而$\mathrm{{Cr}}$含量将增加19.93%。这些作者建议每吨不锈钢生产使用$5 - {11}{\mathrm{\;m}}^{3} \; {\mathrm{{CO}}}_{2}$。氩气价格约为${\mathrm{{CO}}}_{2}$的5 - 8倍。因此,生产成本将降低3 - 7美元/吨。
Anderson et al. (1990) have shown, from their corresponding trials at a steel plant in U.S. with production capacity of 1.0 million tonnes per year, that adopting a similar practice as proposed in Bi et al. (2012), 20 Million to 45 Million RMB could be saved per year. In 2011, Anshan Iron and Steel Co., Ltd. (Tang et al., 2011) invented an AOD process with injection of ${\mathrm{{CO}}}_{2}$ to produce stainless steel and they found it is suitable for smelting steel with carbon content from 0.001 to 0.3 wt% using the new process. They also found with ${\mathrm{{CO}}}_{2}$ injection, oxygen lance can be cooled and its life improved by ${20}\%$ .
Anderson等人(1990年)通过在美国一家年产100万吨的钢铁厂进行的相应试验表明,采用与Bi等人(2012年)类似的做法,每年可节省2000万至4500万元人民币。2011年,鞍山钢铁股份有限公司(Tang等人,2011年)发明了一种注入${\mathrm{{CO}}}_{2}$生产不锈钢的AOD工艺,他们发现该新工艺适用于冶炼碳含量为0.001至0.3 wt%的钢。他们还发现,注入${\mathrm{{CO}}}_{2}$后,氧枪可以冷却,其寿命提高${20}\%$。
3.3.3 CO2 Used in EAF Process
3.3.3 电弧炉工艺中使用的二氧化碳
Electric arc furnace (EAF) steel takes up around ${10.1}\%$ of the steel production in China in 2012, which is far lower than the international average and it is related to the lack of scrap and energy in China. However, with the development of the country, the ratio of scrap is expected to increase and the EAF process would be comparable to developed countries. The use of ${\mathrm{{CO}}}_{2}$ in EAF would have a great impact in future steel production in China. ${\mathrm{{CO}}}_{2}$ was introduced as the bottom blowing gas instead of Ar in the EAF process, in order to enhance the stirring ability of the bath for promoting the slag-metal reaction, homogenize the bath temperature and composition, and increase the yield of valuable metal (Gulyaev & Filippov, 2001; He et al., 1992; Van Wijngaar den & Pieterse, 1994; Zhao, 1995). The materials and heat balances were calculated by Wang et al. (2012) for the introduction of ${\mathrm{{CO}}}_{2}$ in EAF process with hot metal charging.
2012年,电弧炉(EAF)钢产量在中国钢铁总产量中占比约为${10.1}\%$,远低于国际平均水平,这与中国废钢和能源短缺有关。然而,随着国家的发展,废钢比例有望增加,电弧炉工艺将与发达国家相当。在电弧炉中使用${\mathrm{{CO}}}_{2}$将对中国未来的钢铁生产产生重大影响。在电弧炉工艺中引入${\mathrm{{CO}}}_{2}$作为底吹气体替代氩气,以增强熔池搅拌能力,促进渣 - 金属反应,使熔池温度和成分均匀化,并提高有价金属的产量(Gulyaev & Filippov,2001;He等人,1992;Van Wijngaar den & Pieterse,1994;Zhao,1995)。Wang等人(2012年)针对热装铁水的电弧炉工艺引入${\mathrm{{CO}}}_{2}$的情况进行了物料和热平衡计算。
These authors concluded that, with the ${\mathrm{{CO}}}_{2}$ addition in the oxidization gas, the hot metal ratio charged into EAF could be enhanced, resulting in energy savings. Recently, the industrial experiments for ${\mathrm{{CO}}}_{2}$ application in the EAF process were carried out in a 65t EAF with the product of 45# steel (Wang et al., 2014) compared to Ar bottom stirring. The results show that with ${\mathrm{{CO}}}_{2}$ bottom blowing, the stirring effect was reinforced and the FeO content in slag was lowered, which offers good desulphurization conditions. The desulphurization ratio could be increased by 7% compared to that with Ar bottom blowing. However, with ${\mathrm{{CO}}}_{2}$ bottom blowing, the end point carbon content will increase slightly, and a small amount of $\mathrm{{Cr}}$ will be oxidized because ${\mathrm{{CO}}}_{2}$ oxidizes $\mathrm{{Cr}}$ in the melt, while Ar has no effect on $\mathrm{{Cr}}$ oxidation.
这些作者得出结论,在氧化气体中添加${\mathrm{{CO}}}_{2}$,可提高装入电弧炉的铁水比例,从而实现节能。最近,在一座65吨电弧炉中进行了电弧炉工艺应用${\mathrm{{CO}}}_{2}$的工业试验,生产45#钢(Wang等人,2014年),并与氩气底吹搅拌进行了对比。结果表明,采用${\mathrm{{CO}}}_{2}$底吹时,搅拌效果增强,炉渣中FeO含量降低,提供了良好的脱硫条件。与氩气底吹相比,脱硫率可提高7%。然而,采用${\mathrm{{CO}}}_{2}$底吹时,终点碳含量会略有增加,并且会有少量$\mathrm{{Cr}}$被氧化,因为${\mathrm{{CO}}}_{2}$会在熔体中氧化$\mathrm{{Cr}}$,而氩气对$\mathrm{{Cr}}$的氧化没有影响。
To conclude, with ${\mathrm{{CO}}}_{2}$ bottom blowing in EAF instead of $\mathrm{{Ar}}$ , the production cost will be decreased because the expensive Ar is replaced and the quality of the steel will not be affected, even enhanced at times.
总之,在电弧炉中采用${\mathrm{{CO}}}_{2}$底吹替代$\mathrm{{Ar}}$,生产成本将降低,因为昂贵的氩气被替代,而且钢的质量不会受到影响,甚至有时还会得到提高。
3.3.4 ${\mathrm{{CO}}}_{2}$ Used in Secondary Refining Process
3.3.4 ${\mathrm{{CO}}}_{2}$在二次精炼过程中的应用
The use of ${\mathrm{{CO}}}_{2}$ as protection gas in a ladle furnace (LF) during heating can be traced back to 1986, with the aim to form a ${\mathrm{{CO}}}_{2}$ gas layer. This could reduce the possibility of steel melt absorbing nitrogen as well as re-oxidation. American and French plants have applied this technology successfully to decease the N content in the liquid steel by 63-75% (Hara et al., 1986). The research work by Bruce et al. (1987a) suggested that the quality of molten steel is not affected by bottom blowing ${\mathrm{{CO}}}_{2}$ in LF operation.
${\mathrm{{CO}}}_{2}$在钢包精炼炉(LF)加热过程中用作保护气体可追溯到1986年,目的是形成一层${\mathrm{{CO}}}_{2}$气体层。这可以降低钢水吸收氮以及再氧化的可能性。美国和法国的工厂已成功应用该技术,将钢液中的氮含量降低了63 - 75%(原田等人,1986年)。布鲁斯等人(1987a)的研究工作表明,在LF操作中底吹${\mathrm{{CO}}}_{2}$不会影响钢水质量。
Unfortunately, because of weak oxidation of ${\mathrm{{CO}}}_{2}$ , few researches are focused on applying ${\mathrm{{CO}}}_{2}$ as a bottom stirring gas in LF operation. Because of this background, the current group, Gu et al. (2014) and Dong et al. (2014) have studied the ${\mathrm{{CO}}}_{2}$ application in LF both experimentally and theoretically. The experiments were performed in a 70 ton LF with ${\mathrm{{CO}}}_{2}$ as bottom blowing gas for 45# grade steel production. The results showed that neither types nor compositions of inclusions have significantly changed in steel compared with bottom blowing Ar.
不幸的是,由于${\mathrm{{CO}}}_{2}$的弱氧化性,很少有研究关注在LF操作中将${\mathrm{{CO}}}_{2}$用作底吹搅拌气体。基于此背景,当前的研究团队,顾等人(2014年)和董等人(2014年)对${\mathrm{{CO}}}_{2}$在LF中的应用进行了实验和理论研究。实验在一座70吨的LF中进行,以${\mathrm{{CO}}}_{2}$作为底吹气体生产45#钢。结果表明,与底吹氩气相比,钢中夹杂物的类型和成分均无显著变化。
On the other hand, it is observed that the process decreases inclusion yield density and improves steel cleanness. But one should also take note of the fact that ${\mathrm{{CO}}}_{2}$ is a weak oxidizer, and its use may lead to the increase of oxygen content in the liquid steel. A slight increase of oxygen in steel has been observed by Gu et al. (2014) and Dong et al. (2014) when blowing $1/3$ and $2/3{\mathrm{{CO}}}_{2}$ compared with pure Ar blowing.
另一方面,观察到该过程降低了夹杂物的产生密度并提高了钢的纯净度。但还应注意到${\mathrm{{CO}}}_{2}$是一种弱氧化剂,其使用可能导致钢液中氧含量增加。顾等人(2014年)和董等人(2014年)发现,与纯氩气底吹相比,吹入$1/3$和$2/3{\mathrm{{CO}}}_{2}$时钢中的氧含量略有增加。
Further evidence is obtained by experiments conducted by Paules et al. (1987) and Bruce et al. (1987b), who demonstrated that, when the carbon content is less than ${0.20}\mathrm{{wt}}\%$ in the melt, the dissolved oxygen in liquid steel is higher with ${\mathrm{{CO}}}_{2}$ stirring than with Ar stirring, but for steel grades with higher carbon content, there is no difference of dissolved oxygen content by blowing these two gases.
保尔斯等人(1987年)和布鲁斯等人(1987b)进行的实验进一步证明,当熔体中的碳含量低于${0.20}\mathrm{{wt}}\%$时,用${\mathrm{{CO}}}_{2}$搅拌时钢液中的溶解氧高于用氩气搅拌时的情况,但对于碳含量较高的钢种,吹入这两种气体时溶解氧含量没有差异。
3.4 CO2 Used in Continuous Casting Process
3.4 连铸过程中使用的二氧化碳
${\mathrm{{CO}}}_{2}$ was applied in casting as shield gas, replacing Ar for special steel rod production in America 1989 (Anderson et al., 1989). Almost at the same period, researchers from UK (Normanton & Wang 1990) also tested the utilization of ${\mathrm{{CO}}}_{2}$ on ladle slide gate as shield gas during 1986-1988. The conclusion from these experiences was that, with the protection of ${\mathrm{{CO}}}_{2}$ , the steel quality was similar to that when $\mathrm{{Ar}}$ is used. The utilization of ${\mathrm{{CO}}}_{2}$ in the casting process came into popularity rather late in China. Until 2015, Li et al. (2015b) have carried out the industrial experiments on ${\mathrm{{CO}}}_{2}$ applied as a protective gas during continuous casting process instead of $\mathrm{{Ar}}/{\mathrm{N}}_{2}$ .
${\mathrm{{CO}}}_{2}$于1989年在美国被用作铸造中的保护气体,替代氩气用于特殊钢棒材生产(Anderson等人,1989年)。几乎在同一时期,英国的研究人员(Normanton和Wang,1990年)也在1986 - 1988年期间测试了${\mathrm{{CO}}}_{2}$在钢包滑动水口作为保护气体的应用。这些经验得出的结论是,在${\mathrm{{CO}}}_{2}$的保护下,钢的质量与使用$\mathrm{{Ar}}$时相似。${\mathrm{{CO}}}_{2}$在铸造过程中的应用在中国普及得相当晚。直到2015年,Li等人(2015b)才进行了${\mathrm{{CO}}}_{2}$作为连铸过程中的保护气体替代$\mathrm{{Ar}}/{\mathrm{N}}_{2}$的工业试验。
When ${\mathrm{{CO}}}_{2}$ is used as stirring gas or shielding gas for production, the quality of steel is similar or even the same to that using Ar gas. The nitrogen content in the melt is slightly lower with ${\mathrm{{CO}}}_{2}$ blowing than with Ar blowing since 1 volume ${\mathrm{{CO}}}_{2}$ reacting with $\mathrm{C}$ will generate 2 volumes of $\mathrm{{CO}}$ and large amounts of gas benefit from removing nitrogen. The oxygen content, hydrogen content and the content of oxide inclusions in the liquid steel are comparable with that stirred by Ar.
当${\mathrm{{CO}}}_{2}$用作生产的搅拌气体或保护气体时,钢的质量与使用氩气时相似甚至相同。由于1体积的${\mathrm{{CO}}}_{2}$与$\mathrm{C}$反应会生成2体积的$\mathrm{{CO}}$,且大量气体有助于去除氮气,因此用${\mathrm{{CO}}}_{2}$吹气时熔体中的氮含量比用氩气吹气时略低。钢液中的氧含量、氢含量和氧化物夹杂物含量与用氩气搅拌时相当。
3.5 CO2 Used in Ferroalloy Production
3.5 用于铁合金生产的二氧化碳
Converter refining for ferrochrome (FeCr) and ferro manganese (FeMn) production is the trend of medium and low carbon (MLC) product smelting in China. Because the submerged arc furnace used for high carbon ferroalloy production is getting larger in size and the tapping size is very large. The conventional way for medium and low carbon ferroalloy production is not suitable because of its limited size and very high energy consumption. But the current converter technology used for M-LCFeCr and M-LCFeMn production has defects of a short lifetime of linings and low yield of $\mathrm{{Cr}}/\mathrm{{Mn}}$ . In this case, current authors (Yu, 2015; Yu et al.,2015) introduced ${\mathrm{{CO}}}_{2}$ into the converter process for M-LCFeCr and M-LCFeMn production. Laboratory scale experiments show that it is feasible to use ${\mathrm{{CO}}}_{2}$ for producing these two alloys and it can enhance the yield of $\mathrm{{Cr}}/\mathrm{{Mn}}$ by using ${\mathrm{{CO}}}_{2} + {\mathrm{O}}_{2}$ mixtures, especially when the carbon content in product is higher than 3.0wt%. However, calculations indicate that it is not beneficial to produce ferrochrome with carbon content lower than 1.0wt% with the introduction of ${\mathrm{{CO}}}_{2}$ .
在中国,用于生产铬铁(FeCr)和锰铁(FeMn)的转炉精炼是中低碳(MLC)产品冶炼的趋势。因为用于生产高碳铁合金的矿热炉尺寸越来越大,出钢量也非常大。由于其尺寸有限且能耗极高,传统的中低碳铁合金生产方式并不适用。但是,目前用于生产中低碳铬铁和中低碳锰铁的转炉技术存在炉衬寿命短和$\mathrm{{Cr}}/\mathrm{{Mn}}$产量低的缺陷。在这种情况下,当前作者(Yu,2015;Yu等人,2015)将${\mathrm{{CO}}}_{2}$引入到中低碳铬铁和中低碳锰铁生产的转炉工艺中。实验室规模的实验表明,使用${\mathrm{{CO}}}_{2}$生产这两种合金是可行的,并且通过使用${\mathrm{{CO}}}_{2} + {\mathrm{O}}_{2}$混合物可以提高$\mathrm{{Cr}}/\mathrm{{Mn}}$的产量,特别是当产品中的碳含量高于3.0wt%时。然而,计算表明,引入${\mathrm{{CO}}}_{2}$生产碳含量低于1.0wt%的铬铁并不有利。
Additionally, the refining of silicon and ferrosilicon with the outfurnace method has also considered using ${\mathrm{{CO}}}_{2}$ as a medium; the results, however, are not very encouraging (Suzuki et al., 1992; Wu et al., 2009, 2014) and would require further study.
此外,采用炉外法精炼硅和硅铁时也考虑使用${\mathrm{{CO}}}_{2}$作为介质;然而,结果并不十分理想(Suzuki等人,1992;Wu等人,2009,2014),需要进一步研究。
3.6 CO2 Used in Other Areas in Steel Process
3.6 二氧化碳在钢铁生产其他领域的应用
${\mathrm{{CO}}}_{2}$ was also used as the protection media, as a substitute for hydrocarbon, for side-blown oxygen lance in a converter to successfully limit dissolved hydrogen in liquid steel (Liu, 1983). As an acidic gas, ${\mathrm{{CO}}}_{2}$ could also be used to fix active basic substances in slag to get stable carbonate. Dong (2008) have used ${\mathrm{{CO}}}_{2}$ to stabilize the converter slag and found that the best reaction temperature was ${700}{}^{ \circ }\mathrm{C}$ . Slag splashing in a converter is widely used in China and ${\mathrm{{CO}}}_{2}$ is being tested as a replacement for ${\mathrm{N}}_{2}$ by researchers at the Chinese Academy of Sciences (Yuan et al., 2007; Zhao et al., 2010). During these trials with slag splashing, coke fines or pulverized coal with additives were added into the converter. The basic idea was that ${\mathrm{{CO}}}_{2}$ would react with $\mathrm{C}$ to form $\mathrm{{CO}}$ . In this case, $\mathrm{{CO}} + {\mathrm{{CO}}}_{2}$ mixed gas will be recycled using this process. After separation, the ${\mathrm{{CO}}}_{2}$ could be utilized for slag splashing again, while CO could be reused in other places in plant.
${\mathrm{{CO}}}_{2}$ 还被用作保护介质,替代碳氢化合物,用于转炉的侧吹氧枪,成功限制了钢液中的溶解氢(Liu,1983年)。作为一种酸性气体,${\mathrm{{CO}}}_{2}$ 还可用于固定炉渣中的活性碱性物质,以获得稳定的碳酸盐。董(2008年)使用 ${\mathrm{{CO}}}_{2}$ 来稳定转炉炉渣,发现最佳反应温度为 ${700}{}^{ \circ }\mathrm{C}$ 。转炉溅渣护炉在中国广泛应用,中国科学院的研究人员正在测试用 ${\mathrm{{CO}}}_{2}$ 替代 ${\mathrm{N}}_{2}$ (Yuan等人,2007年;Zhao等人,2010年)。在这些溅渣试验中,将焦粉或添加添加剂的煤粉加入转炉。基本思路是 ${\mathrm{{CO}}}_{2}$ 会与 $\mathrm{C}$ 反应生成 $\mathrm{{CO}}$ 。在这种情况下,$\mathrm{{CO}} + {\mathrm{{CO}}}_{2}$ 混合气体将通过此工艺循环利用。分离后,${\mathrm{{CO}}}_{2}$ 可再次用于溅渣,而CO可在工厂其他地方再利用。
3.7 CO2 Used in Microalgae Cultivation
3.7 微藻培养中使用的二氧化碳
${\mathrm{{CO}}}_{2}$ used in microalgae cultivation is another promising way of sequestering ${\mathrm{{CO}}}_{2}$ . On one hand, microalgae could fix carbon in a very efficient way with zero carbon emissions. On the other hand, it helps to realize the transformation of solar energy to biomass energy. Microalgae has broad applications. It can be used to produce biodiesel which has many advantages over traditional fuels. Advantages include better combustion and safety behavior, and higher environmental performance. Another microalgae application is in food industry. Microalgae is used to produce products with high industrial added value, like docosahexaenoic acid and eicosapentaenoic acid.
${\mathrm{{CO}}}_{2}$用于微藻培养是另一种很有前景的${\mathrm{{CO}}}_{2}$封存方式。一方面,微藻能够以非常高效的方式固定碳,且零碳排放。另一方面,它有助于实现太阳能向生物质能的转化。微藻有广泛的应用。它可用于生产生物柴油,与传统燃料相比有许多优势。优势包括更好的燃烧和安全性能,以及更高的环境性能。微藻的另一个应用领域是食品工业。微藻用于生产具有高工业附加值的产品,如二十二碳六烯酸和二十碳五烯酸。
Biofuels and methanol, which are emerging class of carbon-neutral drop-in replacement fuels, offer strongly viable alternatives for providing carbon neutral fuels to large and very large vessels. At the moment, through biotechnology utilization creates a carbon neutral loop as the ${\mathrm{{CO}}}_{2}$ released from burning the biofuels and methanol are captured and offset from industrial activities in the production of biofuels and methanol. Energy need for the reaction is in the renewable form. Utilization biological carbon capture there will convert ${70},{000}\mathrm{t}$ per year of ${\mathrm{{CO}}}_{2}$ into 50,000 t per year of methanol (ADB, 2020).
生物燃料和甲醇是新兴的碳中和直接替代燃料,为大型和超大型船舶提供碳中和燃料提供了极具可行性的替代方案。目前,通过生物技术利用形成了一个碳中和循环,因为燃烧生物燃料和甲醇释放的${\mathrm{{CO}}}_{2}$被捕获,并从生物燃料和甲醇生产中的工业活动中抵消。反应所需的能量是可再生形式。利用生物碳捕获每年将${70},{000}\mathrm{t}$的${\mathrm{{CO}}}_{2}$转化为每年50,000吨甲醇(亚洲开发银行,2020年)。
The broad geographical distribution of microalgae and its extraordinary environmental tolerance make large-scale microalgae cultivation possible. China is the biggest microalgae breeding country worldwide and has great potential for microalgae development. Therefore, microalgae technology should be perceived as an important development direction of carbon fixation and should receive more attention. Currently, technical challenges include the low quality of microalgae, less efficiency of large-scale cultivation, and high energy cost.
微藻广泛的地理分布及其非凡的环境耐受性使得大规模微藻培养成为可能。中国是全球最大的微藻养殖国家,微藻发展潜力巨大。因此,微藻技术应被视为碳固定的一个重要发展方向,应受到更多关注。目前,技术挑战包括微藻质量低、大规模培养效率低和能源成本高。
3.8 Econic Catalyst Technology for Utilization of Carbon Dioxide as a Feedstock for the Polyurethane Industry
3.8 用于将二氧化碳用作聚氨酯工业原料的Econic催化技术
The proprietary catalyst technology of Econic allows for recycled carbon dioxide $\left( {\mathrm{{CO}}}_{2}\right)$ emissions to be used as a feedstock in polyol manufacture. In the frst market application, recycled ${\mathrm{{CO}}}_{2}$ is incorporated into a range of polyols-the building blocks of polyurethanes-substituting up to ${50}\%$ of the conventional fossil-based feedstocks, propylene oxide and/or ethylene oxide. Econic technology produces polyols with tunable amounts of incorporated ${\mathrm{{CO}}}_{2}$ , which have enhanced performances that are tailored for specifc applications. Beyond polyols,
Econic的专利催化技术允许将回收的二氧化碳$\left( {\mathrm{{CO}}}_{2}\right)$排放物用作多元醇生产的原料。在首个市场应用中,回收的${\mathrm{{CO}}}_{2}$被纳入一系列多元醇中——聚氨酯的基础成分——替代高达${50}\%$的传统化石基原料环氧丙烷和/或环氧乙烷。Econic技术生产的多元醇中所含${\mathrm{{CO}}}_{2}$的量可调节,具有针对特定应用量身定制的增强性能。除了多元醇之外,
Econic technology has been proven to deliver the same ${\mathrm{{CO}}}_{2}$ benefts in the surfactant, lubricant, and high molecular weight polymer sectors. Its frst target market is in the manufacture of polyols, the building blocks of polyurethane materials. Life-cycle assessment studies indicate that polyols produced with average ${\mathrm{{CO}}}_{2}$ contents $\left( {{25}\% - {35}\% }\right)$ will have reduced ${\mathrm{{CO}}}_{2}$ emissions footprints in the order of 25-40%. Across the global polyurethanes market, a 30% adoption of Econic catalyst technology could result in the consumption and prevention of 5 million tonnes per annum of ${\mathrm{{CO}}}_{2}$ emissions. Polyols created by the Econic system can be utilized in all aspects of the polyurethane market, from housing insulation to car interiors to running shoes and refrigerators. The Econic system incorporates ${\mathrm{{CO}}}_{2}$ into polyols using less energy than the existing industrial process, and-compared to competing technologies-is the only system that facilitates bespoke incorporation of ${\mathrm{{CO}}}_{2}$ into products, thereby optimizing production and end-product performance. Furthermore, it does so under the same equipment and processing conditions of existing production facilities, allowing fast, simple, and low-cost adoption by retrofit.
Econic技术已被证明在表面活性剂、润滑剂和高分子量聚合物领域能带来相同的${\mathrm{{CO}}}_{2}$益处。其首个目标市场是聚氨酯材料基础成分多元醇的生产。生命周期评估研究表明,平均${\mathrm{{CO}}}_{2}$含量为$\left( {{25}\% - {35}\% }\right)$的多元醇生产的${\mathrm{{CO}}}_{2}$排放量足迹将减少25 - 40%。在全球聚氨酯市场中,采用30%的Econic催化技术每年可消耗和防止500万吨${\mathrm{{CO}}}_{2}$排放。Econic系统生产的多元醇可用于聚氨酯市场的各个方面,从房屋隔热到汽车内饰,再到跑鞋和冰箱。Econic系统将${\mathrm{{CO}}}_{2}$纳入多元醇所使用的能源比现有工业工艺少;与竞争技术相比,它是唯一能将${\mathrm{{CO}}}_{2}$定制纳入产品的系统,从而优化生产和最终产品性能。此外,它在现有生产设施的相同设备和加工条件下就能做到这一点,通过改造实现快速、简单且低成本的采用。
Beyond polyols, the same utilization of ${\mathrm{{CO}}}_{2}$ has been demonstrated in the surfactant, lubricant, and high molecular weight polymer sectors, dramatically increasing the scale of carbon beneft the Econic technology can deliver.
除了多元醇之外,在表面活性剂、润滑剂和高分子量聚合物领域也证明了对${\mathrm{{CO}}}_{2}$的相同利用,极大地扩大了Econic技术所能带来的碳效益规模。
3.9 Carbon Utilization Recommendation
3.9 碳利用建议
Significant research efforts have been made on ${\mathrm{{CO}}}_{2}$ used as stirring gas, reacting medium as well as protecting source in metallurgical processes. This covers almost all the fields of ferrous metallurgy. In most cases, positive results are obtained through observation. However, despite the positive impacts, the negative effects of ${\mathrm{{CO}}}_{2}$ also need to be considered. For example, when it is used in converter and EAF processes, it may prolong the tap-to-tap time hence increase the production cost somehow, and it is difficult to decide the proper introduction amount. While, when it is used in LF (ladle furnace) and CC (continuous casting) processes, it may lead to re-oxidation of the melt for clean steel production.
在冶金过程中,人们对将${\mathrm{{CO}}}_{2}$用作搅拌气体、反应介质以及保护气源进行了大量的研究工作。这几乎涵盖了黑色冶金的所有领域。在大多数情况下,通过观察获得了积极的结果。然而,尽管有积极影响,但${\mathrm{{CO}}}_{2}$的负面影响也需要考虑。例如,当它用于转炉和电弧炉工艺时,可能会延长冶炼周期,从而在一定程度上增加生产成本,并且难以确定合适的引入量。而当它用于LF(钢包精炼炉)和CC(连铸)工艺时,可能会导致钢水再氧化,不利于生产纯净钢。
Till now, the experiments on application of ${\mathrm{{CO}}}_{2}$ in the metallurgical processes in China are limited to laboratory scale and pilot scale. The lack of enthusiasm in industrial implementation could be attributed to (1) method of ${\mathrm{{CO}}}_{2}$ preparation leads to the cost of ${\mathrm{{CO}}}_{2}$ currently is not low, and it is not economical to use ${\mathrm{{CO}}}_{2}$ ; (2) there is lack of sufficient research results with regard to the optimal amount of ${\mathrm{{CO}}}_{2}$ to be used. These problems need to be solved by researchers as soon as possible. Recently, the new methods for ${\mathrm{{CO}}}_{2}$ separation from the flue gas in steel industry reported by researchers from South Korea (Kim et al., 2015) provided an economic solution of ${\mathrm{{CO}}}_{2}$ preparation (62 USD/t ${\mathrm{{CO}}}_{2}$ separated), which will make ${\mathrm{{CO}}}_{2}$ cyclic utilization in the metallurgical processes closer to the industrial production.
到目前为止,中国在冶金过程中应用${\mathrm{{CO}}}_{2}$的实验仅限于实验室规模和中试规模。工业实施缺乏积极性可能归因于:(1)${\mathrm{{CO}}}_{2}$的制备方法导致目前${\mathrm{{CO}}}_{2}$的成本不低,使用${\mathrm{{CO}}}_{2}$不经济;(2)关于${\mathrm{{CO}}}_{2}$的最佳使用量缺乏足够的研究成果。这些问题需要研究人员尽快解决。最近,韩国研究人员(Kim等人,2015年)报道的从钢铁行业烟气中分离${\mathrm{{CO}}}_{2}$的新方法提供了一种经济的${\mathrm{{CO}}}_{2}$制备方案(分离出的${\mathrm{{CO}}}_{2}$成本为62美元/吨),这将使${\mathrm{{CO}}}_{2}$在冶金过程中的循环利用更接近工业生产。
4 Review of Appropriate CO2 Transport and Storage Options
4 合适的二氧化碳运输与封存选项综述
4.1 Options for ${\mathrm{{CO}}}_{2}$ Transport
4.1 ${\mathrm{{CO}}}_{2}$运输的选项
Generally, a CCS system has three separate elements: capture, transport and storage. As the intermediate process in the CCS chain, ${\mathrm{{CO}}}_{2}$ transport is needed to link ${\mathrm{{CO}}}_{2}$ sources and storage sites and thus plays a significant role in the successful deployment of CCS. Hence, it is important to have a thorough consideration of ${\mathrm{{CO}}}_{2}$ transportation approaches and corresponding cost. However, transport is considered as the least challenging element of CCS and has been less studied (Aspelund & Jordal, 2007).
一般来说,碳捕集与封存(CCS)系统有三个独立的环节:捕集、运输和封存。作为CCS链条中的中间环节,${\mathrm{{CO}}}_{2}$运输需要连接${\mathrm{{CO}}}_{2}$源和封存地点,因此在CCS的成功部署中发挥着重要作用。因此,全面考虑${\mathrm{{CO}}}_{2}$运输方式及其相应成本非常重要。然而,运输被认为是CCS中最不具挑战性的环节,相关研究较少(阿斯佩伦德和乔达尔,2007年)。
In industry, ${\mathrm{{CO}}}_{2}$ is transported by pipelines, ships, railway tankers, and tanker trucks. Svensson et al. (2004) performed an economic analysis on these four alternatives and concluded that water carriers (offshore), pipelines (offshore and onshore) and a combination of these are appropriate transport options for CCS. Figure 2 shows the cost and capacity for transportation alternatives at a distance of ${250}\mathrm{\;{km}}$ . It clearly shows that pipeline and water carriers have a large capacity and low cost. Nevertheless, other options still have the potential to be applied to small-scale CCS projects. For example, Yanchang integrated a CCS demonstration project in China that adopts tanker trucks and pipelines as its ${\mathrm{{CO}}}_{2}$ transport method (GCCSI, 2017a). For large-scale CCS projects, due to the low capacity and high transportation fares, railway tankers and tanker trucks are not cost effective. Therefore, this portion of the review will focus on pipeline and shipment transport and gives a brief introduction of transport technology as well as cost analysis.
在工业中,${\mathrm{{CO}}}_{2}$通过管道、船舶、铁路油罐车和油罐车进行运输。斯文森等人(2004年)对这四种运输方式进行了经济分析,得出水运(海上)、管道(海上和陆上)以及两者结合是CCS合适的运输选择。图2显示了距离为${250}\mathrm{\;{km}}$时各种运输方式的成本和运输能力。该图清楚地表明,管道和水运具有运输能力大、成本低的特点。尽管如此,其他运输方式仍有可能应用于小规模的CCS项目。例如,中国延长石油集成了一个CCS示范项目,该项目采用油罐车和管道作为其${\mathrm{{CO}}}_{2}$运输方式(全球碳捕集与封存研究院,2017年a)。对于大规模的CCS项目,由于运输能力低和运输费用高,铁路油罐车和油罐车在成本效益方面并不理想。因此,本综述的这一部分将重点关注管道运输和船舶运输,并简要介绍运输技术以及成本分析。
Fig. 2 Cost and capacity for transportation alternatives at ${250}\mathrm{\;{km}}$ (Svensson et al., 2004)
图2 ${250}\mathrm{\;{km}}$运输方式的成本和运输能力(斯文森等人,2004年)
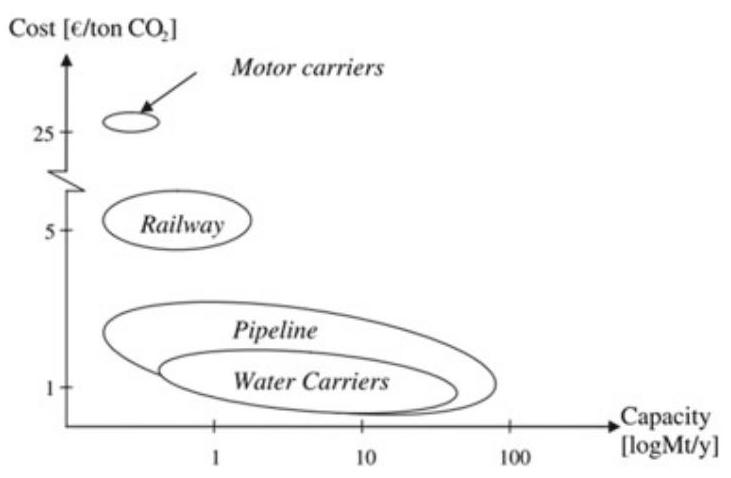
4.1.1 ${\mathrm{{CO}}}_{2}$ Pipeline Transport
4.1.1 ${\mathrm{{CO}}}_{2}$管道运输
The use of ${\mathrm{{CO}}}_{2}$ pipelines is well established to be the most economical way of transporting ${\mathrm{{CO}}}_{2}$ (Zhang et al.,2006). At present,14 of 16 global large-scale CCS projects use pipeline transport (Table 1). Carbon dioxide pipelines have extended over ${2500}\mathrm{\;{km}}$ in the western areas of United States, where they transport more than 50 million tonnes of ${\mathrm{{CO}}}_{2}$ per year from natural ${\mathrm{{CO}}}_{2}$ sources to enhanced oil recovery sites. By far, many problems associated with carbon dioxide pipelines are similar with those encountered by hydrocarbon pipelines in similar areas. Therefore, lots of learning and knowledge from the use of hydrocarbon pipelines, i.e. system design, construction, risk monitoring, can be borrowed to develop pipelines for ${\mathrm{{CO}}}_{2}$ transport.
使用${\mathrm{{CO}}}_{2}$管道是公认的运输${\mathrm{{CO}}}_{2}$最经济的方式(Zhang等人,2006年)。目前,全球16个大型CCS项目中有14个使用管道运输(表1)。二氧化碳管道在美国西部地区的延伸长度超过${2500}\mathrm{\;{km}}$,每年从天然${\mathrm{{CO}}}_{2}$源向强化采油场地运输超过5000万吨${\mathrm{{CO}}}_{2}$。到目前为止,与二氧化碳管道相关的许多问题与类似地区的烃类管道所遇到的问题相似。因此,可以借鉴许多烃类管道使用方面的经验和知识,即系统设计、建设、风险监测,来开发用于${\mathrm{{CO}}}_{2}$运输的管道。
Transport Technology and System Design
运输技术与系统设计
Broadly speaking, the ${\mathrm{{CO}}}_{2}$ pipeline transport chain includes gas conditioning, compression and pipeline transport (Fig. 3). Gas conditioning means the necessary processing of ${\mathrm{{CO}}}_{2}$ to achieve transport specification. Normally, it includes two steps: removing water and other liquids and then removing volatile gases. Liquids should be ensured not to enter ${\mathrm{{CO}}}_{2}$ compressors so that the formation of gas hydrates, the freezing of water and corrosion can be avoided. Transportation of volatile gases, like nitrogen, would increase the energy requirement and cost. Gas conditioning is often recognized as the interface between ${\mathrm{{CO}}}_{2}$ capture and transport.
一般来说,${\mathrm{{CO}}}_{2}$管道运输链包括气体调节、压缩和管道运输(图3)。气体调节是指对${\mathrm{{CO}}}_{2}$进行必要的处理以达到运输规格。通常,它包括两个步骤:去除水和其他液体,然后去除挥发性气体。应确保液体不会进入${\mathrm{{CO}}}_{2}$压缩机,以避免形成气体水合物、水的冻结和腐蚀。像氮气这样的挥发性气体的运输会增加能源需求和成本。气体调节通常被认为是${\mathrm{{CO}}}_{2}$捕集与运输之间的接口。
The most economical way of transporting ${\mathrm{{CO}}}_{2}$ is as a dense phase (Van-deginste & Piessens, 2008). The dense phase pipeline was 20% cheaper than a low-pressure ${\mathrm{{CO}}}_{2}$ gas pipeline. Generally, the pressure should be kept above 9.6 MPa to remain in a dense phase state no matter the temperature change. In addition, high pressure ${\mathrm{{CO}}}_{2}$ is advantageous in the injection process. Compressors not only offer the pressure at the starting point, but also operate at some points along the pipeline, at areas called booster stations, to overcome the pressure loss caused by friction. These stations are not necessarily equally spaced. When pipeline length is short, they may lack compressor stations.
运输${\mathrm{{CO}}}_{2}$最经济的方式是采用密相运输(Van-deginste & Piessens,2008年)。密相管道比低压${\mathrm{{CO}}}_{2}$气体管道便宜20%。一般来说,无论温度如何变化,压力应保持在9.6兆帕以上以保持密相状态。此外,高压${\mathrm{{CO}}}_{2}$在注入过程中具有优势。压缩机不仅在起点提供压力,还在管道沿线的某些点,即在称为增压站的区域运行,以克服摩擦引起的压力损失。这些站点不一定等距分布。当管道长度较短时,可能没有压缩机站。
Table 1 Transportation of global large-scale CCS project in operation. Adapted from GCCSI (2017b)
表1全球运行中的大型CCS项目运输情况。改编自GCCSI(2017b)
| Project name | Capacity (Mtpa) | Operation date | Transport type | Length (km) |
| Val Verde Natural Gas Plants | 1.3 | 1972 | Pipeline | 316 |
| Enid Fertilizer ${\mathrm{{CO}}}_{2}$ -EOR Project | 0.7 | 1982 | Pipeline | 225 |
| Shute Creek Gas Processing Facility | 7.0 | 1986 | Pipeline | Multiple, maximum of 460 km |
| Sleipner ${\mathrm{{CO}}}_{2}$ Storage Project | 0.85 | 1996 | N/A | Not applicable |
| Great Plains Synfuel Plant and Weyburn-Midale Project | 3.0 | 2000 | Pipeline | 329 |
| Snohvit CO2 Storage Project | 0.7 | 2008 | Pipeline | 153 |
| Century Plant | 8.4 | 2010 | Pipeline | 64 to 240 |
| Air Products Steam Methane Reformer EOR Project | 1.0 | 2013 | Pipeline | 158 |
| Coffeyville Gasification Plant | 1.0 | 2013 | Pipeline | 112 |
| Lost Cabin Gas Plant | 0.9 | 2013 | Pipeline | 374 |
| Petrobras Santos Basin Pre-Salt Oil Field CCS Project | Approx. 1.0 | 2013 | N/A | Not applicable |
| Boundary Dam Carbon Capture and Storage Project | 1.0 | 2014 | Pipeline | 66 |
| Uthmaniyah ${\mathrm{{CO}}}_{2}$ -EOR Demonstration Project | 0.8 | 2015 | Pipeline | 85 |
| Quest | Approx. 1.0 | 2015 | Pipeline | 64 |
| Abu Dhabi CCS Project (Phase 1 being Emirates Steel Industries (ESI) CCS Project) | 0.8 | 2016 | Pipeline | 43 |
| Petra Nova Carbon Capture Project 1. | 1.4 | 2017 | Pipeline | 132 |
N/A means no transport required (direct injection)
N/A表示无需运输(直接注入)
The diameter of the pipeline is the crucial parameter in pipeline design. Based on the mechanical energy balance, a model was developed to calculate the pipeline diameter required for a given pressure drop (Mohitpour et al., 2003). The diameter is also influenced by mass flow rate, fanning friction factor and pipeline length. The solving process is iterative, so an initial guess is needed.
管道直径是管道设计中的关键参数。基于机械能平衡,开发了一个模型来计算给定压力降所需的管道直径(Mohitpour等人,2003年)。直径还受质量流量、范宁摩擦系数和管道长度的影响。求解过程是迭代的,因此需要一个初始猜测值。
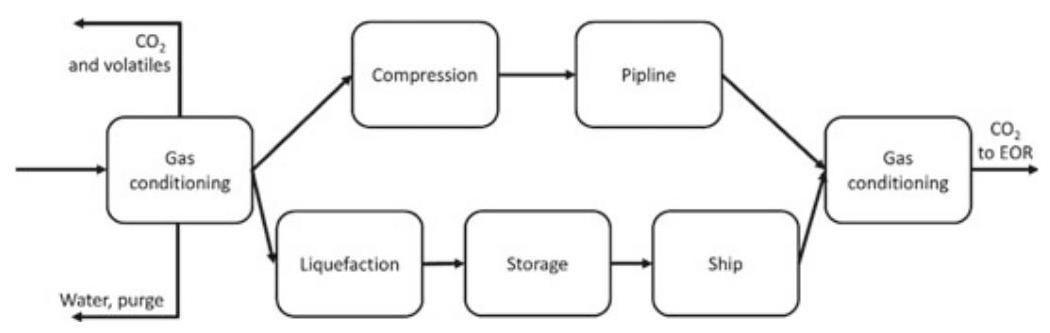
Fig. 3 The ${\mathrm{{CO}}}_{2}$ transport chain (Modified from Aspelund &Jordal,2007)
图3 ${\mathrm{{CO}}}_{2}$运输链(改编自Aspelund & Jordal,2007年)
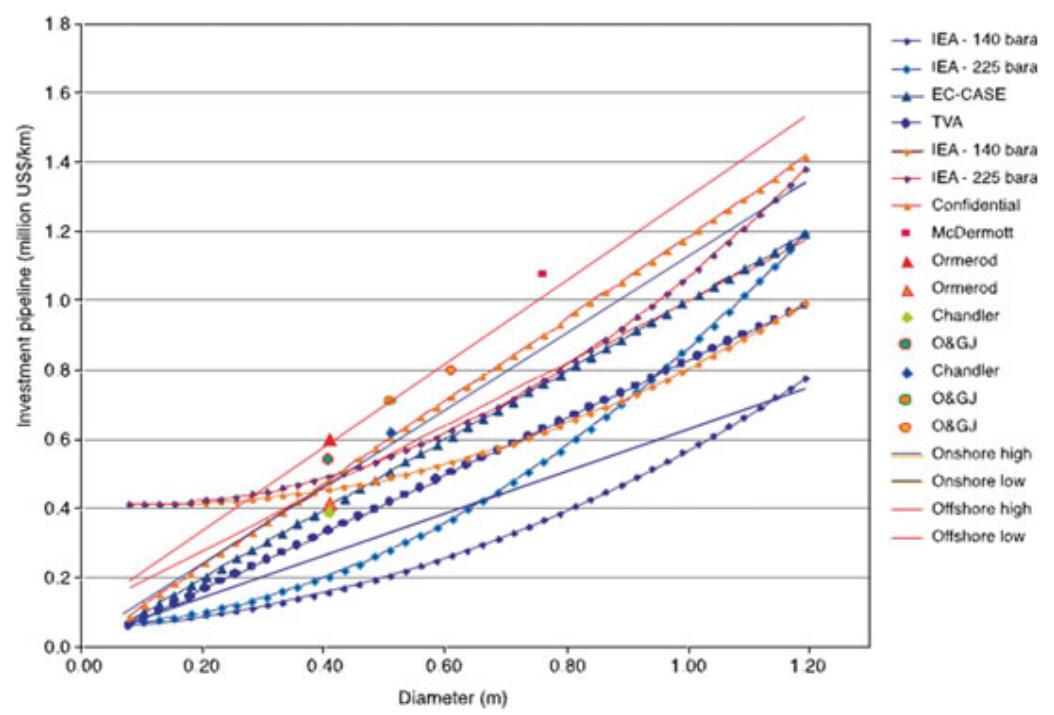
Fig. 4 Construction costs for pipelines from various information sources. Costs exclude booster stations (Metz, 2005)
图4来自各种信息源的管道建设成本。成本不包括增压站(Metz,2005年)
A monitoring system is essential as high concentrations of ${\mathrm{{CO}}}_{2}$ can be fatal for humans and animals. Pipelines can be monitored internally by pigs, which are pressure-driven devices with piston shapes moved along the pipeline, and can be monitored externally by leak detection systems.
监测系统至关重要,因为高浓度的${\mathrm{{CO}}}_{2}$对人类和动物可能是致命的。管道可以通过清管器进行内部监测,清管器是一种由压力驱动的活塞形状的装置,沿管道移动,也可以通过泄漏检测系统进行外部监测。
Economic Analysis of Pipeline Transport
管道运输的经济分析
The cost of ${\mathrm{{CO}}}_{2}$ transport includes three parts. Construction costs, also called capital costs, measure the initial investment costs. It contains material/equipment costs, and labor costs. Figure 4 shows construction costs for pipelines in different contexts. This data clearly shows the relationship between diameter and the capital cost. It is also obvious that booster stations increase the capital cost. Operation and maintenance costs include monitoring costs, maintenance costs and energy costs. Other costs are miscellaneous, including design, project management and right-of-way costs, etc. Levelized cost takes all the costs in the whole lifetime of a project into account (Fig. 5), and it represents the cost of per tonne ${\mathrm{{CO}}}_{2}$ transported by pipeline (McCollum & Ogden, 2006).
${\mathrm{{CO}}}_{2}$运输成本包括三个部分。建设成本,也称为资本成本,衡量初始投资成本。它包含材料/设备成本和劳动力成本。图4显示了不同情况下管道的建设成本。这些数据清楚地显示了管径与资本成本之间的关系。同样明显的是,增压站会增加资本成本。运营和维护成本包括监测成本、维护成本和能源成本。其他成本则是杂项成本,包括设计、项目管理和通行权成本等。平准化成本考虑了项目整个生命周期内的所有成本(图5),它代表了通过管道运输每吨${\mathrm{{CO}}}_{2}$的成本(McCollum & Ogden,2006年)。
Based on natural gas pipelines experience, Mccoy and Rubin (2008) developed a model for prediction of the pipeline capital expense in United States. For an illustrative example (transport of five million tonnes of ${\mathrm{{CO}}}_{2}$ with distance larger than ${100}\mathrm{\;{km}}$ ), capital cost was US$1.16 per tonne of ${\mathrm{{CO}}}_{2}$ . Liu and Gallagher (2011) developed a model which considers both engineering and economic factors with the background of China. For five illustrative case studies with a pipeline length of ${100}\mathrm{\;{km}}$ , the levelized costs are US$1.84-3.06 per tonne of ${\mathrm{{CO}}}_{2}$ .
基于天然气管道的经验,Mccoy和Rubin(2008年)开发了一个预测美国管道资本支出的模型。对于一个示例(运输500万吨${\mathrm{{CO}}}_{2}$,距离大于${100}\mathrm{\;{km}}$),资本成本为每吨${\mathrm{{CO}}}_{2}$ 1.16美元。Liu和Gallagher(2011年)在中国的背景下开发了一个同时考虑工程和经济因素的模型。对于五个管道长度为${100}\mathrm{\;{km}}$的示例案例研究,平准化成本为每吨${\mathrm{{CO}}}_{2}$ 1.84 - 3.06美元。
4.1.2 ${\mathrm{{CO}}}_{2}$ Transport by Ship
4.1.2 ${\mathrm{{CO}}}_{2}$ 船舶运输
${\mathrm{{CO}}}_{2}$ transport by ship is more flexible compared to pipeline transport, and it is more competitive for ocean ${\mathrm{{CO}}}_{2}$ storage or marine oilfield EOR. ${\mathrm{{CO}}}_{2}$ transport by ship is very similar to liquefied petroleum gas (LPG) transport by ship. However, the number of ${\mathrm{{CO}}}_{2}$ marine tankers is rather limited because of the low demand. Currently, there are no existing experienced ${\mathrm{{CO}}}_{2}$ transport ships for CCS. Only four small-scale semi-pressurized ${\mathrm{{CO}}}_{2}$ ships operate in western Europe, the ${\mathrm{{CO}}}_{2}$ of which is used for the food industry. Korean-CCS 1 and 2 may become the first two projects using shipment transport for ${\mathrm{{CO}}}_{2}$ , as the storage site is offshore Korea. Now they are under evaluation and the operation date is in the 2020s.
${\mathrm{{CO}}}_{2}$ 船舶运输与管道运输相比更具灵活性,对于海洋 ${\mathrm{{CO}}}_{2}$ 封存或海上油田提高采收率而言更具竞争力。${\mathrm{{CO}}}_{2}$ 船舶运输与液化石油气(LPG)船舶运输非常相似。然而,由于需求较低,${\mathrm{{CO}}}_{2}$ 海洋油轮数量相当有限。目前,尚无现有的经验丰富的用于碳捕集与封存(CCS)的 ${\mathrm{{CO}}}_{2}$ 运输船。在西欧仅有四艘小型半加压 ${\mathrm{{CO}}}_{2}$ 船运营,其中一艘用于食品工业。韩国碳捕集与封存1号和2号项目可能成为首批使用船舶运输 ${\mathrm{{CO}}}_{2}$ 的两个项目,因为其封存地点位于韩国近海。目前它们正在评估中,运营日期定在21世纪20年代。
Transport Technology and System Design
运输技术与系统设计
${\mathrm{{CO}}}_{2}$ transport process by ship is quite different compared to the process by pipeline. The ship transport chain of ${\mathrm{{CO}}}_{2}$ includes liquefaction and gas conditioning, an intermediate storage, a loading system, shipping and a loading system. At the onset of the transport process, ${\mathrm{{CO}}}_{2}$ is liquefied around its triple point. The density of ${\mathrm{{CO}}}_{2}$ is as high as ${1200}\mathrm{\;{kg}}/{\mathrm{m}}^{3}$ at its triple point and reduces to half at its critical point. Higher density means more ${\mathrm{{CO}}}_{2}$ can be transported for the same size ship. In addition, since ${\mathrm{{CO}}}_{2}$ is captured continuously but transported separately, the system must include an intermediate storage part. The ${\mathrm{{CO}}}_{2}$ is contained in semi-pressurized tanks before being loaded on board.
${\mathrm{{CO}}}_{2}$ 的船舶运输过程与管道运输过程有很大不同。${\mathrm{{CO}}}_{2}$ 的船舶运输链包括液化和气体调节、中间储存、装载系统、运输和卸载系统。在运输过程开始时,${\mathrm{{CO}}}_{2}$ 在其三相点附近被液化。${\mathrm{{CO}}}_{2}$ 在其三相点时的密度高达 ${1200}\mathrm{\;{kg}}/{\mathrm{m}}^{3}$,在临界点时降至一半。更高的密度意味着对于相同尺寸的船舶可以运输更多的 ${\mathrm{{CO}}}_{2}$。此外,由于 ${\mathrm{{CO}}}_{2}$ 是连续捕获但分开运输的,系统必须包括一个中间储存部分。${\mathrm{{CO}}}_{2}$ 在装载上船之前被储存在半加压罐中。
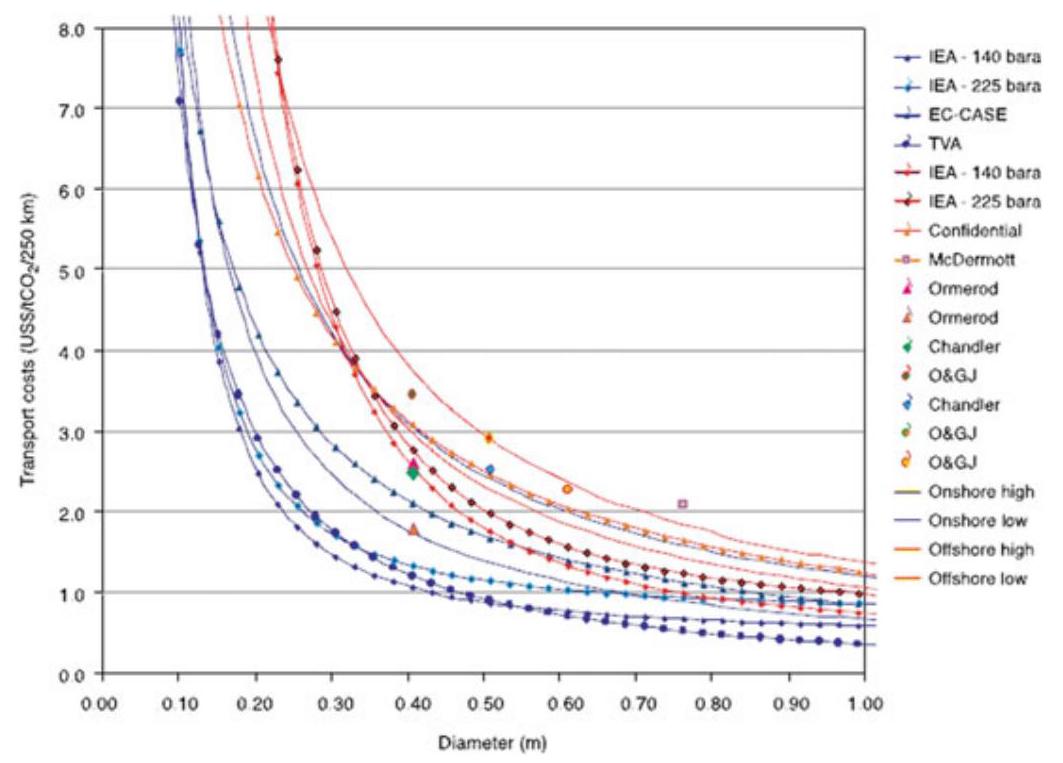
Fig. 5 Levelized cost of pipeline transport from various information sources (Metz, 2005)
图5 来自各种信息来源的管道运输平准化成本(梅茨,2005年)
There are three types of ships for transporting ${\mathrm{{CO}}}_{2}$ : fully pressurized ship, semi-pressurized ship and fully refrigerated ship. Semi-pressurized ships are recommended by ship designers and the best transport condition is at ${0.65}\mathrm{{MPa}}$ and $- {52}^{ \circ }\mathrm{C}$ (Bock et al.,2003). LPG ships can be rebuilt for ${\mathrm{{CO}}}_{2}$ transport. However, some difficulties may arise because the ${\mathrm{{CO}}}_{2}$ is transported at a little higher pressure and lower temperatures. It is noteworthy that ${\mathrm{{CO}}}_{2}$ leakage during ship transport is inevitable. The total loss is estimated between 3 and 4% per 1000 km (Metz, 2005).
有三种类型的船舶用于运输 ${\mathrm{{CO}}}_{2}$:全加压船、半加压船和全冷冻船。船舶设计师推荐使用半加压船,最佳运输条件是在 ${0.65}\mathrm{{MPa}}$ 和 $- {52}^{ \circ }\mathrm{C}$(博克等人,2003年)。液化石油气船可以改装用于 ${\mathrm{{CO}}}_{2}$ 运输。然而,可能会出现一些困难,因为 ${\mathrm{{CO}}}_{2}$ 是在略高的压力和较低的温度下运输的。值得注意的是,船舶运输过程中 ${\mathrm{{CO}}}_{2}$ 的泄漏是不可避免的。每1000公里的总损失估计在3%至4%之间(梅茨,2005年)。
Fig. 6 Comparison of costs of onshore and offshore pipelines, and ship transport (Metz, 2005)
图6 陆上和海上管道以及船舶运输成本的比较(梅茨,2005年)
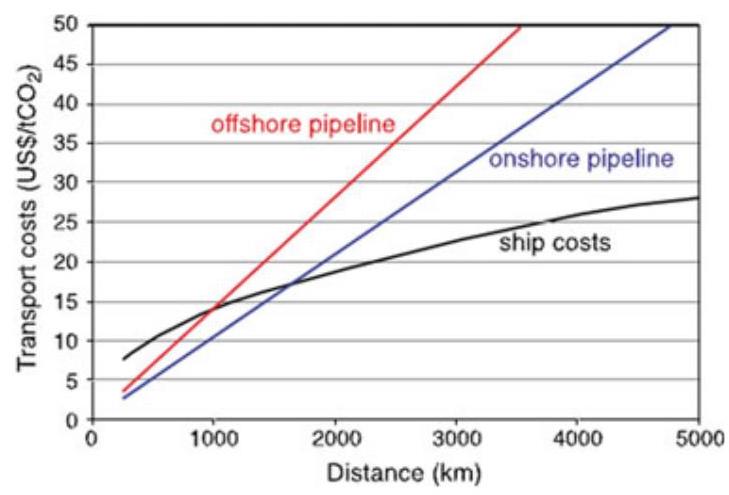
Economic Analysis of ${\mathrm{{CO}}}_{2}$ Transport by Ship
船舶运输${\mathrm{{CO}}}_{2}$的经济分析
Costs of shipment system are composed of capital costs, operational and maintenance costs and miscellaneous costs. However, less is known on the costs of a ${\mathrm{{CO}}}_{2}$ shipment system since no large-scale CCS projects adopt this means of transportation by far. Therefore, the cost estimates from different literature vary widely.
运输系统成本由资本成本、运营和维护成本以及杂项成本组成。然而,由于迄今为止尚无大规模的碳捕集与封存项目采用这种运输方式,因此对于${\mathrm{{CO}}}_{2}$运输系统的成本了解较少。所以,不同文献中的成本估算差异很大。
Aspelund et al. (2006) performed a cost, energy and ${\mathrm{{CO}}}_{2}$ emission analysis on transport chain within the North Sea. The total cost is US$20-30 per tonne of ${\mathrm{{CO}}}_{2}$ for volumes larger than $2\mathrm{{Mt}}$ per year. The energy requirement is ${142}\mathrm{{KWh}}$ per tonne of ${\mathrm{{CO}}}_{2}$ , and the liquefaction process accounts for the major energy consumption with a proportion of ${77}\%$ . Total ${\mathrm{{CO}}}_{2}$ emissions are estimated to be 1.4% of the inlet ${\mathrm{{CO}}}_{2}$ . By comparison, a case study in China gives the levelized cost of shipment transport as US$7.09 per tonne of ${\mathrm{{CO}}}_{2}$ with a ship transport distance of ${300}\mathrm{\;{km}}$ and pipeline length of ${25}\mathrm{\;{km}}$ (Gao et al.,2011). The ship capacity and travel distance are sensitive factors and will have large impact on cost. The relationship between travel distance and the levelized cost is non-linear. Therefore, ${\mathrm{{CO}}}_{2}$ transport by ship is a more economical solution when the distance is greater than ${1000}\mathrm{\;{km}}$ (Aspelund et al.,2006). Figure 6 clearly shows as distance increases, ship will be the cheapest way to transport ${\mathrm{{CO}}}_{2}$ .
阿斯佩伦德等人(2006年)对北海内的运输链进行了成本、能源和${\mathrm{{CO}}}_{2}$排放分析。对于每年运输量大于$2\mathrm{{Mt}}$的情况,每吨${\mathrm{{CO}}}_{2}$的总成本为20 - 30美元。每吨${\mathrm{{CO}}}_{2}$的能源需求为${142}\mathrm{{KWh}}$,液化过程占主要能源消耗,比例为${77}\%$。${\mathrm{{CO}}}_{2}$排放总量估计为进口${\mathrm{{CO}}}_{2}$的1.4%。相比之下,中国的一个案例研究给出了船舶运输的平准化成本为每吨${\mathrm{{CO}}}_{2}$7.09美元,船舶运输距离为${300}\mathrm{\;{km}}$,管道长度为${25}\mathrm{\;{km}}$(高等人,2011年)。船舶容量和航行距离是敏感因素,会对成本产生很大影响。航行距离与平准化成本之间的关系是非线性的。因此,当距离大于${1000}\mathrm{\;{km}}$时,船舶运输${\mathrm{{CO}}}_{2}$是更经济的解决方案(阿斯佩伦德等人,2006年)。图6清楚地表明,随着距离增加,船舶将是运输${\mathrm{{CO}}}_{2}$最便宜的方式。
4.1.3 Proximity Study
4.1.3 邻近性研究
Broadly speaking, any place that releases ${\mathrm{{CO}}}_{2}$ into the atmosphere is a ${\mathrm{{CO}}}_{2}$ source. In contrast, any place that sequestrates ${\mathrm{{CO}}}_{2}$ from the atmosphere is a ${\mathrm{{CO}}}_{2}$ sink. However, in this context sources and sinks refer to those related to CCS project. Therefore, ${\mathrm{{CO}}}_{2}$ sources include power plants, steel mills, cement factories, etc. ${\mathrm{{CO}}}_{2}$ sinks include oil reservoirs, deep saline aquifers, coal beds and the ocean.
广义而言,任何向大气中排放${\mathrm{{CO}}}_{2}$的地方都是一个${\mathrm{{CO}}}_{2}$源。相反,任何从大气中封存${\mathrm{{CO}}}_{2}$的地方都是一个${\mathrm{{CO}}}_{2}$汇。然而,在此背景下,源和汇指的是与碳捕集与封存(CCS)项目相关的那些。因此,${\mathrm{{CO}}}_{2}$源包括发电厂、钢铁厂、水泥厂等。${\mathrm{{CO}}}_{2}$汇包括油藏、深层盐水含水层、煤层和海洋。
Proximity study is indispensable in CCS system. It is necessary to spot the geo-location of ${\mathrm{{CO}}}_{2}$ sources and sinks and specify their capacity so as to evaluate the CCS potential in an area. In addition, the geological information can be used to calculate the transportation cost. The availability of ${\mathrm{{CO}}}_{2}$ sources data is relatively easy, but things are not easy for sinks. The sinks are always underground which means geological exploration method should be used. In this case, the accuracy is compromised. In most cases, ${\mathrm{{CO}}}_{2}$ sources and sinks do not coincide. So proximity study is needed to deploy CCS transport lines wisely to optimize the NPV.
邻近性研究在CCS系统中是不可或缺的。有必要确定${\mathrm{{CO}}}_{2}$源和汇的地理位置并明确其容量,以便评估一个地区的CCS潜力。此外,地质信息可用于计算运输成本。${\mathrm{{CO}}}_{2}$源数据的获取相对容易,但汇的情况并非如此。汇总是在地下,这意味着应使用地质勘探方法。在这种情况下,准确性会受到影响。在大多数情况下,${\mathrm{{CO}}}_{2}$源和汇并不重合。因此,需要进行邻近性研究以明智地部署CCS运输线路,从而优化净现值(NPV)。
Proximity study of China is at an early stage, though several studies have estimated CCS potential of China. Bai et al. (2006) performed a research on ${\mathrm{{CO}}}_{2}$ point sources in industry and studied how they distribute across China. Liu et al. (2005) made estimation on ${\mathrm{{CO}}}_{2}$ storage capacity of coalbeds in China. Li et al. (2006) studied domestic deep saline aquifers and ranked their potential for CCS application. At present, proximity study of China is at national scale which is not meaningful considering a specific CCS project. Also the lack of integrated study of sources and sinks undermines the integrity of CCS system. Therefore, proximity should be performed at regional scale and be more holistic in future.
中国的邻近性研究尚处于早期阶段,尽管已有多项研究对中国的CCS潜力进行了估算。白等人(2006年)对工业中的${\mathrm{{CO}}}_{2}$点源进行了研究,并探讨了它们在中国的分布情况。刘等人(2005年)对中国煤层的${\mathrm{{CO}}}_{2}$封存能力进行了估算。李等人(2006年)研究了国内的深层盐水含水层,并对它们在CCS应用方面的潜力进行了排名。目前,中国的邻近性研究是在国家层面进行的,考虑到具体的CCS项目,这并无实际意义。此外,缺乏对源和汇的综合研究也损害了CCS系统的完整性。因此,未来应在区域层面进行邻近性研究,并使其更加全面。
4.1.4 ${\mathrm{{CO}}}_{2}$ Transport Recommendation
4.1.4 ${\mathrm{{CO}}}_{2}$运输建议
${\mathrm{{CO}}}_{2}$ transport approaches should be determined based on proximity study and the quantity of ${\mathrm{{CO}}}_{2}$ to be sequestrated. For the existing alternatives, pipeline transport is the most economical and stable method for terrestrial storage. However, for some special cases, i.e. ${\mathrm{{CO}}}_{2}$ capture from marine natural gas production, ship transport can be an alternative option. In summary, pipeline transport is our recommendation for ${\mathrm{{CO}}}_{2}$ transport. We should focus on building of pipeline networks.
${\mathrm{{CO}}}_{2}$运输方式应根据近距离研究和待封存的${\mathrm{{CO}}}_{2}$数量来确定。对于现有的替代方案,管道运输是陆地封存最经济、最稳定的方法。然而,在一些特殊情况下,即从海洋天然气生产中捕获${\mathrm{{CO}}}_{2}$,船舶运输可以作为一种替代选择。总之,管道运输是我们对${\mathrm{{CO}}}_{2}$运输的建议。我们应专注于管道网络的建设。
4.2 Trapping Mechanisms of Geological Storage of ${\mathrm{{CO}}}_{2}$
4.2 ${\mathrm{{CO}}}_{2}$地质封存的捕集机制
Trapping mechanisms of ${\mathrm{{CO}}}_{2}$ can be classified into five types: structural, capillary, solubility, mineral and hydrodynamic trapping (Fig. 7). Contribution of different mechanisms is dynamic and the dominant mechanism is changing at different phases as ${\mathrm{{CO}}}_{2}$ migrates and reacts with rocks and fluids (Benson & Cole,2008). With the extension of time, the storage security of ${\mathrm{{CO}}}_{2}$ sequestration increases. The trapping mechanism determines the contribution of each trapping approach. At the beginning, structural trapping and hydrodynamic trapping play an important role. After hundreds of years, the effect of capillary, solubility and mineral trapping increases in importance. All the mechanisms will be introduced in detail in following sections.
${\mathrm{{CO}}}_{2}$的捕集机制可分为五种类型:构造捕集、毛细管捕集、溶解捕集、矿物捕集和水动力捕集(图7)。随着${\mathrm{{CO}}}_{2}$迁移并与岩石和流体发生反应,不同机制的贡献是动态变化的,主导机制在不同阶段也会发生变化(Benson & Cole,2008)。随着时间的推移,${\mathrm{{CO}}}_{2}$封存的存储安全性会提高。捕集机制决定了每种捕集方式的贡献。一开始,构造捕集和水动力捕集起重要作用。几百年后,毛细管捕集、溶解捕集和矿物捕集的作用会增强。所有机制将在后续章节详细介绍。
Fig. 7 Trapping mechanisms evolution with time (Modified from Metz et al., 2005)
图7捕集机制随时间的演变(改编自Metz等人,2005)
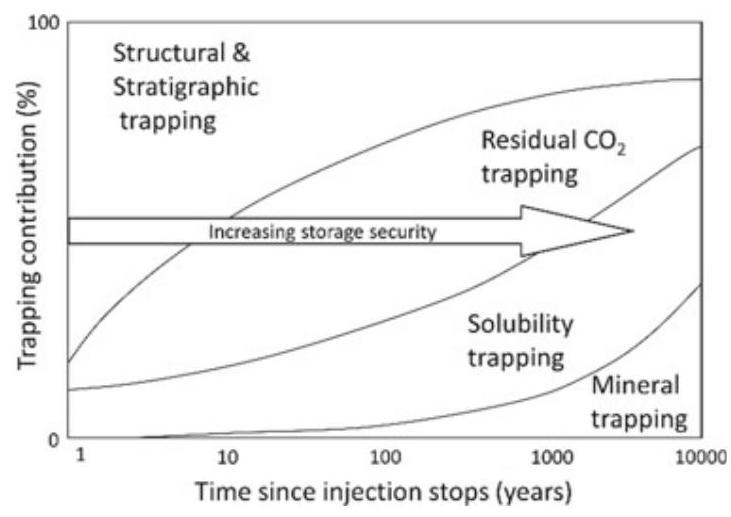
For scientific research on caprock-sealing mechanisms of ${\mathrm{{CO}}}_{2}$ sequestration, Song and Zhang (2013) presented a comprehensive overview of the ${\mathrm{{CO}}}_{2}$ caprock-sealing mechanisms, where the problems related to ${\mathrm{{CO}}}_{2}$ leakage are defined, and major research gaps and additional study areas are identified.
关于${\mathrm{{CO}}}_{2}$封存盖层封闭机制的科学研究,Song和Zhang(2013)全面概述了${\mathrm{{CO}}}_{2}$盖层封闭机制,定义了与${\mathrm{{CO}}}_{2}$泄漏相关的问题,并确定了主要研究差距和其他研究领域。
4.2.1 Structural Trapping
4.2.1 构造圈闭
Structural trapping is of great significance in early stages of ${\mathrm{{CO}}}_{2}$ injection. A thick and fine-textured rock, such as shale, can serve as a caprock above the sequestration reservoir and prevent ${\mathrm{{CO}}}_{2}$ from migrating freely. Though the buoyance of ${\mathrm{{CO}}}_{2}$ is large, the block effect of the impermeable layer impedes the vertical migration of ${\mathrm{{CO}}}_{2}$ . Furthermore, the caprock could prevent ${\mathrm{{CO}}}_{2}$ from migrating upwards due to its low permeability and high capillary entry pressure (Benson & Cole, 2008). The geological structure apt to such trap includes anticline, fault block, and pinch. In most cases, the structure originally contains oil and gas, or groundwater.
构造圈闭在${\mathrm{{CO}}}_{2}$注入的早期阶段具有重要意义。致密细粒岩石,如页岩,可作为封存储层上方的盖层,防止${\mathrm{{CO}}}_{2}$自由迁移。虽然${\mathrm{{CO}}}_{2}$的浮力很大,但不透水层的阻挡作用会阻碍${\mathrm{{CO}}}_{2}$的垂直迁移。此外,盖层因其低渗透率和高毛细管入口压力,可防止${\mathrm{{CO}}}_{2}$向上迁移(Benson & Cole,2008年)。易于形成此类圈闭的地质构造包括背斜、断块和尖灭。在大多数情况下,该构造最初含有石油和天然气或地下水。
4.2.2 Capillary Trapping
4.2.2 毛细管捕集
After injection when ${\mathrm{{CO}}}_{2}$ migrates into the formation, ${\mathrm{{CO}}}_{2}$ can be immobilized in pores within rocks because of the gas-liquid interface tension (IFT), which is called residual trapping. When large quantities of ${\mathrm{{CO}}}_{2}$ pass across porous media, ${\mathrm{{CO}}}_{2}$ is usually trapped in the pore as spherical drops. Therefore, the more the amount of ${\mathrm{{CO}}}_{2}$ passing the porous media, the more the ${\mathrm{{CO}}}_{2}$ is trapped in the rock pore. Normally, this process can last for several decades from the time ${\mathrm{{CO}}}_{2}$ once being injected into the formation.
注入后,当${\mathrm{{CO}}}_{2}$迁移到地层中时,由于气液界面张力(IFT),${\mathrm{{CO}}}_{2}$可以固定在岩石孔隙中,这称为残余捕集。当大量的${\mathrm{{CO}}}_{2}$穿过多孔介质时,${\mathrm{{CO}}}_{2}$通常以球形液滴的形式被困在孔隙中。因此,通过多孔介质的${\mathrm{{CO}}}_{2}$量越多,被困在岩石孔隙中的${\mathrm{{CO}}}_{2}$就越多。通常,从${\mathrm{{CO}}}_{2}$注入地层开始,这个过程可以持续几十年。
4.2.3 Solubility Trapping
4.2.3 溶解捕集
Another trapping mechanism, solubility trapping, starts to function when ${\mathrm{{CO}}}_{2}$ migrates in the pore of rocks. ${\mathrm{{CO}}}_{2}$ will contact with water and crude oil in which ${\mathrm{{CO}}}_{2}$ can dissolve. The solubility of ${\mathrm{{CO}}}_{2}$ is influenced by several elements, including temperature, pressure and fluid salinity. Other influencing elements that could affect the solubility of ${\mathrm{{CO}}}_{2}$ include the chemical components of formation fluids, and the contact rate between ${\mathrm{{CO}}}_{2}$ and formation fluids. Because of the gravity, ${\mathrm{{CO}}}_{2}$ -saturated formation fluids will move towards the center of the basin over time. Therefore, solubility trapping has more storage potential compared with structural trapping. The time-scale of solubility trapping is from 100 to 1000 years.
另一种捕集机制,即溶解捕集,在${\mathrm{{CO}}}_{2}$在岩石孔隙中迁移时开始起作用。${\mathrm{{CO}}}_{2}$会与其中${\mathrm{{CO}}}_{2}$可溶解的水和原油接触。${\mathrm{{CO}}}_{2}$的溶解度受几个因素影响,包括温度、压力和流体盐度。其他可能影响${\mathrm{{CO}}}_{2}$溶解度的因素包括地层流体的化学成分,以及${\mathrm{{CO}}}_{2}$与地层流体之间的接触速率。由于重力作用,随着时间推移,${\mathrm{{CO}}}_{2}$饱和的地层流体将向盆地中心移动。因此,与构造捕集相比,溶解捕集具有更大的储存潜力。溶解捕集的时间尺度为100至1000年。
4.2.4 Mineral Trapping
4.2.4 矿物捕集
Mineral trapping mechanism happens once ${\mathrm{{CO}}}_{2}$ , either in dissolved state or supercritical state, reacts in a direct or indirect way with formation rocks, which in most cases promotes carbonate mineral precipitation (Oelkers et al., 2008). Although mineral trapping is considered as the most reliable for the reason that it can last for very long periods, the reaction happens very slowly. The overall efficiency is usually achieved in a timescale of hundreds of years, or maybe longer. The main factors which can influence the speed of mineral trapping include chemical reaction process, fluid type and mineral composition. For example, the chemical reaction rate is high when the formation is carbonate. In contrast, the chemical reaction rate is low or even no reaction happens when the formation is sandstone.
当${\mathrm{{CO}}}_{2}$以溶解态或超临界态与地层岩石发生直接或间接反应时,矿物捕集机制便会发生,在大多数情况下,这会促使碳酸盐矿物沉淀(Oelkers等人,2008年)。尽管矿物捕集因其可持续很长时间而被认为是最可靠的,但反应发生得非常缓慢。总体效率通常在数百年甚至更长的时间尺度上才能实现。影响矿物捕集速度的主要因素包括化学反应过程、流体类型和矿物成分。例如,当地层为碳酸盐岩时,化学反应速率较高。相反,当地层为砂岩时,化学反应速率较低甚至不发生反应。
Besides geologic formation, concrete may be another choice when considering mineral trapping. A novel technology from CarbonCure injects ${\mathrm{{CO}}}_{2}$ into fresh concrete during production (ADB,2020). The injected ${\mathrm{{CO}}}_{2}$ has been proved to strengthen concrete mechanical properties, which can reduce cement requirement and optimize the mix designs. Most importantly, ${\mathrm{{CO}}}_{2}$ can be permanently trapped in concrete due to mineralization. This technology provides a new approach to storing and reusing waste ${\mathrm{{CO}}}_{2}$ .
除了地质构造外,在考虑矿物捕集时,混凝土可能是另一种选择。CarbonCure的一项新技术在生产过程中将${\mathrm{{CO}}}_{2}$注入新鲜混凝土中(亚洲开发银行,2020年)。已证明注入的${\mathrm{{CO}}}_{2}$可增强混凝土的力学性能,这可以减少水泥用量并优化配合比设计。最重要的是,${\mathrm{{CO}}}_{2}$可通过矿化永久地捕获在混凝土中。这项技术为储存和再利用废弃${\mathrm{{CO}}}_{2}$提供了一种新方法。
4.2.5 Hydrodynamic Trapping
4.2.5 水动力圈闭
The groundwater flow pressure will impede and accumulate ${\mathrm{{CO}}}_{2}$ when its direction is opposite to that of ${\mathrm{{CO}}}_{2}$ buoyancy and of approximately equal force. This mechanism works when the ${\mathrm{{CO}}}_{2}$ is injected into the deep saline aquifers within a closed formation. Like the structural trapping, hydrodynamic trapping works immediately after the injection. The difference is that the lateral movement of ${\mathrm{{CO}}}_{2}$ is not blocked in hydrodynamic trapping. The groundwater migration velocity is measured in centimeters per year, whereas the ${\mathrm{{CO}}}_{2}$ migration distance is measured in kilometers. So it will take thousands of years for the injected ${\mathrm{{CO}}}_{2}$ to migrate to the shallower geologic sections. Other trapping mechanisms will likely also contribute and, consequently, no free ${\mathrm{{CO}}}_{2}$ will reach the surface. Thus the integrity of the ${\mathrm{{CO}}}_{2}$ storage is guaranteed.
当地下水流动压力方向与${\mathrm{{CO}}}_{2}$浮力方向相反且力大致相等时,它会阻碍并聚集${\mathrm{{CO}}}_{2}$。当将${\mathrm{{CO}}}_{2}$注入封闭地层内的深层盐水含水层时,这种机制就会起作用。与构造圈闭一样,水动力圈闭在注入后立即起作用。不同之处在于,在水动力圈闭中${\mathrm{{CO}}}_{2}$的横向移动不会被阻止。地下水的迁移速度以厘米/年为单位,而${\mathrm{{CO}}}_{2}$的迁移距离以公里为单位。因此,注入的${\mathrm{{CO}}}_{2}$需要数千年才能迁移到较浅的地质层段。其他圈闭机制可能也会起作用,因此,不会有游离的${\mathrm{{CO}}}_{2}$到达地表。这样就保证了${\mathrm{{CO}}}_{2}$储存的完整性。
4.3 Options for ${\mathrm{{CO}}}_{2}$ Storage
4.3 ${\mathrm{{CO}}}_{2}$储存的选项
Generally speaking, optimal ${\mathrm{{CO}}}_{2}$ storage sites need to be located at the edge or inside a stable plate, such as a craton basin. The size and effectiveness of the basin storage space directly determine the amount of ${\mathrm{{CO}}}_{2}$ stored, and finally, the pressure and fluid system of the formation water in the basin are also crucial. important. According to the current research level, three basin geological bodies are appropriate to ${\mathrm{{CO}}}_{2}$ underground burial: depleted oil and gas reservoirs, saline aquifers, and coal seams (Fig. 8). Each structure type has a certain storage capacity, but due to different storage media, its storage conditions also have certain differences. Different options for ${\mathrm{{CO}}}_{2}$ storage have their advantages and disadvantage as discussed below.
一般来说,最佳的${\mathrm{{CO}}}_{2}$储存地点需要位于稳定板块的边缘或内部,如克拉通盆地。盆地储存空间的大小和有效性直接决定了${\mathrm{{CO}}}_{2}$的储存量,而且,盆地中地层水的压力和流体系统也至关重要。根据目前的研究水平,可以将三种盆地地质体用于${\mathrm{{CO}}}_{2}$的地下埋藏:枯竭油气藏、盐水层和煤层(图8)。每种结构类型都有一定的储存能力,但由于储存介质不同,其储存条件也存在一定差异。如下所述,${\mathrm{{CO}}}_{2}$储存的不同选项各有优缺点。
4.3.1 Depleted Oil and Gas Reservoirs
4.3.1枯竭的油气藏
Oil and gas reservoirs, especially depleted oil and gas reservoirs, are preferred for underground geological storage of ${\mathrm{{CO}}}_{2}$ due to following advantages: (1) Good trapping conditions (structural and stratigraphic), gas can be sealed for a long time with a small risk of leakage; (2) High degree of exploration, including the geological structure and physical properties; (3) Well-developed computer simulation technology and models for the prediction of trapping and displacement of hydrocarbons; (4) More than 80% of oil and gas reservoirs lie in deep formations. Pressure and temperature conditions are relatively easier to store ${\mathrm{{CO}}}_{2}$ in the supercritical state; (5) Complete infrastructure and wells constructions.
油气藏,尤其是枯竭的油气藏,由于以下优势,是${\mathrm{{CO}}}_{2}$地下地质储存的首选:(1)良好的圈闭条件(构造和地层),气体能够长时间被封存,泄漏风险小;(2)勘探程度高,包括地质构造和物理性质;(3)成熟的计算机模拟技术和模型,用于预测碳氢化合物的圈闭和驱替;(4)超过80%的油气藏位于深层地层。压力和温度条件相对更容易将${\mathrm{{CO}}}_{2}$储存于超临界状态;(5)基础设施和井的建设完备。
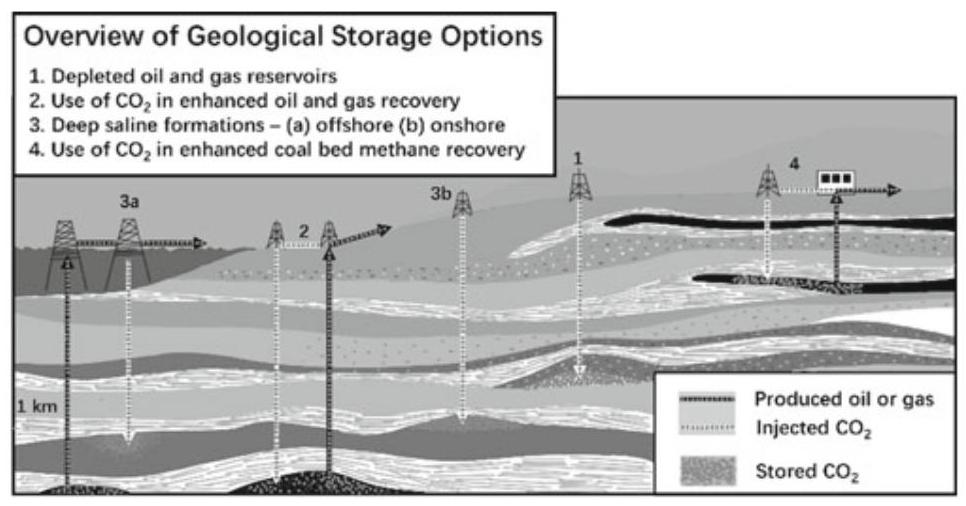
Fig. 8 Different kinds of appropriate ${\mathrm{{CO}}}_{2}$ storage sites (Modified from Benson &Cole, 2008)
图8不同类型的合适${\mathrm{{CO}}}_{2}$储存地点(改编自Benson & Cole,2008)
These conditions are the main- criteria for measuring whether a depleted oil field is capable of underground ${\mathrm{{CO}}}_{2}$ storage. However, care should be taken to avoid exceeding the pressure that the caprock can withstand, and the reservoir is not easily affected by permeability reduction induced by plugging near injection well and fluctuations in reservoir stress, which will cause the reservoir capacity to face certain limitations (Bossie-Codreanu et al., 2003; Kovscek, 2002). In addition, ${\mathrm{{CO}}}_{2}$ injection can also increase oil recovery rate, enhance oil and gas production and protect environment.
这些条件是衡量枯竭油田是否具备地下${\mathrm{{CO}}}_{2}$储存能力的主要标准。然而,应注意避免超过盖层所能承受的压力,并且储层不易受到注入井附近堵塞和储层应力波动引起的渗透率降低的影响,这会导致储层容量面临一定限制(Bossie-Codreanu等人,2003年;Kovscek,2002年)。此外,${\mathrm{{CO}}}_{2}$注入还可以提高采收率,增加油气产量并保护环境。
4.3.2 Saline Aquifers
4.3.2 盐性含水层
The underground saline aquifer suitable for geological storage of ${\mathrm{{CO}}}_{2}$ generally refers to a rock formation with high porosity and permeability that is filled with formation waters or brines, and the salt concentration of which is pretty high at a certain depth (at least 800 m) (Gunter et al., 1993). These filled salt waters (with a mass concentration of $\mathrm{{NaCl}}$ of ${32} \times {10}^{-3}\mathrm{{mg}}/\mathrm{L}$ ) are unsuitable for industrial or agricultural use. These saline aquifers can be found in most sedimentary basins in the world. Around 2 percent of the available space can be used to storage ${\mathrm{{CO}}}_{2}$ (Metz et al.,2005). The reservoir property directly affects the effectiveness, safety, and durability of storage.
适合进行${\mathrm{{CO}}}_{2}$地质封存的地下盐性含水层通常指的是孔隙度和渗透率较高、充满地层水或卤水且在一定深度(至少800米)盐浓度相当高的岩层(冈特等人,1993年)。这些充满的盐水($\mathrm{{NaCl}}$的质量浓度为${32} \times {10}^{-3}\mathrm{{mg}}/\mathrm{L}$)不适用于工业或农业用途。世界上大多数沉积盆地都能找到这些盐性含水层。大约2%的可用空间可用于储存${\mathrm{{CO}}}_{2}$(梅茨等人,2005年)。储层特性直接影响储存的有效性、安全性和耐久性。
The stratum depth of the top interface of the saline aquifer must be at least ${800}\mathrm{\;m}$ or more to guarantee the supercritical state of ${\mathrm{{CO}}}_{2}$ . If the top and bottom of the saline aquifer are blocked or enclosed by shale or gypsum-salt layers, the formation water will have a high salinity due to slow flow, which will be very conducive to the storage of ${\mathrm{{CO}}}_{2}$ , which can stay for millions of years.
盐性含水层顶部界面的地层深度必须至少为${800}\mathrm{\;m}$或更深,以确保${\mathrm{{CO}}}_{2}$处于超临界状态。如果盐性含水层的顶部和底部被页岩或石膏 - 盐层封堵或封闭,由于水流缓慢,地层水的盐度会很高,这将非常有利于${\mathrm{{CO}}}_{2}$的储存,${\mathrm{{CO}}}_{2}$可以留存数百万年。
Because of the density difference between ${\mathrm{{CO}}}_{2}$ and formation water, the ${\mathrm{{CO}}}_{2}$ injected into the saltwater layer will move upward under the action of buoyancy. This movement appears irregular due to being blocked by low permeability rock formations or lenses. If it encounters a suitable stratigraphic or structural trap, it will be stored; while if there are no such blocking or enclosure conditions, ${\mathrm{{CO}}}_{2}$ may continue to move upwards and cannot be buried in deep saline aquifers. In addition, in general sandstone or carbonate rock, pores or cracks are relatively developed, and most of them are easily filled by water to form saline aquifers. On the contrary, crystalline and metamorphic rocks, like granite, are not applicable to the formation of saline aquifers and therefore to ${\mathrm{{CO}}}_{2}$ storage.
由于${\mathrm{{CO}}}_{2}$与地层水之间的密度差异,注入盐水层的${\mathrm{{CO}}}_{2}$在浮力作用下会向上移动。由于被低渗透率岩层或透镜体阻挡,这种移动显得不规则。如果遇到合适的地层或构造圈闭,它将被储存起来;而如果没有这种封堵或封闭条件,${\mathrm{{CO}}}_{2}$可能会继续向上移动,无法被埋入深层盐性含水层。此外,一般来说砂岩或碳酸盐岩中孔隙或裂缝相对发育,其中大部分很容易被水填充形成盐性含水层。相反,像花岗岩这样的结晶岩和变质岩不适用于形成盐性含水层,因此也不适用于${\mathrm{{CO}}}_{2}$储存。
The ${\mathrm{{CO}}}_{2}$ injected into the stable saltwater layer is mainly dissolved in the early stage of the chemical reaction. Under normal circumstances, the solubility of ${\mathrm{{CO}}}_{2}$ in saline aquifers will increase with pressure, temperature, and salinity, and it is also related to the contact with formation water. Experiments show that under certain salinity and depth conditions, assuming that the saline aquifer is more homogeneous and given sufficient dissolution time, $1{\mathrm{\;m}}^{3}$ of formation water can dissolve about ${20} - {60}\mathrm{\;{kg}}$ of ${\mathrm{{CO}}}_{2}$ ; if the injection continues for 25 years, then 10-25% of ${\mathrm{{CO}}}_{2}$ will be dissolved by formation water (Gale,2003).
注入稳定盐水层的${\mathrm{{CO}}}_{2}$在化学反应初期主要是溶解。通常情况下,${\mathrm{{CO}}}_{2}$在盐性含水层中的溶解度会随着压力、温度和盐度的增加而增大,并且还与和地层水的接触有关。实验表明,如果盐性含水层更均匀且有足够的溶解时间,在一定盐度和深度条件下,地层水中$1{\mathrm{\;m}}^{3}$可以溶解约${20} - {60}\mathrm{\;{kg}}$的${\mathrm{{CO}}}_{2}$;如果持续注入25年,那么10 - 以及25%的${\mathrm{{CO}}}_{2}$会被地层水溶解(盖尔,2003年)。
4.3.3 Coal Seams
4.3.3 煤层
In coal beds, the storage of ${\mathrm{{CO}}}_{2}$ is mainly realized by the ${\mathrm{{CO}}}_{2}$ adsorption process. Injected plume of ${\mathrm{{CO}}}_{2}$ is mainly within the cleat between the coal blocks and inside the coal block (Rice et al., 1993). There are many tiny pores developed in the coal block sandwiched between the endogenous fissures, which can fully and firmly absorb the gas molecules from the fissures, thus the endogenous fissures between the coal blocks are important in the coal seam. The pore system is very important in the process of gas transport between different seams. Therefore, this transport effect directly affects ${\mathrm{{CO}}}_{2}$ injection and storage prospects. At present, the majority of coal seams worldwide suffer from low permeability, the average of which is only $1 - 5 \times {10}^{-3}\mu {\mathrm{m}}^{2}$ . In addition, the formation thickness is relatively thin, the average is only $1 - 5\mathrm{\;m}$ or part of $> 5\mathrm{\;m}$ (Larsen,2004). This unfavorable condition directly restricts the storage capacity of ${\mathrm{{CO}}}_{2}$ in coal seams and specific storage projects implementation.
在煤层中,${\mathrm{{CO}}}_{2}$ 的储存主要通过 ${\mathrm{{CO}}}_{2}$ 吸附过程实现。注入的 ${\mathrm{{CO}}}_{2}$ 羽流主要存在于煤块之间的割理以及煤块内部(Rice等人,1993年)。夹在内生裂隙之间的煤块中发育有许多微小孔隙,这些孔隙能够充分且牢固地吸附裂隙中的气体分子,因此煤块之间的内生裂隙在煤层中很重要。孔隙系统在不同煤层间的气体运移过程中非常重要。所以,这种运移效应直接影响 ${\mathrm{{CO}}}_{2}$ 的注入和储存前景。目前,全球大多数煤层渗透率较低,平均仅为 $1 - 5 \times {10}^{-3}\mu {\mathrm{m}}^{2}$ 。此外,地层厚度相对较薄,平均仅为 $1 - 5\mathrm{\;m}$ 或 $> 5\mathrm{\;m}$ 的一部分(Larsen,2004年)。这种不利条件直接限制了煤层中 ${\mathrm{{CO}}}_{2}$ 的储存能力以及具体储存项目的实施。
4.3.4 Deep-Sea Sediments
4.3.4 深海沉积物
Although the above-mentioned storage method has good application prospects, there is still a risk of leakage because of the pressure rise induced by ${\mathrm{{CO}}}_{2}$ . Scientists from many countries have begun to pay attention to deep-sea sediments.
尽管上述储存方法具有良好的应用前景,但由于${\mathrm{{CO}}}_{2}$引起的压力上升,仍存在泄漏风险。许多国家的科学家已开始关注深海沉积物。
The latest research (Teng & Zhang, 2018) studied the long-term evolution process of carbon dioxide injected into the seabed sediments, carried out numerical studies in a computer, and evaluated the effect of storage. Studies have found that in a high-pressure and low-temperature environment, the high density of liquid carbon dioxide will cause “negative buoyancy” in a sinking state. Coupled with the reaction of carbon dioxide with water to form carbon dioxide hydrate and block the flow channel, it can affect the carbon dioxide in the formation. The floating situation plays a very good role in hindering, so as to realize the safe, stable, and permanent storage of ${\mathrm{{CO}}}_{2}$ . On the other hand, the ${\mathrm{{CO}}}_{2}$ stored by this method will not come into contact with seawater, which avoids the negative impact on the marine ecological environment that may be caused by conventional deep-sea ${\mathrm{{CO}}}_{2}$ storage.
最新研究(Teng & Zhang,2018)对注入海底沉积物中的二氧化碳的长期演化过程进行了研究,在计算机中开展了数值研究,并对储存效果进行了评估。研究发现,在高压低温环境下,液态二氧化碳的高密度会使其在下沉状态下产生“负浮力”。再加上二氧化碳与水反应形成二氧化碳水合物并堵塞流道,会对地层中二氧化碳的上浮情况起到很好的阻碍作用,从而实现${\mathrm{{CO}}}_{2}$的安全、稳定和永久储存。另一方面,通过这种方法储存的${\mathrm{{CO}}}_{2}$不会与海水接触,避免了传统深海${\mathrm{{CO}}}_{2}$储存可能对海洋生态环境造成的负面影响。
This research provides a novel solution for geological storage of ${\mathrm{{CO}}}_{2}$ in addition to land, expanding the storage sites to a wide range of marine sediments, and has important significance and application prospects for the future global carbon dioxide emissions reduction and storage options.
这项研究为除陆地之外的${\mathrm{{CO}}}_{2}$地质储存提供了一种新的解决方案,将储存地点扩展到了广泛的海洋沉积物中,对于未来全球二氧化碳减排和储存选择具有重要意义和应用前景。
Since the operating facilities required for deep-sea geological storage are similar to the semi-submersible offshore platforms designed for combustible ice mining in the sea, and the injection of carbon dioxide is conducive to the mining of combustible ice, the two can be carried out simultaneously. The next step of research may try to actively seek opportunities to combine with field experiments on the combustible ice mining.
由于深海地质储存所需的作业设施与为开采海洋可燃冰而设计的半潜式海上平台类似,且注入二氧化碳有利于可燃冰的开采,二者可以同时进行。下一步研究可能会积极寻求与可燃冰开采的现场试验相结合的机会。
4.3.5 CO2 Storage Recommendation
4.3.5二氧化碳封存建议
In light of the large quantities of coalbeds and oilfields in China, ECBM and EOR are recommended. On the one hand, the ${\mathrm{{CO}}}_{2}$ storage potential is large. On the other hand, the increase in coal gas and oil production could be profitable. It is also necessary to improve the techniques for ${\mathrm{{CO}}}_{2}$ storage to lower the cost and leakage risk. For example, a new monitoring system is needed. Finally, we should attract more and more enterprises to participate in the CCS projects. It is very beneficial to expand the scale of CCS and increase the public awareness.
鉴于中国有大量的煤层和油田,建议采用强化煤层气(ECBM)和强化采油(EOR)。一方面,${\mathrm{{CO}}}_{2}$封存潜力巨大。另一方面,增加煤气和石油产量可能会带来利润。还需要改进${\mathrm{{CO}}}_{2}$封存技术以降低成本和泄漏风险。例如,需要一个新的监测系统。最后,我们应该吸引越来越多的企业参与碳捕集与封存(CCS)项目。这对于扩大CCS规模和提高公众意识非常有益。
4.4 Case Studies
4.4 案例研究
4.4.1 CCS Projects in the World
4.4.1 世界上的碳捕集与封存项目
As the world’s first commercial ${\mathrm{{CO}}}_{2}$ storage project, Sleipner operated at 1996 and millions of tonnes of ${\mathrm{{CO}}}_{2}$ were injected underground in the middle of the Central North Sea ever since. Covering an area of about ${26},{000}{\mathrm{\;{km}}}^{2}$ , the shallow sands in Utsira Formation act as an ideal site for ${\mathrm{{CO}}}_{2}$ storage. The thickness of the formation is between 200 to ${300}\mathrm{\;m}$ and porosity is up to ${40}\%$ and permeability is above 1 Darcy. High porosity and large permeability enable Utsira Formation to storage large quantities of ${\mathrm{{CO}}}_{2}$ . The estimated storing capability of Utsira Formation is up to 600 billion tonnes.
作为世界上第一个商业性的${\mathrm{{CO}}}_{2}$储存项目, Sleipner项目于1996年开始运营,自那时起,数百万吨的${\mathrm{{CO}}}_{2}$被注入北海中部的地下。乌特西拉组的浅海砂层面积约为${26},{000}{\mathrm{\;{km}}}^{2}$,是${\mathrm{{CO}}}_{2}$储存的理想场所。该地层厚度在200至${300}\mathrm{\;m}$之间,孔隙度高达${40}\%$,渗透率超过1达西。高孔隙度和高渗透率使乌特西拉组能够储存大量${\mathrm{{CO}}}_{2}$。乌特西拉组的估计储存能力高达6000亿吨。
From Table 2, we can see that most of world’s massive CCS projects utilize ${\mathrm{{CO}}}_{2}$ to increase oil production rate. The other three projects inject ${\mathrm{{CO}}}_{2}$ into deep saline aquifers for storage.
从表2中我们可以看出,世界上大多数大规模碳捕集与封存项目利用${\mathrm{{CO}}}_{2}$来提高石油产量。其他三个项目则将${\mathrm{{CO}}}_{2}$注入深层盐水层进行储存。
4.4.2 CCS Projects in China
4.4.2中国的碳捕集与封存项目
Many Chinese energy-related companies have made efforts on CCS development and a series of CCS projects and many demonstration CCS projects have been implemented. In 2011, Shenhua Group picked Ordos Basin to demonstrate their CCS project and began to sequestrate ${\mathrm{{CO}}}_{2}$ in saline aquifers. Two largest oil companies in China, CNPC and Sinopec, have launched numerous ${\mathrm{{CO}}}_{2}$ -EOR operations in many plays, and many academic achievements are made (Wu et al., 2014). Huaneng Group has also attempted to build devices to collect ${\mathrm{{CO}}}_{2}$ from flue gas in large Chinese cities. China United Coalbed Methane Co., Ltd. has been carrying out ${\mathrm{{CO}}}_{2}$ -ECBM projects in two wells. The CCS project in Yanchang, Shanxi Province has also come into the implementation stage. Every year, around half a million tonnes of ${\mathrm{{CO}}}_{2}$ is collected from local chemical plants, and the ${\mathrm{{CO}}}_{2}$ was then transported to the storage site.
许多中国能源相关企业在碳捕集与封存发展方面做出了努力,实施了一系列碳捕集与封存项目以及许多示范项目。2011年,神华集团选择鄂尔多斯盆地来示范其碳捕集与封存项目,并开始在盐水层中封存${\mathrm{{CO}}}_{2}$。中国石油天然气集团公司(CNPC)和中国石油化工集团公司(Sinopec)这两家中国最大的石油公司,在多个油田开展了大量的${\mathrm{{CO}}}_{2}$提高采收率作业,并取得了许多学术成果(Wu等人,2014年)。华能集团也试图在中国大城市建造从烟气中收集${\mathrm{{CO}}}_{2}$的装置。中联煤层气有限责任公司一直在两口井中开展${\mathrm{{CO}}}_{2}$强化煤层气项目。山西省延长县的碳捕集与封存项目也已进入实施阶段。每年从当地化工厂收集约50万吨${\mathrm{{CO}}}_{2}$,然后将这些${\mathrm{{CO}}}_{2}$运输到储存地点。
4.4.3 The Next Wave of Projects
4.4.3 下一波项目
The Paris Agreement sets a plan of keeping global temperature increase below $2{}^{ \circ }\mathrm{C}$ by 2050, and CCS plays a key role for achieving this target. However, the overall trend of CCS is not promising. Around two thirds of CCS projects are unable to reach a financial investment decision. By 2016 the large-scale CCS projects had shrunk to 38 from 77 large-scale CCS projects in 2010. It is clear to see that the pace of global CCS project development is stagnated and even goes backwards. (IEA, 2016) concludes that CCS is off track for Paris Agreement goals and picking up the pace of CCS deployment is urgent. Accelerating the pace of CCS deployment needs more policy support, economic investment, advanced technology, and global cooperation.
《巴黎协定》制定了到2050年将全球气温升幅控制在$2{}^{ \circ }\mathrm{C}$以内的计划,而碳捕集、利用与封存(CCS)对于实现这一目标起着关键作用。然而,CCS的总体趋势并不乐观。约三分之二的CCS项目无法达成财务投资决策。到2016年,大型CCS项目已从2010年的77个缩减至38个。可以明显看出,全球CCS项目的发展步伐停滞不前,甚至出现倒退。(国际能源署,2016年)得出结论,CCS偏离了《巴黎协定》的目标,加快CCS部署的步伐迫在眉睫。加快CCS部署需要更多的政策支持、经济投资、先进技术和全球合作。
Table 2 Primary capture and storage type of global large-scale CCS project in operation. Adapted from GCCSI (2017b)
表2 全球运行中的大型CCS项目的主要捕集和封存类型。改编自全球碳捕集与封存协会(2017b)
| Project name | Country | Operation date | Industry | Capture type | Primary storage type |
| Val Verde Natural Gas Plants | United States | 1972 | Natural gas processing | Pre-combustion capture | Enhanced oil recovery |
| Enid Fertilizer ${\mathrm{{CO}}}_{2}$ -EOR Project | United States | 1982 | Fertiliser production | Industrial separation | Enhanced oil recovery |
| Shute Creek Gas Processing Facility | United States | 1986 | Natural gas processing | Pre-combustion capture | Enhanced oil recovery |
| Sleipner ${\mathrm{{CO}}}_{2}$ Storage Project | NORWAY | 1996 | Natural gas processing | Pre-combustion capture | offshore deep saline formations |
| Great Plains Synfuel Plant and Weyburn-Midale Project | CANADA | 2000 | Synthetic natural gas | Pre-combustion capture | Enhanced oil recovery |
| Snohvit CO2 Storage Project | NORWAY | 2008 | Natural gas processing | Pre-combustion capture | offshore deep saline formations |
| Century Plant | United States | 2010 | Natural gas processing | Pre-combustion capture | Enhanced oil recovery |
| Air Products Steam Methane Reformer EOR Project | United States | 2013 | Hydrogen production | Industrial separation | Enhanced oil recovery |
| Coffeyville Gasification Plant | United States | 2013 | Fertiliser production | Industrial separation | Enhanced oil recovery |
| Lost Cabin Gas Plant | United States | 2013 | Natural gas processing | Pre-combustion capture | Enhanced oil recovery |
(continued)
(续)
Table 2 (continued)
表2(续)
| Project name | Country | Operation date | Industry | Capture type | Primary storage type |
| Petrobras Santos Basin Pre-Salt Oil Field CCS Project | Brazil | 2013 | Natural gas processing | Pre-combustion capture | Enhanced oil recovery |
| Boundary Dam Carbon Capture and Storage Project | Canada | 2014 | Power generation | Post-combustion capture | Enhanced oil recovery |
| Uthmaniyah ${\mathrm{{CO}}}_{2}$ -EOR Demonstration Project | Saudi Arabia | 2015 | Natural gas processing | Pre-combustion capture | Enhanced oil recovery |
| Quest | Canada | 2015 | Hydrogen production | Industrial separation | onshore deep saline formations |
| Abu Dhabi CCS Project (Phase 1 being Emirates Steel Industries (ESI) CCS Project) | United Arab Emirates | 2016 | Iron and steel production | Industrial separation | Enhanced oil recovery |
| Petra Nova Carbon Capture Project | United States | 2017 | Power generation | Post-combustion capture | Enhanced oil recovery |
Acronym Full spelling
首字母缩写 全称
ADB Asian Development Bank
亚行 亚洲开发银行
AOD Argon Oxygen Decarburization
氩氧脱碳
BECCS Bio-Energy CCS
生物能源碳捕集与封存
BOF Basic Oxygen Furnace
碱性氧气转炉
CC Continuous Casting
连铸
CCS Carbon Capture, Utilization and Storage
碳捕集、利用与封存
${\mathrm{{CO}}}_{2}$ -EOR ${\mathrm{{CO}}}_{2}$ Enhanced Oil Recovery
${\mathrm{{CO}}}_{2}$ - 提高采收率 ${\mathrm{{CO}}}_{2}$ 强化采油
CP Cyclopentane
环戊烷
CNPC China’s National Petroleum Corporation
中国石油天然气集团公司
DAC Direct Air Capture
直接空气捕集
DTAC Dodecyl-trimethyl-ammonium Chloride
十二烷基三甲基氯化铵
EAF Electric Arc Furnace
电弧炉
ECBM Enhanced Coal Bed Methane
强化煤层气
EnOpt Ensemble-based Optimization
基于集合的优化
EOR Enhance Oil Recovery
提高采收率
ESI Emirates Steel Industries
阿联酋钢铁工业公司
GCCSI Global CCS Institute
全球碳捕集与封存研究所
HBCC Hydrate-based ${\mathrm{{CO}}}_{2}$ Capture
基于水合物的${\mathrm{{CO}}}_{2}$捕集
IEA International Energy Agency
国际能源署
IPCC Intergovernmental Panel on Climate Change
政府间气候变化专门委员会
KTH Royal Institute of Technology Sweden
瑞典皇家理工学院
LF Ladle Furnace
钢包精炼炉
LPG Liquefied Petroleum Gas
液化石油气
MEA Monoethanolamine
一乙醇胺
MLC Medium and Low Carbon
中低碳
PSA Pressure Swing Adsorption
变压吸附
SDS Sodium Dodecyl Sulphate
十二烷基硫酸钠
TBAB Tetra-n-butyl Ammonium Bromide
四丁基溴化铵
THF Tetrahydrofuran
四氢呋喃
TRT Top-Pressure Recovery Turbine Plant
顶压回收透平装置
TSA Temperature Swing Adsorption
变温吸附
VPSA Vacuum Pressure Swing Adsorption
变压吸附
References
参考文献
ADB. (2020). Carbon capture, utilization, and storage game changers in Asia.
Anderson S. H., Doulas C. L., & Bermel, C. L. (1990). Use of ${\mathrm{{CO}}}_{2}$ in the AOD. In 47th Electric Furnace Conference Proceedings; ISS-AIME (pp. 297-304).
Anderson, Foulard, J., & Lutgen, V. (1989). Inert gas technology for the production of low nitrogen steels. In Electric Furnace Proceeding (pp. 365-375).
Aspelund, A.,& Jordal, K. (2007). Gas conditioning-The interface between ${\mathrm{{CO}}}_{2}$ capture and transport. International Journal of Greenhouse Gas Control, 1(3), 343-354.
Aspelund, A., Molnvik, M. J., & Dekoeijer, G. (2006). Ship transport of ${\mathrm{{CO}}}_{2}$ technical solutions and analysis of costs, energy utilization, exergy efficiency and ${\mathrm{{CO}}}_{2}$ emissions. Chemical Engineering Research & Design, 84(9), 847-855.
Baciocchi, R., Costa G., & Polettini, A., Pomi, R. (2010). Accelerated mineral carbonation of steel slags. In Proceedings of the first International Slag Valorisation Symposium, Leuven, Belgium, April 6-7, 2009 (pp. 51-63). Leuven, Belgium: Katholieke Universiteit Leuven.
Bai, B., Xiaochun, L. I., Liu, Y., & Zhang, Y. (2006). Preliminary study on ${\mathrm{{CO}}}_{2}$ industrial point sources and their distribution in china. Chinese Journal of Rock Mechanics & Engineering, 25(2), 2918-2923.
Baoshan Iron and Steel. (2008). Sustainability report 2007 (116 pp). Shanghai, China: Baoshan Iron and Steel Co. www.baosteel.com
Benson, S. M., & Cole, D. R. (2008). ${\mathrm{{CO}}}_{2}$ sequestration in deep sedimentary formations. Elements, 4(5), 325-331.
Bi, X. R., Zhu, R., & Liu, R. Z. (2012). Fundamental study on stainless steel making through ${\mathrm{{CO}}}_{2} - {\mathrm{O}}_{2}$ mixture blowing. Steelmaking, ${28}\left( 2\right) ,{67} - {70}$ . (in Chinese).
Bi, X. R., Zhu, R., & Lv, M. (2010). Research on mechanism of dust generation in converter. Industrial Heating, 06, 13-16. (in Chinese).
Birat, J.-P. (2010). Carbon dioxide $\left( {\mathrm{{CO}}}_{2}\right)$ capture and storage technology in the iron and steel industry. In Developments and innovation in carbon dioxide $\left( {\mathrm{{CO}}}_{2}\right)$ capture and storage technology Vol. 1: carbon dioxide $\left( {\mathrm{{CO}}}_{2}\right)$ capture, transport and industrial applications (pp. 492-521). Woodhead Publishing Ltd.
Bock, B., Rhudy, R., Herzog, H., Klett, M., Davison, J., & Ugarte, D. G. D. L. T., et al. (2003). Economic evaluation of ${\mathrm{{CO}}}_{2}$ storage and sink enhancement options. Office of Scientific & Technical Information Technical Reports.
Boot-Handford, M. E., Abanades, J. C., Anthony, E. J., Blunt, M. J., Brandani, S., Mac Dowell, N., Fernández, J. R., Ferrari, M.-C., Gross, R., Hallett, J. P., et al. (2014). Carbon capture and storage update. Energy & Environmental Science, 7(1), 130-189.
Bossie-Codreanu, D., Le-Gallo, Y., Duquerroix, J., Doerler, N., & Le Thiez, P. (2003). CO2 sequestration in depleted oil reservoirs. In Paper presented at the Greenhouse Gas Control Technologies-6th International Conference.
Bruce, E. T, Weisang, F., Allibert, M., & Fruehan, R. (1987a). In Electric Furnace Conference Proceedings (p. 293). Chicago: ISS-AIME.
Bruce, E. T, Weisang, F., Allibert, M., Fruehan, R. (1987b). Effects of ${\mathrm{{CO}}}_{2}$ stirring in a ladle. In 45th Electric Furnace Proceedings (pp. 293-297), December 8-11, 1987, Chicago, USA.
Bui, M., Adjiman, C. S., Bardow, A., Anthony, E. J., Boston, A., Brown, S., Fennell, P. S., Fuss, S., Galindo, A., Hackett, L. A., et al. (2018). Carbon capture and storage (CCS): The way forward. Energy & Environmental Science, 11(5), 1062-1176.
Carpenter, A. (2012). CO2abatement in the iron and steel industry (pp. 83-94). IEA Clean Coal Centre.
Chen, J.B., Yang, Z.L, & He D. Z. (2008). Treatment outside the furnace. Metallurgical Industry Press (in Chinese).
Dashti, H., Yew, L. Z., & Lou, X. (2015). Recent advances in gas hydrate-based ${\mathrm{{CO}}}_{2}$ capture. Journal of Natural Gas Science and Engineering, 23, 195-207.
Davidson, R. M. (2007). Post-combustion carbon capture from coal fired plant-solvent scrubbing. CCC/125 (58 pp), London, UK: IEA Clean Coal Centre
Dong, K., Zhu, R., & Liu, R. Z. (2014). Influence of bottom blowing ${\mathrm{{CO}}}_{2}$ in LF on molten steel quality and erosion of ventilated bricks. Journal of University of Science and Technology Beijing, 36(s1), 226-229. (in Chinese).
Dong, X. D. (2008). Experimental study on converter slag quickly absorbing ${\mathrm{{CO}}}_{2}$ . Steelmaking., 24, 29-32. (in Chinese).
Doucet, F. J. (2010). Effective ${\mathrm{{CO}}}_{2}$ -specific sequestration capacity of steel slags and variability in their leaching behaviour in view of industrial mineral carbonation. Minerals Engineering, 23(3), 262-269.
Duc, N. H., Chauvy, F., & Herri, J.-M. (2007). CO2 capture by hydrate crystallization-a potential solution for gas emission of steelmaking industry. Energy Conversion and Management, 48(4), 1313-1322.
Eloneva, S., Teir, S., Salminen, J., Fogelholm, C.-J., & Zevenhoven, R. (2008). Fixation of ${\mathrm{{CO}}}_{2}$ by carbonating calcium derived from blast furnace slag. Energy, ${33}\left( 9\right) ,{1461} - {1467}$ .
Faruque Hasan, M. M., First, E. L., Boukouvala, F., & Floudas, C. A. (2014). A novel framework for carbon capture, utilization, and sequestration, CCUS. In Proceedings of the 8th International Conference on Foundations of Computer-Aided Process Design (pp. 98-107).
Favre, E. (2011). Membrane processes and postcombustion carbon dioxide capture: Challenges and prospects. Chemical Engineering Journal, 171(3), 782-793.
Figueroa, J. D., Fout, T., Plasynski, S., McIlvried, H., & Srivastava, R. D. (2008). Advances in ${\mathrm{{CO}}}_{2}$ capture technology—The U.S. department of energy’s carbon sequestration program. International Journal of Greenhouse Gas Control, 2(1), 9-20.
Fogelholm, C. J., Tveit, T. M., Eloneva, S., Said, A., Revitzer, H., Zevenhoven, R., … & Fält, M. (2009). Reduction of ${\mathrm{{CO}}}_{2}$ emissions and utilization of slag products by producing calcium-based products from carbonate-free slag products (Slag2PCC Plus) (pp. 314- 323). Helsinki, Finland.
Fu ZX, Liu SJ, Fu X. 2010. A method of carbon dioxide injec- tion to Blast Furnace. Chinese Patent, CN101871026 (in Chinese).
Gale, J. (2003). Geological storage of ${\mathrm{{CO}}}_{2}$ : What’s known, where are the gaps and what more needs to be done. In aper presented at the Greenhouse Gas Control Technologies-6th International Conference.
Gao, L., Fang, M., Li, H., & Hetland, J. (2011). Cost analysis of ${\mathrm{{CO}}}_{2}$ , transportation: Case study in china. Energy Procedia, 4(22), 5974-5981.
GCCSI (Global CCS Institue). (2017a). Yanchang integrated carbon capture and storage demonstration project.
GCCSI (Global CCS Institue). (2017b), Large scale CCS projects
Giorno, L., Drioli, E., & Strathmann, H. (2015). The principle of gas separation. In Encyclopedia of membranes (pp. 1-6).
Gu, Y. L., Wang, H. J., Zhu, R., Wang, J., Lv, M., & Wang, H. (2014). Study on experiment and mechanism of bottom blowing ${\mathrm{{CO}}}_{2}$ during the LF refining process. Steel Research International, 85(4), 589-598.
Gulyaev, M. P, & Filippov, V. V. (2001). The first systems of bottom blowing with inert-gas in electric arc furnace. Proceedings of the 6-th Congress of Steelmakers (p. 308).
Gunter, W. D., Perkins, E. H., & McCann, T. J. (1993). Aquifer disposal of ${\mathrm{{CO}}}_{2}$ -rich gases: reaction design for added capacity. Energy Conversion and Management, 34(9-11), 941- 948.
Guo, M. X., & Chen, X. W. (1993). Action mechanism of bottom- blown ${\mathrm{{CO}}}_{2}$ in the bath of combined-blown converter. Journal of Iron and Steel Research, 1, 9-14. (in Chinese).
Guo, X. Q, Yuan, L., Zhang, J., Wu, S. Q. (2010). A method of CO ${}_{2}$ utilization as the transmission medium of pulverized coal injection into BF (Chinese Patent, CN 102382915) (in Chinese).
Hao, G.-P., Li, W.-C., & Lu, A.-H. (2011). Novel porous solids for carbon dioxide capture. Journal of Materials Chemistry, 21(18).
Hara, R. D. O., Spence, A. G. R., & Eissenwasser, J. D. (1986). Carbon dioxide shrouding and purging at IPSCO Melt shop. Iron Steelmaker, 3, 24-28.
He, P., Zhang, D. M., & Deng, K. W. (1992). Gas stirring technology with bottom blowing in EAF. Iron Steel, 9, 65-70. (in Chinese).
Hong, Y. G. (2012). Experimental study on desilication of hot metal with carbon dioxide injection (Master thesis). Northeastern University (in Chinese).
IEA. (2016). 20 years of carbon capture and storage: Accelerating future deployment. France: International Energy Agency.
Inagaki, M., & Kang, F. (2014). Engineering and applications of carbon materials. In Materials science and engineering of carbon: Fundamentals (pp. 219-525).
Ismail, A. F., Kusworo, T. D., Mustafa, A., & Hasbullah, H. (2005). Understanding the solution-diffusion mechanism in gas separation membrane for engineering students. In Paper presented at the Regional Conference on Engineering Education RCEE.
Jahangiri, H. R., & Zhang, D. (2012). Ensemble based co-optimization of carbon dioxide sequestration and enhanced oil recovery. International Journal of Greenhouse Gas Control, 8(5), 22-33.
Jin, G. L. (1985). Application study of LD converter bottom blowing N2-CO2. Steelmaking., 3, 96-100. (in Chinese).
Jin, R. J., Zhu, R., Feng, L. X., & Yin, Z. J. (2007). Experimental study of steelmaking with ${\mathrm{{CO}}}_{2}$ and ${\mathrm{O}}_{2}$ mixed blowing. Journal of University of Science and Technology Beijing, 29(S1), 77-80. (in Chinese).
Kim, H., Lee, J., Lee, S., Lee, I.-B., Park, J.-H., & Han, J. (2015). Economic process design for separation of ${\mathrm{{CO}}}_{2}$ from the off-gas in ironmaking and steelmaking plants. Energy,88, 756-764.
Kovscek, A. R. (2002). Screening criteria for ${\mathrm{{CO}}}_{2}$ storage in oil reservoirs. Petroleum Science and Technology, 20(7-8), 841-866.
Kunzler, C., Alves, N., Pereira, E., Nienczewski, J., Ligabue, R., Einloft, S., & Dullius, J. (2011). ${\mathrm{{CO}}}_{2}$ storage with indirect carbonation using industrial waste. Energy Procedia,4, 1010-1017.
Larsen, J. W. (2004). The effects of dissolved ${\mathrm{{CO}}}_{2}$ on coal structure and properties. International Journal of Coal Geology, 57(1), 63-70.
Lee, S.-Y., & Park, S.-J. (2015). A review on solid adsorbents for carbon dioxide capture. Journal of Industrial and Engineering Chemistry, 23, 1-11.
Leung, D. Y., Caramanna, G., & Maroto-Valer, M. M. (2014). An overview of current status of carbon dioxide capture and storage technologies. Renewable and Sustainable Energy Reviews, 39, 426-443.
Li, C. B., & Han, Y. (1996). The application of the combined blowing technique with ${\mathrm{{CO}}}_{2}$ bottom blowing to the converters of Anshan Iron and Steel Company. Steelmaking., 4, 19-25. (in Chinese).
Li, Q., Liu, R. Z., & Zhu, R. (2015a). Research on decarburization and chromium conservation by blowing carbon dioxide. Industrial Heating, 44(4), 24-26. (in Chinese).
Li, Q., Wang, H., & Zhu, R. (2015b). Experimental study on ${\mathrm{{CO}}}_{2}$ as shield gas of continuous casting. Continuous Casting, 40(2), 5-9. (in Chinese).
Li, X., Liu, Y., Bai, B., & Fang, Z. (2006). Ranking and screening of ${\mathrm{{CO}}}_{2}$ saline aquifer storage zones in china. Chinese Journal of Rock Mechanics & Engineering, 25(5), 963-968.
Liu, L. S. (1983). Study on ${\mathrm{{CO}}}_{2}$ being protection media for side- blown oxygen lance in converter. Hebei Metall., 3, 80-81. (in Chinese).
Liu, H., & Gallagher, K. S. (2011). Preparing to ramp up large-scale CCS demonstrations: An engineering-economic assessment of ${\mathrm{{CO}}}_{2}$ , pipeline transportation in china. International Journal of Greenhouse Gas Control, 5(4), 798-804.
Liu, Y. F., Li, X. C., & Bai, B. (2005). Preliminary estimation of ${\mathrm{{CO}}}_{2}$ storage capacity of coalbeds in china. Chinese Journal of Rock Mechanics & Engineering, 24(16), 2947-2952.
Lv, M., Zhu, R., Bi, X. R., & Lin, T. C. (2011a). Research on ${\mathrm{{CO}}}_{2}$ application in BOF steelmaking process. Journal of University of Science and Technology Beijing, S1, 126- 130. (in Chinese).
Lv, M., Zhu, R., & Bi, X. R. (2011b). Fundamental research on dephosphorization of BOF by COMI steelmaking process. Iron Steel, 8, 31-35. (in Chinese).
Mccollum, D. L., & Ogden, J. M. (2006). Techno-economic models for carbon dioxide compression, transport, and storage & correlations for estimating carbon dioxide density and viscosity. In Working Paper Series. Institute of Transportation Studies.
McCoy, S. T., & Rubin, E. S. (2008). An engineering-economic model of pipeline transport of ${\mathrm{{CO}}}_{2}$ with application to carbon capture and storage. International Journal of Greenhouse Gas Control, 2(2), 219-229.
Merkel, T. C., Lin, H., Wei, X., & Baker, R. (2010). Power plant post-combustion carbon dioxide capture: An opportunity for membranes. Journal of Membrane Science, 359(1-2), 126-139.
Metz, B., (2005). “IPCC Special Report on Carbon Dioxide Capture and Storage.” Economics & Politics of Climate Change.
Metz, B., Davidson, O., & De Coninck, H. (Eds.). (2005). Carbon dioxide capture and storage: special report of the intergovernmental panel on climate change. Cambridge University Press.
Mohitpour, M., Golshan, H., Murray, A., (2003). In: Pipeline design & construction (1st ed.). ASME Press.
Mondal, M. K., Balsora, H. K., & Varshney, P. (2012). Progress and trends in ${\mathrm{{CO}}}_{2}$ capture/separation technologies: A review. Energy, 46(1), 431-441.
Ning, X. J., Yin, Z. J., Yi, C., Zhu, R., & Dong, K. (2009). Experimental research on dust reduction in steelmaking by ${\mathrm{{CO}}}_{2}$ . Steelmaking, 5, 32-34. (in Chinese).
Normanton, A. S. (Steel Times), Wang, X. C. (Translate). (1990). Application of ${\mathrm{{CO}}}_{2}$ in steelmaking process in English steel industry (Vol. 2, pp. 21-27). Wisco Technologies (in Chinese).
Oelkers, E. H., Gislason, S. R., & Matter, J. (2008). Mineral carbonation of ${\mathrm{{CO}}}_{2}$ . Elements, 4(5), 333-337.
Olajire, A. A. (2010). ${\mathrm{{CO}}}_{2}$ capture and separation technologies for end-of-pipe applications-A review. Energy, 35(6), 2610-2628.
Paules, J. R, Grieshaber, K. W, & Martines, M. L. (1987). Ladle stirring and stream shrouding with carbon diodide at Armeco’s Midwestern Steel Division. In 70th Steelmaking Conference Proceedings, Mar 29-Apr 1, 1987 (pp. 129-132), Pittsburgh, USA.
Paules, J. R. (1987). Ladle stirring and stream shrouding with ${\mathrm{{CO}}}_{2}$ at Armco’s Midwestern Steel Division. In The 70th Steelmaking Conference Proceedings Mar 29-Apr 1 1987, Pittsburgh, America.
Rawlins, C. H., Richards, V. L., Peaslee, K. D., Lekakh, S. N. (2006). Steelmaking slag as a permanent sequestration sink for carbon dioxide. Steel Times International, 30(7), 25-26, 28.
Rice, D. D., Law, B. E., & Clayton, J. L. (1993). Coalbed gas—An undeveloped resource. US Geological Survey Professional Paper, 1570, 389-404.
Richards, V. L., Peaslee, K., Smith, J. D. (2008). Geological sequestration of ${\mathrm{{CO}}}_{2}$ by hydrous carbonate formation with reclaimed slag. TRP 9955 (307 pp). Oak Ridge, TN, USA: Office of Scientific and Technical Information. www.osti.gov/bridge.
Seoane, B., Coronas, J., Gascon, I., Etxeberria Benavides, M., Karvan, O., Caro, J., Kapteijn, F., & Gascon, J. (2015). Metal-organic framework based mixed matrix membranes: A solution for highly efficient ${\mathrm{{CO}}}_{2}$ capture? Chemical Society Reviews,44(8),2421-2454.
Song, J., & Zhang, D. (2013). Comprehensive review of caprock-sealing mechanisms for geologic carbon sequestration. Environmental Science and Technology, 47, 9-22.
Spigarelli, B. P., & Kawatra, S. K. (2013). Opportunities and challenges in carbon dioxide capture. Journal of CO2 Utilization, 1, 69-87.
Suzuki, K., Kumagai, T., & Sano, N. (1992). Removal of boron from metallurgical-grade silicon by applying the plasma treatment. ISIJ International, 32(5), 630-634.
Svensson, R., Odenberger, M., Johnsson, F., & Strömberg, L. (2004). Transportation system for ${\mathrm{{CO}}}_{2}$ - application to carbon capture and storage.Energy Conversion and Management, 45(15-16), 2343-2353.
Tang, F. P, Zhao, G., Li, D. G., Cao, D., & Zhao, C. L. (2011). A smelting method for stainless steel production with ${\mathrm{{CO}}}_{2}$ blowing in AOD (Chinese patent, CN102146499) (in Chinese).
Teng, Y., & Zhang, D. (2018). Long-term viability of carbon sequestration in deep-sea sediments. Science Advances, 4.
Teir, S., Eloneva, S., Fogelholm, C.-J., & Zevenhoven, R. (2007). Dissolution of steelmaking slags in acetic acid for precipitated calcium carbonate production. Energy, 32(4), 528-539.
Uibu, M., Kuusik, R., Andreas, L., & Kirsimäe, K. (2011). The ${\mathrm{{CO}}}_{2}$ -binding by Ca-Mg-silicates in direct aqueous carbonation of oil shale ash and steel slag. Energy Procedia, 4, 925-932.
Van Wijngaarden, M. J., & Pieterse, A. T. (1994). Bottom-stirring in an electric-arc furnace: Performance results at Iscor Vereeniging Works. Journal of the Southern African Institute of Mining and Metallurgy, 1, 27-34.
Vandeginste, V., & Piessens, K. (2008). Pipeline design for a least-cost router application for ${\mathrm{{CO}}}_{2}$ , transport in the ${\mathrm{{CO}}}_{2}$ , sequestration cycle. International Journal of Greenhouse Gas Control, 2(4), 571-581.
Wang, H., Zhu, R., & Liu, R. Z. (2014). CO2 application on bottom blowing in EAF. Industrial Heating, 43(2), 12-14. (in Chinese).
Wang, H. J., Teng, L. D., Seetharaman, S. (2012). Heat and material balance calculations with introduction of ${\mathrm{{CO}}}_{2}$ during EAF processes. In: 5th International Congress on Steelmaking Technology, October 1-3, 2012, Dresden
Wang, H. J., Viswanathan, N. N., Ballal, N. B., & Seetharaman, S. (2009). Modelling of reactions between gas bubble and molten metal bath-experimental validation in the case of decar-burization of Fe-Cr-C melts. High Temp Mater Process, 28(6), 407-419.
Wang, H. J., Viswanathan, N. N., Ballal, N. B., & Seetharaman, S. (2010). Modelling of physico-chemical phenomena between gas inside a bubble and liquid metal. Journal of Chemical Reaction Engineering, 8, 45-54.
Wang, S. L. (1986). Metallurgical behaviours of gas bottom blowing in converter. Steelmaking, 3, 24-30. (in Chinese).
Wang, S. L. (1989). Gas supply model of bottom blowing ${\mathrm{{CO}}}_{2}$ in converter. Steelmaking., 4, 1-7. (in Chinese).
Wilberforce, T., Baroutaji, A., Soudan, B., Al-Alami, A. H., & Olabi, A. G. (2019). Outlook of carbon capture technology and challenges. Science of the Total Environment, 657, 56-72.
Wilcox, J., Haghpanah, R., Rupp, E. C., He, J., & Lee, K. (2014). Advancing adsorption and membrane separation processes for the gigaton carbon capture challenge. Annual Review of Chemical and Biomolecular Engineering, 5, 479-505.
Wu, J. J., Li, Y., Ma, W., Liu, K., Wei, K., Xie, K., Yang, B., & Dai, Y. (2014). Impurities removal from metallurgical grade silicon using gas blowing refining techniques. SILICON, 6(1), 79-85.
Wu, J.-J., Ma, W.-H., Yang, B., Dai, Y.-N., & Morita, K. (2009). Boron removal from metallurgical grade silicon by oxidizing refining. Transactions of Nonferrous Metals Society of China, 19(2), 463-467.
Xiuzhang, W. (2014). Shenhua Group’s carbon capture and storage (CCS) demonstration. Mining Report, 150(1-2), 81-84.
Yi, C., Zhu, R., Yin, Z. J., & Hou, N. N. (2009). Experimental study of COMI steel making process based on 30t converter. Chinese Journal of Proceeding Engineering, S1, 222-225. (in Chinese).
Yin, Z. J., Zhu, R., & Yi, C. (2009). Fundamental research on controlling BOF dust by COMI steelmaking process. Iron Steel, 10, 92-94. (in Chinese).
Yu, H. C, Wang, H. J., & Chu, S. J. (2015). Fundamental investigations on M-LCFeCr smelting by introducing ${\mathrm{{CO}}}_{2}$ . In The 6th International Congress on the Science and Technology of Steelmaking (ICS2015), May 12-14, 2015, Beijing.
Yu, H. C. (2015). Master thesis. Beijing: University of Science and Technology (in Chinese).
Yuan, Z. F, Zhao, H. X., Pan, Y. F. (2007). Method for CO2being applied in slag splashing in converter (Chinese patent). ZL200610165219.2 (in Chinese).
Zhang, Z. X., Wang, G. X., Massarotto, P., & Rudolph, V. (2006). Optimization of pipeline transport for ${\mathrm{{CO}}}_{2}$ sequestration. Energy Conversion and Management,47(6),702-715.
Zhao, H.-X., Yuan, Z.-F., Wang, W.-J., Pan, Y.-F., & Li, S.-Q. (2010). A novel method of recycling ${\mathrm{{CO}}}_{2}$ for slag splashing in converter. Journal of Iron and Steel Research International, 17, 11-16.
Zhao, X. J. (1995). Development of bottom blowing technology of EAF abroad. Steeltubes, 5, 12-15. (in Chinese).
Zhu, R., Lv, M., Lin, T. C. (2012). Application research of carbon dioxide during the steelmaking process. In 5th International Congress on Steelmaking Technology, October 1-3, 2012, Dresden.
Zhu, R., Yi, C., Chen, B. Y., & Wang, C. Y. (2010). Research on inner circulation control of steelmaking dust by COMI process. Energy Metall Industries, 1, 48-51. (in Chinese).
CCUS: What is It? How Does It Cost? Techno-Economic Analysis
碳捕获、利用与封存技术(CCUS):是什么?成本几何?技术经济分析
Qianguo Lin, Xi Liang, Ming Lei, Y. M. Zhang, Y. R. Pan, and N. Wang
林谦国、梁希、雷鸣、张义明、潘耀荣、王宁
${\mathrm{{CO}}}_{2}$ capture, utilization and storage technology (CCUS) is one of the few technologies that can help industry achieve large-scale ${\mathrm{{CO}}}_{2}$ emission reductions. Currently, huge investment and operating costs, as well as lack of financially viable business models are generally seen as the main obstacles to the development of CCUS. According to IEA estimates, currently for CCS project to sequester one ton of ${\mathrm{{CO}}}_{2}$ emissions, it would cost as high as $\$ {200} - {300}$ on average, and that cost varies greatly, depending on local and project-specific engineering conditions. A full-chain CCUS project is particularly complex, involving multiple interactions between carbon capture, transportation, utilization and storage activities. Even within an iron or steel plant, CCUS involves not only multiple gas sources in the capture process, but also different capture technologies for different gas sources. That being the case, cost estimates in connection with tech-performance of CCUS are all the more important, because they can help decision-makers understand and identify cost-effective pathways, when making decisions about deploying CCUS projects.
${\mathrm{{CO}}}_{2}$捕获、利用与封存技术(CCUS)是少数能够助力行业实现大规模${\mathrm{{CO}}}_{2}$减排的技术之一。当前,巨额的投资与运营成本,以及缺乏具备财务可行性的商业模式,通常被视作CCUS发展的主要障碍。据国际能源署估算,目前对于碳捕集与封存(CCS)项目而言,封存一吨${\mathrm{{CO}}}_{2}$排放,平均成本高达$\$ {200} - {300}$,且该成本因当地及项目特定工程条件而差异巨大。一个全链条的CCUS项目尤为复杂,涉及碳捕获、运输、利用与封存活动之间的多重相互作用。即便在钢铁厂内部,CCUS不仅在捕获过程中涉及多种气源,而且针对不同气源采用不同的捕获技术。即便如此,与CCUS技术性能相关的成本估算愈发重要,因为这有助于决策者在做出部署CCUS项目的决策时,理解并识别出具有成本效益的路径。
The original version of this chapter was revised: A sentence has been added on page 109. The correction to this chapter can be found at https://doi.org/10.1007/978-981-16-4310-1_8.
本章的原始版本已修订:第109页新增了一句话。本章的勘误可在https://doi.org/10.1007/978-981-16-4310-1_8查看。
M. Lei (★)
雷鸣(★)
Guanghua School of Management, Peking University, Beijing, China
北京大学光华管理学院,中国北京
Q. Lin $\cdot$ X. Liang
林谦国$\cdot$梁希
University of Edinburgh Business School, Edinburgh, U.K.
爱丁堡大学商学院,英国爱丁堡
Y. M. Zhang · Y. R. Pan · N. Wang
张义明·潘耀荣·王宁
North-China Electric Power University, Beijing, China
华北电力大学,中国北京
Thus, building upon the previous chapter, in Chapter 4, we attempt a systematic techno-economic analysis of the efficacy of different carbon capture technologies for major sources of carbon emissions in the steel sector.
因此,基于上一章内容,在第4章中,我们尝试对钢铁行业主要碳排放源的不同碳捕获技术的效能进行系统的技术经济分析。
Chapter 4 is organized into four sections. Section 1 identifies the main ${\mathrm{{CO}}}_{2}$ emission sources of a typical production process of China’s iron/steel industry. Section 2 discusses suitable carbon capture technologies for each emission source. Section 3 conducts a systematic techno-economic analysis of different capture methods for each emission source. Section 4 concludes with a caveat, calling for attention to local and firm-specific engineering conditions.
第4章分为四个部分。第1部分确定了中国钢铁行业典型生产流程的主要${\mathrm{{CO}}}_{2}$排放源。第2部分讨论了各排放源适用的碳捕获技术。第3部分对各排放源的不同捕获方法进行了系统技术经济分析。第4部分给出了一项提醒作为结论,呼吁关注当地及企业特定的工程条件。
1 Section 1
1 第1节
1.1 Main ${\mathrm{{CO}}}_{2}$ Emission Sources from Iron/steel Industry
1.1 钢铁行业主要的${\mathrm{{CO}}}_{2}$排放源
The steel/iron production process can be divided into a main process and an auxiliary process. The main process can be further categorized into long process (BF/BOF) and short process (EAF). The long process (BF/BOF) starts with raw materials such as iron ore, through the processes of mining, milling of ores, blast furnace, converter secondary metallurgy, continuous casting, steel rolling and other processes. The short process (EAF) refers to the use of scrap steel as raw materials to make steel product, though casting of electric furnace, ladle furnace, continuous rolling and other processes. The auxiliary process refers to the production process which has a great influence on the environmental, such as coking, boiler, oxygen production, fuel gas processing, energy discharge and internal transportation. At present, the long process is mainly adopted by China’s iron/steel industry; crude steel production accounts for 90% of total steel production in China (Cui, 2016); in addition, the per ton steel ${\mathrm{{CO}}}_{2}$ emission of crude steel produced by a short process is far less than that of crude steel produced by a long process $\left( {\mathrm{{CO}}}_{2}\right.$ emission associated with converter process is 5 times than that associated with electrical furnace process (Ran & Weng, 2006). Therefore, the ${\mathrm{{CO}}}_{2}$ produced by long process production process is the main ${\mathrm{{CO}}}_{2}$ emission source of China’s steel/iron industry.
钢铁生产过程可分为主流程和辅助流程。主流程可进一步分为长流程(高炉/转炉)和短流程(电弧炉)。长流程(高炉/转炉)以铁矿石等原料开始,经过采矿、矿石研磨、高炉、转炉二次冶金、连铸、轧钢等工序。短流程(电弧炉)是指以废钢为原料,通过电炉熔炼、钢包精炼炉、连轧等工序生产钢材。辅助流程是指对环境影响较大的生产流程,如焦化、锅炉、制氧、燃气处理、能源排放和内部运输等。目前,中国钢铁行业主要采用长流程;粗钢产量占中国钢铁总产量的90%(Cui,2016);此外,短流程生产的粗钢每吨${\mathrm{{CO}}}_{2}$排放量远低于长流程生产的粗钢$\left( {\mathrm{{CO}}}_{2}\right.$转炉工艺的排放量是电炉工艺排放量的5倍(Ran & Weng,2006)。因此,长流程生产过程产生的${\mathrm{{CO}}}_{2}$是中国钢铁行业主要的${\mathrm{{CO}}}_{2}$排放源。
The production processes of a long process steel/iron industry mainly include 5 processes: coking, sintering, iron-making, steel-making and steel rolling. The iron-making process has three types: blast furnace iron-making, direct-reduction iron-making and molten reduction technology. The steel-making process has two types, which is converter steel-making and electric furnace steel-making. In the process of coking, sintering, iron-making, steel-making and rolling steel, fuel coal, coking coal, coke, natural gas and fuel oil are not only the source of energy, but also raw materials. Some part of carbon in these energy and material sources is converted and released in the form of ${\mathrm{{CO}}}_{2}$ by the way of reduction or oxidation reaction in the whole production process. The main ${\mathrm{{CO}}}_{2}$ emission sources are released from units include lime kiln, coke oven, hot blast furnace, blast furnace, converter and self-provided power plant.
长流程钢铁行业的生产过程主要包括5个工序:焦化、烧结、炼铁、炼钢和轧钢。炼铁工艺有三种类型:高炉炼铁、直接还原炼铁和熔融还原技术。炼钢工艺有两种类型,即转炉炼钢和电炉炼钢。在焦化、烧结、炼铁、炼钢和轧钢过程中,燃料煤、焦煤、焦炭、天然气和燃料油不仅是能源来源,也是原料。这些能源和原料中的一部分碳在整个生产过程中通过还原或氧化反应以${\mathrm{{CO}}}_{2}$的形式转化并释放出来。主要的${\mathrm{{CO}}}_{2}$排放源来自石灰窑、焦炉、热风炉、高炉、转炉和自备电厂等装置。
1.2 ${\mathrm{{CO}}}_{2}$ Emission from Lime Kiln
1.2 石灰窑的${\mathrm{{CO}}}_{2}$排放
In iron-making process, lime kiln is used to produce lime as flux and slag materials to be used in blast furnace iron-making and converter iron-making processes to remove harmful elements from smelting, such as sulphur, silicon, phosphorus other impurities. Lime is formed by the limestone calcination, the main component of limestone is calcium carbonate. The basic principle of burning limestone can be expressed by the following chemical reaction equation (Eq. 1):
在炼铁过程中,石灰窑用于生产石灰,作为熔剂和造渣材料,用于高炉炼铁和转炉炼铁过程,以去除冶炼中的有害元素,如硫、硅、磷等其他杂质。石灰由石灰石煅烧而成,石灰石的主要成分是碳酸钙。石灰石燃烧的基本原理可以用以下化学反应方程式(式1)表示:
$$ {\mathrm{{CaCO}}}_{3}\xrightarrow[]{ > {900}^{ \circ }\mathrm{C}}\mathrm{{CaO}} + \mathrm{{CO}} \uparrow \tag{1} $$The limestone and air are preheated to about ${900}{}^{ \circ }\mathrm{C}$ in the lime kiln preheater. After lime produced, the lime (product) will be cooled to below about ${100}{}^{ \circ }\mathrm{C}$ by cooling gas. After the cooling gas enters a roast area to mix with the exhaust gas from combustion, the temperature of mixed gas will reach about ${900}{}^{ \circ }\mathrm{C}$ . The mixed gas is then recycled and reused for heating limestone and air in the subsequent limestone preheating process. After the preheating process, the temperature of flue gas is reduced to ${60} - {80}^{ \circ }\mathrm{C}$ . Although when the breakdown of limestone can release about ${40}\%$ of its weight in the form of ${\mathrm{{CO}}}_{2}$ , after mixing with exhaust gas from combustion and circulating, ${\mathrm{{CO}}}_{2}$ content in the flue gas will be significantly decreased. ${\mathrm{{CO}}}_{2}$ from different lime kiln unit may have different concentrations.
石灰石和空气在石灰窑预热器中预热至约${900}{}^{ \circ }\mathrm{C}$。石灰生产出来后,石灰(产品)将通过冷却气体冷却至约${100}{}^{ \circ }\mathrm{C}$以下。冷却气体进入焙烧区与燃烧废气混合后,混合气体温度将达到约${900}{}^{ \circ }\mathrm{C}$。然后混合气体被循环利用,用于后续石灰石预热过程中加热石灰石和空气。预热过程后,烟气温度降至${60} - {80}^{ \circ }\mathrm{C}$。虽然石灰石分解时会以${\mathrm{{CO}}}_{2}$的形式释放出约其重量${40}\%$的物质,但与燃烧废气混合并循环后,烟气中的${\mathrm{{CO}}}_{2}$含量将显著降低。不同石灰窑单元的${\mathrm{{CO}}}_{2}$浓度可能不同。
According to the report of Applying carbon capture and storage to a Chinese steel plant which is prepared for Global Carbon Capture and Storage Institute Ltd by Toshiba International Corp Pty Ltd/Toshiba Corporation in collaboration with Tongfang Environment Co. Ltd, China Shougang Caofeidian plant has 6 sets shaft lime kilns, used for production of lime needed by steel mill. The flue gas composition of #4 lime kiln from Caofeidian plant is given in Table 1, indicating 19.3% ${\mathrm{{CO}}}_{2}$ concentration. Shen (2008) reported that the ${\mathrm{{CO}}}_{2}$ concentration of flue gas of a typical limestone kilns outlet in the integrated iron and steel enterprise was 15-21%.
根据东芝国际公司/东芝公司与同方环境股份有限公司合作,为全球碳捕集与封存研究所有限公司编写的《将碳捕集与封存应用于中国钢铁厂》报告,中国首钢曹妃甸工厂有6座竖炉石灰窑,用于生产钢厂所需的石灰。曹妃甸工厂4号石灰窑的烟气成分见表1,显示${\mathrm{{CO}}}_{2}$浓度为19.3%。沈(2008年)报告称,综合钢铁企业中典型石灰石窑出口烟气的${\mathrm{{CO}}}_{2}$浓度为15 - 21%。
Table 1 Flue gas composition of #4 Lime Kiln in Shougang Jingtang
表1首钢京唐4号石灰窑烟气成分
| Flow rate ${\mathrm{m}}^{3}\mathrm{\;N}/\mathrm{h}$ | Temperature ℃ | Concentration $\left( {\mathrm{{CO}}}_{2}\right)$ Vol.% | ${\mathrm{{CO}}}_{2}$ emission t/d | kt/year | |
| #4 lime kiln | 75,304 | 110 | 19.3 | 685 | 205 |
1.3 CO2 Emission from Coke Oven
1.3 焦炉的二氧化碳排放
The coke oven flue gas from steel/iron plant is the exhaust gas produced by combustion and discharged through a coke oven chimney. The mixture of coke oven gas and blast furnace gas is generally used for coke oven heating by integrated iron and steel enterprises. Accordingly, the ${\mathrm{{CO}}}_{2}$ concentration is mainly affected by the combustion condition and the composition of combustion feed gas. According to the report of Applying carbon capture and storage to a Chinese steel plant which is prepared for Global Carbon Capture and Storage Institute Ltd by Toshiba International Corp Pty Ltd/Toshiba Corporation in collaboration with Tongfang Environment Co. Ltd, the ${\mathrm{{CO}}}_{2}$ concentration of the combustion flue gas from coke oven in China Shougang Jingtang was ${11}\%$ . The report of Global Carbon Capture and Storage presented a concentration range of 10-15% (Global CCS Institute, 2016).
钢铁厂的焦炉烟道气是燃烧产生的废气,通过焦炉烟囱排放。焦炉煤气和高炉煤气的混合物通常被钢铁联合企业用于焦炉加热。因此,${\mathrm{{CO}}}_{2}$浓度主要受燃烧条件和燃烧原料气成分的影响。根据东芝国际公司/东芝公司与同方环境有限公司合作,为全球碳捕集与封存研究所编写的《将碳捕集与封存应用于中国钢铁厂》报告,中国首钢京唐焦炉燃烧烟道气的${\mathrm{{CO}}}_{2}$浓度为${11}\%$。全球碳捕集与封存报告给出的浓度范围为10 - 15%(全球CCS研究所,2016年)。
There is another gas source related to coking produced by coking process. It is called raw coke oven gas or raw coal gas. The raw coal gas can be purified though a coke oven gas purification system (Fig. 1). Coke oven gas purification process is differentiated mainly based on different desulphurization and deamination configurations. Generally, there are two kinds desulfurization system: dry desulfurization and wet desulfurization. Wet desulfurization process can be further categorized into two types: wet oxidation process and wet absorption process. The wet absorption process has the function of removing ${\mathrm{{CO}}}_{2}$ simultaneously, leading to a low ${\mathrm{{CO}}}_{2}$ concentration in the purified flue gas.
还有一种与焦化过程相关的气体来源,称为焦炉荒煤气或荒煤气。荒煤气可以通过焦炉煤气净化系统进行净化(图1)。焦炉煤气净化工艺主要根据不同的脱硫和脱氨配置进行区分。一般来说,有两种脱硫系统:干法脱硫和湿法脱硫。湿法脱硫工艺又可进一步分为两类:湿式氧化法和湿式吸收法。湿式吸收法具有同时去除${\mathrm{{CO}}}_{2}$的功能,导致净化后的烟道气中${\mathrm{{CO}}}_{2}$浓度较低。
The Sulfiban method of wet absorption process was applied in the coal gas refining system in Baosteel phase II which was put into operation in May 1997. Through an intermediate cooling tower, the coal gas after naphthalene removed enters an ammonia absorption facility, where a 75% of ammonium dihydrogen phosphate is used as absorption solution. The rich solution is ammonium hydrogen phosphate. Ammonia solution with concentration of ${18}\%$ is obtained after desorption. Anhydrous ammonia with the concentration of 99.8% is finally obtained after further pressurized and concentrated. The absorbents can be recycled after desorption. The coal gas which absorbed ammonia enters a final cooling tower after dephenolization and decyanation. The coal gas without ammonia enters a benzol scrubber to remove crude benzene. The gas is then delivered to a gas cabinet for storage after desulfuration and decyanation processes. The sulfur enriched solution is desorbed in a desorption facility. The obtained ${\mathrm{H}}_{2}\mathrm{\;S},\mathrm{{HCN}}$ and ${\mathrm{{CO}}}_{2}$ are then sent to combustion furnace to generate ${\mathrm{{SO}}}_{2}$ and ${\mathrm{{NO}}}_{\mathrm{x}}$ .
湿式吸收法的苏尔菲班法应用于1997年5月投产的宝钢二期煤气精制系统。经过中间冷却塔,脱萘后的煤气进入氨吸收设施,其中75%的磷酸二氢铵用作吸收液。富液为磷酸氢铵。解吸后得到浓度为${18}\%$的氨溶液。进一步加压浓缩后最终得到浓度为99.8%的无水氨。吸收剂解吸后可循环使用。吸收氨后的煤气在脱酚脱氰后进入最终冷却塔。不含氨的煤气进入苯洗涤器以去除粗苯。然后,气体在脱硫脱氰后输送到气柜进行储存。富硫溶液在解吸设施中解吸。得到的${\mathrm{H}}_{2}\mathrm{\;S},\mathrm{{HCN}}$和${\mathrm{{CO}}}_{2}$然后被送入燃烧炉以产生${\mathrm{{SO}}}_{2}$和${\mathrm{{NO}}}_{\mathrm{x}}$。
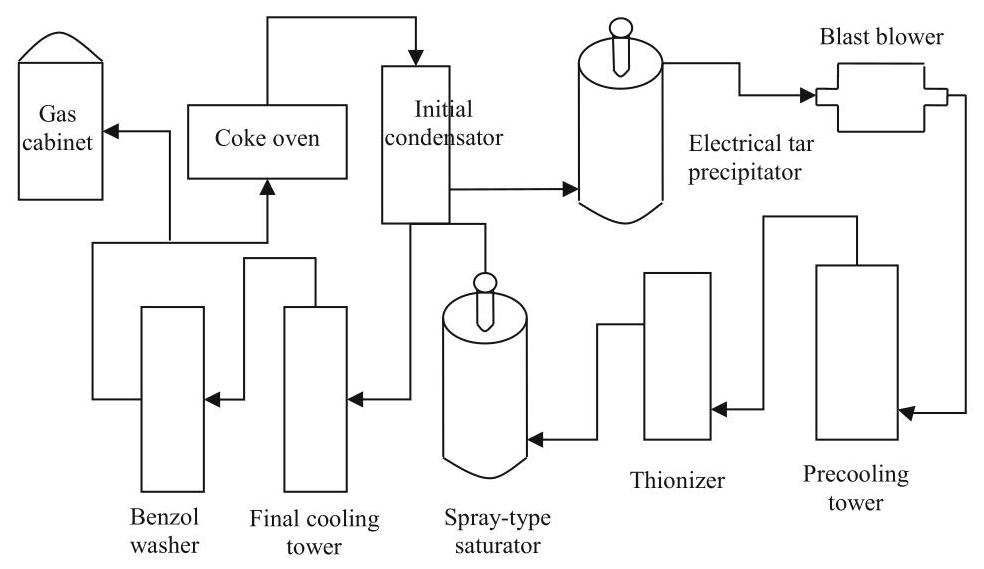
Fig. 1 Coke oven gas purification system
图1 焦炉煤气净化系统
The composition of a typical purified coal gas is illustrated in Table 3. Because ${\mathrm{{CO}}}_{2}$ is partially removed by ammonia absorption process, the concentration of ${\mathrm{{CO}}}_{2}$ is as low as ${2.1}\%$ . Comparing coke oven flue gas and coke oven gas, the former is a combustion product discharged through a coke oven chimney, its ${\mathrm{{CO}}}_{2}$ concentration is relatively high; the latter is a direct product produced in the coking process of coal, its ${\mathrm{{CO}}}_{2}$ concentration is relatively low particularly after absorption of ammonia. Therefore, coke oven flue gas is more suitable for the application of carbon capture technology than the coke oven gas (Table 2).
典型净化煤气的成分见表3。由于${\mathrm{{CO}}}_{2}$通过氨吸收过程被部分去除,${\mathrm{{CO}}}_{2}$的浓度低至${2.1}\%$。比较焦炉烟道气和焦炉煤气,前者是通过焦炉烟囱排放的燃烧产物,其${\mathrm{{CO}}}_{2}$浓度相对较高;后者是煤炭焦化过程中直接产生的产物,其${\mathrm{{CO}}}_{2}$浓度相对较低,特别是在氨吸收之后。因此,焦炉烟道气比焦炉煤气更适合应用碳捕集技术(表2)。
Table 2 Composition of typical coke oven gas
表2 典型焦炉煤气的成分
| Composition | CO | ${\mathrm{{CO}}}_{2}$ | ${\mathrm{H}}_{2}$ | ${\mathrm{N}}_{2}$ | ${\mathrm{{CH}}}_{4}$ | ${\mathrm{C}}_{2}{\mathrm{H}}_{4}$ | ${\mathrm{C}}_{2}{\mathrm{H}}_{6}$ | ${\mathrm{C}}_{3}{\mathrm{H}}_{6}$ | ${\mathrm{O}}_{2}$ | ${\mathrm{H}}_{2}\mathrm{O}$ |
| Coke oven gas | 5.9 | 2.1 | 58.8 | 3.8 | 25.6 | 2.3 | 0.9 | 0.2 | 0.4 | saturation |
Table 3 Operating condition at TRT inlet and outlet
表3 透平膨胀机进出口运行工况
| Item | Numerical value |
| Blast furnace top pressure | 0.20 MPa |
| TRT inlet pressure | 0.17 MPa |
| TRT outlet pressure | 0.01 MPa |
| TRT inlet gas temperature | 100 °C |
| TRT outlet gas temperature | 50 ${}^{ \circ }\mathrm{C}$ |
1.4 ${\mathrm{{CO}}}_{2}$ Emission from Blast Furnace
1.4 高炉${\mathrm{{CO}}}_{2}$排放
An iron-making process makes use of iron ore, fuel (coke, sometimes it is supplemented by heavy oil, pulverized coal, natural gas etc.) and other auxiliary raw materials to produce molten iron and two by-products (slag and coal gas) through heating, decomposing, revivification slagging, desulfuration and other reactions in a blast furnace. In the production of blast furnace, iron ore, coke and limestone are put into the furnace from the top. After preheated through a hot blast furnace, air is blown into the furnace from the bottom by a blast blower. Under high temperature, carbon of coke, pulverized coal, heavy oil, natural gas and other fuels and blowing oxygen burn to generate carbon monoxide (CO). In the rising process of CO in a furnace, the oxygen in iron ore is removed, the iron ore is reduced to molten iron. The molten iron is released from a iron hole as the product of blast furnace; the non-reductive impurities in iron ore react with the fluxes such as limestone to generate slag, discharging from a slag hole; the generated gas (blast furnace gas) is released from the top of the furnace. After removal of dust, the gas can be used as the fuel of hot blast furnace, heating furnace, coke oven, boiler, etc. The pressure of blast furnace gas (BFG) mainly depends on the pressure of blowing air.
炼铁过程利用铁矿石、燃料(焦炭,有时辅以重油、煤粉、天然气等)和其他辅助原料,通过高炉内的加热、分解、还原造渣、脱硫等反应,生产铁水和两种副产品(炉渣和煤气)。在高炉生产中,铁矿石、焦炭和石灰石从顶部装入炉内。空气经热风炉预热后,由鼓风机从底部吹入炉内。在高温下,焦炭、煤粉、重油、天然气等燃料中的碳与鼓入的氧气燃烧生成一氧化碳(CO)。在炉内CO上升过程中,铁矿石中的氧被去除,铁矿石被还原成铁水。铁水从出铁口放出成为高炉产品;铁矿石中的非还原性杂质与石灰石等熔剂反应生成炉渣,从出渣口排出;产生的气体(高炉煤气)从炉顶放出。除尘后,该气体可作为热风炉、加热炉、焦炉、锅炉等的燃料。高炉煤气(BFG)的压力主要取决于鼓入空气的压力。
Blast furnace gas can be classified into coarse dust removal coal gas, semi-clean dust removal coal gas and fine dust removal coal gas. According to different purification methods, blast furnace gas can be purified by dry dust and wet dust removal methods. The coarse dust removal is usually conducted with dry method. The coarse dust removal is the first purification in a dust removal process. The semi-clean dust removal can adopt wet method or dry method. The fine dust removal is the final stage of BFG dust removal. The purified fine gas can be sent to a gas pipeline after energy recovered by a blast furnace top gas pressure recovery turbine system (TRT). Blast furnace top gas pressure recovery turbine (TRT) system makes use of pressure energy and sensible heat of BFG. Through the system, the blast furnace gas pressure energy and part of heat energy can be converted into mechanical energy and then drives a generator to generate electricity.
高炉煤气可分为粗除尘煤气、半净除尘煤气和精除尘煤气。根据不同的净化方法,高炉煤气可采用干法和湿法除尘。粗除尘通常采用干法。粗除尘是除尘过程中的第一道净化工序。半净除尘可采用湿法或干法。精除尘是高炉煤气除尘的最后阶段。净化后的净煤气经高炉炉顶煤气余压回收透平系统(TRT)回收能量后可送入煤气管道。高炉炉顶煤气余压回收透平(TRT)系统利用高炉煤气的压力能和显热。通过该系统,高炉煤气的压力能和部分热能可转化为机械能,进而驱动发电机发电。
Table 4 BFG composition of typical iron/steel plant in China
表4 中国典型钢铁厂的高炉煤气成分
| Composition | CO | ${\mathrm{{CO}}}_{2}$ | ${\mathrm{H}}_{2}$ | ${\mathrm{N}}_{2}$ | ${\mathrm{O}}_{2}$ |
| Vol% | 21.8 | 23.1 | 3.2 | 51.7 | 0.2 |
The capacity of TRT should be matched to the gas amount of a blast furnace and the furnace top pressure, while amount of blast furnace gas is associated with the capacity of blast furnace blower. Temperature and pressure will be mainly changed between the inlet and outlet of TRT. Table 3 illustrated a typical operating condition at TRT inlet and outlet. It is observed that pressure and temperature decrease significantly after TRT. The main composition of blast furnace gas after TRT is $\mathrm{{CO}},{\mathrm{{CO}}}_{2},{\mathrm{\;N}}_{2},{\mathrm{H}}_{2}$ and ${\mathrm{{CH}}}_{4}$ . Table 4 is the blast furnace gas composition of a typical steel/iron plant in China. The ${\mathrm{{CO}}}_{2}$ concentration is ${23.1}\%$ which is higher than that of flue gas from lime kiln.
TRT的能力应与高炉的煤气量和炉顶压力相匹配,而高炉煤气量与高炉鼓风机的能力有关。TRT进出口之间温度和压力会有较大变化。表3给出了TRT进出口的典型运行工况。可以看出,经过TRT后压力和温度显著降低。TRT后高炉煤气的主要成分是$\mathrm{{CO}},{\mathrm{{CO}}}_{2},{\mathrm{\;N}}_{2},{\mathrm{H}}_{2}$和${\mathrm{{CH}}}_{4}$。表4是中国某典型钢铁厂的高炉煤气成分。${\mathrm{{CO}}}_{2}$浓度为${23.1}\%$,高于石灰窑烟气中的浓度。
1.5 CO2 Emission from Converter
1.5 转炉的二氧化碳排放
In the Linz-Donawitz smelting process, the molten iron in the furnace reacts with the blown oxygen. The produced gas is called Linz-Donawitz gas (LDG), which is mainly from the oxidation of carbon in molten iron. Due to the high temperature in a converter furnace, the main oxide of carbon is CO, account for about 90% of total amount carbon oxides. A small portion of carbon reacts directly with oxygen to produce ${\mathrm{{CO}}}_{2}$ and some $\mathrm{{CO}}$ could escape from the surface of molten steel and react with oxygen to produce ${\mathrm{{CO}}}_{2}$ .
在氧气顶吹转炉炼钢过程中,炉内铁水与吹入的氧气发生反应。产生的气体称为氧气顶吹转炉煤气(LDG),主要来自铁水中碳的氧化。由于转炉炉内温度较高,碳的主要氧化物是CO,约占碳氧化物总量的90%。一小部分碳直接与氧气反应生成${\mathrm{{CO}}}_{2}$,一些$\mathrm{{CO}}$可能从钢水表面逸出并与氧气反应生成${\mathrm{{CO}}}_{2}$。
At the beginning of blowing oxygen process, the temperature of molten iron is low, the easily oxidized elements silicon and manganese in the molten iron are first oxidized, then phosphorus, sulfur and other elements; meanwhile, a small portion of iron is also oxidized. Because carbon has a lower oxidation rate, furnace gas volume produced is relatively small and the furnace gas temperature is relatively low. With huge heat released associated with the oxidation reaction of above elements, the temperature of the molten pool increases correspondingly. When the temperature of the molten pool exceeds ${1400}{}^{ \circ }\mathrm{C}$ , carbon and oxygen react violently, leading to CO content in the furnace gas gradually increased. The amount of furnace gas produced per unit time is related with the intensity of blowing oxygen and carbon reduction speed. The greater of the intensity of blowing oxygen and the faster of the carbon reduction speed, the more of the amount of furnace gas produced in unit time. In the later period of converting, with the decrease of carbon in molten iron, the amount of LDG production decreases, but the temperature of LDG rises with the rising temperature of molten pool.
在吹氧过程开始时,铁水温度较低,铁水中易氧化的元素硅和锰首先被氧化,然后是磷、硫等元素;同时,也有一小部分铁被氧化。由于碳的氧化速率较低,产生的炉气量相对较小,炉气温度也相对较低。随着上述元素氧化反应释放出大量热量,熔池温度相应升高。当熔池温度超过${1400}{}^{ \circ }\mathrm{C}$时,碳与氧气剧烈反应,导致炉气中CO含量逐渐增加。单位时间内产生的炉气量与吹氧强度和碳还原速度有关。吹氧强度越大,碳还原速度越快,单位时间内产生的炉气量就越多。在转炉后期,随着铁水中碳含量的降低,LDG产量减少,但随着熔池温度升高,LDG温度升高。
The Linz-Donawitz steel-making is usually intermittent. One process may take about 40 min. In the time of beginning and end of converting, the amount of furnace gas is small and CO content is low, hence, the furnace gas is normally taken in the middle section. The former and latter periods are called pre-combustion period and post-combustion period. The middle period for capture furnace gas is called capture period. Due to the periodicity of a Linz-Donawitz steel-making process, the capture time is intermittent, resulting in furnace gas intermittently discharged.
氧气顶吹转炉炼钢通常是间歇性的。一个过程大约需要40分钟。在转炉吹炼开始和结束时,炉气量小且CO含量低,因此,炉气通常在中间段抽取。前后两段分别称为预燃期和后燃期。中间用于捕集炉气的时间段称为捕集期。由于氧气顶吹转炉炼钢过程的周期性,捕集时间是间歇性的,导致炉气间歇性排放。
In the process of converting, when adding auxiliary raw material to a converter, the amount of furnace gas will increase rapidly. The auxiliary raw materials are slagging flux and coolant. The slagging flux mainly uses lime and the coolant mainly uses steel scrap, iron ore and oxidized scale. After the gas leaves the furnace mouth of converter, it will burn when meets air. In addition, the gas contains highly toxic materials. Therefore, the high temperature flue gas needs to be captured at the furnace mouth of converter. When the high temperature flue gas pass through a evaporation cooling facility, the flue gas is initially cooled while some heat energy is recovered. The temperature at the outlet the evaporation cooling facility is about ${900}{}^{ \circ }\mathrm{C}$ (Zhang et al.,2017). After initially cooling and coarse dust removal, the flue gas needs to be further cooled and depressurization to meet operating conditions of fine dust removal units.
在转炉吹炼过程中,向转炉中加入辅助原料时,炉气量会迅速增加。辅助原料是造渣剂和冷却剂。造渣剂主要使用石灰,冷却剂主要使用废钢、铁矿石和氧化铁皮。气体离开转炉炉口后,遇到空气会燃烧。此外,气体中含有剧毒物质。因此,高温烟气需要在转炉炉口捕集。当高温烟气通过蒸发冷却设施时,烟气首先被冷却,同时回收一些热能。蒸发冷却设施出口温度约为${900}{}^{ \circ }\mathrm{C}$(Zhang等人,2017年)。经过初步冷却和粗除尘后,烟气需要进一步冷却和减压,以满足细除尘装置的运行条件。
Dust removal purification methods have two types: wet method and dry method. ① The typical process of wet purification system is: after released from a converter, the gas is initially cooled to ${800} - {1000}{}^{ \circ }\mathrm{C}$ through a vaporizing cooler, then go through the first-degree venturi tube, the first elbow dehydrator, the second-grade venturi tube and the second elbow dehydrator successively. Spraying water at the throat of the venturi tube will decrease gas temperature to about ${35}^{ \circ }\mathrm{C}$ and reduce the dust content in the gas. The purified gas is then sent to a gas storage cabinet by an induced draft fan. ② A typical process of dry purification system is: the gas temperature is dropped to ${1000}{}^{ \circ }\mathrm{C}$ through vaporizing cooler, then further dropped to ${200}{}^{ \circ }\mathrm{C}$ by using an evaporative cooling tower. Through dust removal of dry-type electrostatic precipitator, the purified gas is fed into a gas storage cabinet by an induced draft fan. Compared to wet method, dry method purification system has the following advantages:
除尘净化方法有湿法和干法两种。① 湿法净化系统的典型流程是:气体从转炉排出后,先通过汽化冷却器冷却至${800} - {1000}{}^{ \circ }\mathrm{C}$,然后依次经过一级文氏管、第一弯头脱水器、二级文氏管和第二弯头脱水器。在文氏管喉部喷水可使气体温度降至约${35}^{ \circ }\mathrm{C}$,并降低气体中的粉尘含量。净化后的气体由引风机送入储气柜。② 干法净化系统的典型流程是:气体通过汽化冷却器降温至${1000}{}^{ \circ }\mathrm{C}$,然后利用蒸发冷却塔进一步降至${200}{}^{ \circ }\mathrm{C}$。通过干式静电除尘器除尘后,净化后的气体由引风机送入储气柜。与湿法相比,干法净化系统具有以下优点:
Table 5 Composition of typical LDG
表5典型LDG的成分
| Composition | CO | ${\mathrm{{CO}}}_{2}$ | ${\mathrm{H}}_{2}$ | ${\mathrm{N}}_{2}$ | ${\mathrm{{CH}}}_{4}$ | ${\mathrm{C}}_{2}{\mathrm{H}}_{4}$ | ${\mathrm{C}}_{2}{\mathrm{H}}_{6}$ | ${\mathrm{C}}_{3}{\mathrm{H}}_{6}$ | ${\mathrm{O}}_{2}$ | ${\mathrm{H}}_{2}\mathrm{O}$ |
| Vol% | 58.5 | 15.1 | 3.7 | 21.5 | 1.0 | 0.1 | 0 | 0 | 0.1 | saturation |
The dust content of gas is low;
气体粉尘含量低;
Because of well-developed automation system leading to a quick switch of gas capture system, gas capture rate is increased. Normally, the capture rate of dry method system is 15-30% more than that of wet method one.
由于自动化系统发达,气体捕获系统切换迅速,气体捕获率得以提高。通常,干法系统的捕获率比湿法系统高15 - 30%。
The dust content of gas is low after purification, resulting in longer life of draught fan and less workload of maintenance s;
净化后气体含尘量低,使得引风机寿命延长,维护工作量减少;
System resistance is small;
系统阻力小;
Water conservation;
节约用水;
Total power load of dry method system is much less than wet method;
干法系统的总电力负荷远低于湿法;
Increase the recycled amount of dust containing iron and reduce the associated transportation cost;
提高含铁粉尘的回收量,降低相关运输成本;
Water treatment system is unnecessary, reduce land use;
无需水处理系统,减少土地使用;
Reduce secondary pollution of waste water and reduce dispersed gas amount.
减少废水二次污染,减少分散气体量。
The disadvantage is:
缺点是:
Complex system, high failure rate and high maintenance cost;
系统复杂,故障率高,维护成本高;
Requires high management and operational skills. More training for manager and operators be carried out.
对管理和操作技能要求高。需对管理人员和操作人员进行更多培训。
Fixed investment cost is high (Wang et al., 2008).
固定投资成本高(Wang等人,2008年)。
Table 5 demonstrates the composition of a typical Linz-Donawitz gas (LDG) after dust removal. The temperature of the gas is about ${100}{}^{ \circ }\mathrm{C}$ and the pressure is slightly higher than the ambient pressure.
表5展示了典型的林茨 - 多纳维茨气体(LDG)除尘后的成分。气体温度约为${100}{}^{ \circ }\mathrm{C}$,压力略高于环境压力。
1.6 CO2 Emission from Hot Blast Furnace
1.6 热风炉的二氧化碳排放
An iron-making blast furnace is usually equipped with several hot blast furnaces, with each hot blast furnace consisting of a combustion chamber, a regenerative chamber, a wind mixing chamber, and a variety of valves and corresponding pipes. The air required for the combustion of a hot blast furnace is provided by a combustion fan. According to the regulations of a hot blast furnace operating instruction, in the normal operating process of a hot blast furnace, a smothered furnace state is necessary between blowing-in and combustion operations. There is no direct transfer between the blowing-in and the combustion state. In short, the production cycle of a hot blast furnace should be combustion—stop—blowing-in—stop—combustion (Liu, 2016).
炼铁高炉通常配备多个热风炉,每个热风炉由燃烧室、蓄热室、风混合室以及各种阀门和相应管道组成。热风炉燃烧所需的空气由燃烧风机提供。根据热风炉操作说明书的规定,在热风炉的正常运行过程中,送风操作和燃烧操作之间需要有闷炉状态。送风状态和燃烧状态之间没有直接转换。简而言之,热风炉的生产周期应为燃烧—停止—送风—停止—燃烧(刘,2016)。
The combustion stage is also called a burning furnace stage. The aim is to heat hot blast furnace lattice bricks to a certain temperature to reserve heat by lattice bricks. The combustion fuel is mainly of blast furnace gas, mixture of blast furnace gas and coke oven, gas or mixture of blast furnace gas and CFG as well as combustion air. Those fuels and air are fed into hot furnace through the burner with a certain ratio between the fuels and the air. The fuels burn in the burner aided with air. The resulting gas is discharged from a flue outlet. At combustion stage, cold air inlet and hot air outlet are both in a closure state. After the combustion process (i.e., lattice bricks storage heat sufficiently), and the operation moved to the next air blowing-in stage.
燃烧阶段也称为烧炉阶段。目的是将热风炉格子砖加热到一定温度,以便格子砖蓄热。燃烧燃料主要是高炉煤气、高炉煤气与焦炉煤气的混合气、高炉煤气与CFG的混合气以及燃烧空气。这些燃料和空气通过燃烧器以一定的燃料与空气比例送入热风炉。燃料在燃烧器中与空气辅助燃烧。产生的气体从烟道出口排出。在燃烧阶段,冷空气入口和热空气出口均处于关闭状态。燃烧过程结束后(即格子砖蓄热充分后),操作进入下一个送风阶段。
At the stage of blowing-in, cold air is heated when fed into the blast furnace. The burner and the flue outlet are kept off, while cold air inlet and hot blast air outlet are open. With the heat exchange between cold air and lattice bricks, the temperature of the lattice bricks decreases. Finally, the operation is ceased, waiting for the combustion in the next round.
在送风阶段,冷空气在送入高炉时被加热。燃烧器和烟道出口关闭,而冷空气入口和热风出口打开。随着冷空气与格子砖之间的热交换,格子砖的温度降低。最后,操作停止,等待下一轮燃烧。
Because the ratio of air and fuel in the hot blast furnace is different and the inlet pressure and temperature of gas and air are also different, the ${\mathrm{{CO}}}_{2}$ content would be different in the flue gas of hot blast furnace. The residual ${\mathrm{O}}_{2}$ is also affected by air-fuel ratio. The general composition of hot blast flue gas is shown in Table 6. Although the hot blast flue gas produced by a single hot blast furnace is continuous, in the actual production process, the emission of flue gas at outlet of a chimney is approximately continuous as multiple hot blast furnaces share a flue gas discharge chimney.
由于热风炉中空气与燃料的比例不同,气体和空气的入口压力及温度也不同,热风炉烟道气中的${\mathrm{{CO}}}_{2}$含量会有所不同。残余的${\mathrm{O}}_{2}$也受空燃比影响。典型热风炉烟道气的一般组成见表6。虽然单个热风炉产生的热风炉烟道气是连续的,但在实际生产过程中,由于多个热风炉共用一个烟道气排放烟囱,烟囱出口处的烟道气排放近似连续。
Table 6 Composition of typical hot blast furnace flue gas
表6 典型热风炉烟道气组成
| Composition | ${\mathrm{{CO}}}_{2}$ | ${\mathrm{N}}_{2}$ | ${\mathrm{O}}_{2}$ | ${\mathrm{H}}_{2}\mathrm{O}$ | Dust $/\left( {\mathrm{{mg}}{\mathrm{m}}^{-3}}\right)$ |
| Vol% | 28.52 | 65.15 | 2.51 | 3.82 | 5 |
1.7 CO2 Emission from Power Generation Unit
1.7 发电单元的二氧化碳排放
The power plant in a steel/iron enterprise is to supply heat and electricity to meet iron/steel making demand. The power plant normally consumes the combustible gases produced during iron/steel making processes, including coke oven gas and blast furnace gas, to improve power supply reliability, to reduce power generation cost, and to contribute to energy conservation and environmental protection of iron/steel industry. The ${\mathrm{{CO}}}_{2}$ concentration of flue gas produced by power and heat generation processes in the power plant is a little low, being about 10-15%.
钢铁企业中的发电厂旨在供应热能和电能,以满足钢铁制造的需求。发电厂通常消耗钢铁制造过程中产生的可燃气体,包括焦炉煤气和高炉煤气,以提高供电可靠性、降低发电成本,并为钢铁行业的节能减排和环境保护做出贡献。发电厂发电和供热过程产生的烟气中${\mathrm{{CO}}}_{2}$浓度略低,约为10 - 15%。
1.8 Summary of main ${\mathrm{{CO}}}_{2}$ sources in iron/steel industry
1.8 钢铁行业主要${\mathrm{{CO}}}_{2}$来源总结
There are multiple ${\mathrm{{CO}}}_{2}$ emission sources with huge emissions in an integrated steel/iron plant. The different emission sources correspond to different production processes, thus have different emission characteristics. Among them, the ${\mathrm{{CO}}}_{2}$ content of flue gas of lime kiln, hot blast furnace gas, blast furnace gas and converter furnace gas is higher than that of post-combustion flue gas generated from a typical coal-fired power plant; while, the ${\mathrm{{CO}}}_{2}$ concentration of coke oven flue gas and the self-provided power plant could be lower than that of post-combustion flue gas from coal-fired power plant.
在综合钢铁厂中,存在多个排放量大的${\mathrm{{CO}}}_{2}$排放源。不同的排放源对应不同的生产过程,因此具有不同的排放特征。其中,石灰窑、热风炉煤气、高炉煤气和转炉煤气的烟气中${\mathrm{{CO}}}_{2}$含量高于典型燃煤电厂产生的燃烧后烟气;而焦炉烟气和自备电厂的${\mathrm{{CO}}}_{2}$浓度可能低于燃煤电厂燃烧后烟气。
In terms of pressure, except that there is a higher pressure in blast furnace gas before TRT, the pressure of other emission sources is close to an atmospheric pressure. Regarding temperature, the flue gas from hot blast furnace normally has high temperature than other emission sources, thus heat recovery is desired before ${\mathrm{{CO}}}_{2}$ capture. As for discharge way, the discharge of LDG is intermittent, while others are continuously or approximately continuously discharged. Among all gas sources, LDG and BFG are both combustible. Their calorific value can be increased accordingly by capturing ${\mathrm{{CO}}}_{2}$ . In general, the different emission characteristics of ${\mathrm{{CO}}}_{2}$ enriched gases from iron/steel industry have influence on the technical and economic performance of different capture technologies.
在压力方面,除了高炉煤气在TRT之前压力较高外,其他排放源的压力接近大气压。在温度方面,热风炉烟气通常比其他排放源温度高,因此在${\mathrm{{CO}}}_{2}$捕集之前需要进行热回收。至于排放方式,转炉煤气的排放是间歇性的,而其他排放源是连续或近似连续排放。在所有气体源中,转炉煤气和高炉煤气都是可燃的。通过捕集${\mathrm{{CO}}}_{2}$,它们的热值可以相应提高。一般来说,钢铁行业富${\mathrm{{CO}}}_{2}$气体的不同排放特征会影响不同捕集技术的技术和经济性能。
2 Section 2
2 第2节
2.1 Carbon Capture Technologies for Steel/iron Industry
2.1 钢铁行业的碳捕集技术
The technology development in China’s steel/iron industry is unbalanced, although the overall energy consumption is much higher than that of the international community. With the implementation of energy conservation technologies in China’s steel/iron industry, the energy consumption level of China’s large steel/iron companies is already close to that of international iron/steel enterprises. Therefore, the indirect emission reduction through energy conservation is more and more limited for those large enterprises, resulting in the emission reduction cost through energy conservation is getting higher and higher. It is economically hard for those large steel/iron companies to meet their long-term emission reduction target. As a large-scale ${\mathrm{{CO}}}_{2}$ emission reduction technology with great potential, carbon capture technology can be a cost-effective option to the indirect emission reduction technology. It can benefit large-scale enterprise by achieving a sustainable emission reduction target without changing its already established energy balance system. Therefore, carbon capture technology is increasingly recognized by large steel/iron enterprises in the world.
中国钢铁行业的技术发展不均衡,尽管其整体能源消耗远高于国际水平。随着中国钢铁行业节能技术的实施,大型钢铁企业的能源消耗水平已接近国际钢铁企业。因此,对于这些大型企业而言,通过节能实现的间接减排作用越来越有限,导致节能减排成本越来越高。大型钢铁企业在经济上难以实现其长期减排目标。作为一种具有巨大潜力的大规模${\mathrm{{CO}}}_{2}$减排技术,碳捕集技术对于间接减排技术而言可能是一种经济高效的选择。它可以在不改变其已建立的能量平衡系统的情况下实现可持续减排目标,从而使大型企业受益。因此,碳捕集技术越来越受到全球大型钢铁企业的认可。
According to different ${\mathrm{{CO}}}_{2}$ sources, carbon capture technologies are generally categorized into three types: post-combustion capture, pre-combustion capture and oxyfuel combustion capture. Among them, the post-combustion capture refers to the capture of ${\mathrm{{CO}}}_{2}$ from the flue gas of fossil fuel combustion. According to the analysis in Sect. 1, the most of ${\mathrm{{CO}}}_{2}$ associated with steel/iron production is mainly from post-combustion flue gas, hence, this study focuses on the post-combustion capture technology for iron/steel industry. Based on different separation principles, the post-combustion capture can be further typed into absorption capture technology, adsorption capture technology, membrane capture technology, cryogenic capture technology, hydrate capture technology and mineral carbonation capture technology.
根据不同的${\mathrm{{CO}}}_{2}$来源,碳捕集技术通常分为三类:燃烧后捕集、燃烧前捕集和富氧燃烧捕集。其中,燃烧后捕集是指从化石燃料燃烧产生的烟道气中捕集${\mathrm{{CO}}}_{2}$。根据第1节的分析,与钢铁生产相关的大部分${\mathrm{{CO}}}_{2}$主要来自燃烧后的烟道气,因此,本研究重点关注钢铁行业的燃烧后捕集技术。基于不同的分离原理,燃烧后捕集可进一步分为吸收捕集技术、吸附捕集技术、膜捕集技术、低温捕集技术、水合物捕集技术和矿物碳酸化捕集技术。
2.2 Absorption Capture Technology
2.2 吸收捕集技术
Absorption capture or separation technology is a technology that uses absorbent solution to separate ${\mathrm{{CO}}}_{2}$ from mixed gases containing ${\mathrm{{CO}}}_{2}$ . It can be divided into physical absorption method and chemical absorption method (Li, 2014). The absorption technology has been widely used in chemical industry, oil refining, natural gas processing and other fields, and it is proved that it has the application prospect in steel/iron industry (IEA, 2010) (Fig. 2).
吸收捕集或分离技术是一种利用吸收剂溶液从含有${\mathrm{{CO}}}_{2}$的混合气体中分离${\mathrm{{CO}}}_{2}$的技术。它可分为物理吸收法和化学吸收法(Li,2014)。吸收技术已在化工、炼油、天然气加工等领域广泛应用,并且已证明在钢铁行业具有应用前景(IEA,2010)(图2)。
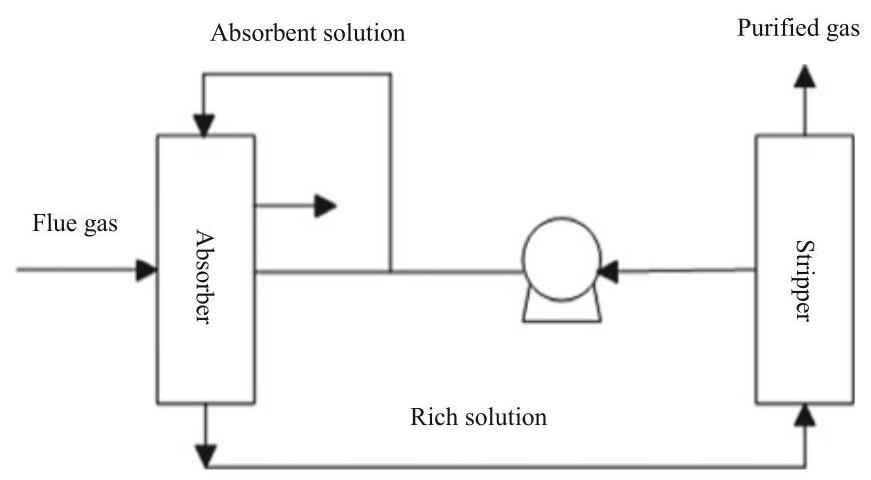
Fig. 2 Principle of chemical absorption method
图2 化学吸收法原理
The chemical absorption method refers to the use of alkaline chemical absorbent, such as ammonia, to absorb ${\mathrm{{CO}}}_{2}$ in a flue gas by chemical reaction and form unstable salt. Under a certain temperature and pressure condition, the salt can be decomposed in reverse to release ${\mathrm{{CO}}}_{2}$ , so as to achieve the aim that removing ${\mathrm{{CO}}}_{2}$ from the flue gas (Jiang,2015). At present, the typical chemical absorbents include mono ethanol amine (MEA), alkyl alcohol amine, ammonium hydroxide, hot potassium carbonate solution, etc. (Sun, 2009), the recovery rate of ${\mathrm{{CO}}}_{2}$ can reach 90%, the purity can reach above 99%.
化学吸收法是指利用碱性化学吸收剂,如氨,通过化学反应吸收烟气中的${\mathrm{{CO}}}_{2}$并形成不稳定的盐。在一定温度和压力条件下,盐可逆向分解释放出${\mathrm{{CO}}}_{2}$,从而达到从烟气中脱除${\mathrm{{CO}}}_{2}$的目的(Jiang,2015)。目前,典型的化学吸收剂包括单乙醇胺(MEA)、烷基醇胺、氢氧化铵、热碳酸钾溶液等(Sun, 2009),${\mathrm{{CO}}}_{2}$的回收率可达90%,纯度可达99%以上。
The study of Gielen (2003) indicated that chemical absorption methods can be used to deal with blast furnace gas (BFG), Linz-Donawitz gas (LDG), and flue gas produced in the process of direct reduction and melting. Tseitlin et al. (1994) used a mono ethanol amine (MEA) solvent to separate ${\mathrm{{CO}}}_{2}$ from blast furnace gas. Tobiesen et al (2007) adopted different amine solvents to separate ${\mathrm{{CO}}}_{2}$ from blast furnace gas. In order to separate the ${\mathrm{{CO}}}_{2}$ with the concentration of 30% from hot blast furnace, Cheng et al (2010a) investigated the performance of different solvents. Yoon et al (2011) developed a potassium carbonate/cyclic diamine solvent to separate ${\mathrm{{CO}}}_{2}$ from the flue gas with concentration of 15-20% in the steel/iron industry.
Gielen(2003)的研究表明,化学吸收法可用于处理高炉煤气(BFG)、氧气顶吹转炉煤气(LDG)以及直接还原和熔炼过程中产生的烟气。Tseitlin等人(1994)使用单乙醇胺(MEA)溶剂从高炉煤气中分离${\mathrm{{CO}}}_{2}$。Tobiesen等人(2007)采用不同的胺溶剂从高炉煤气中分离${\mathrm{{CO}}}_{2}$。为了从热风炉中分离浓度为30%的${\mathrm{{CO}}}_{2}$,Cheng等人(2010a)研究了不同溶剂的性能。Yoon等人(2011)开发了一种碳酸钾/环状二胺溶剂,用于从钢铁行业中浓度为15 - 20%的烟气中分离${\mathrm{{CO}}}_{2}$。
In technology demonstration field, POSCO developed an ammonia absorption technology to separate ${\mathrm{{CO}}}_{2}$ form blast furnace gas. In order to reduce the cost of ${\mathrm{{CO}}}_{2}$ separation, a medium and low temperature waste heat from steel/iron mill was used as the desorption heat of ${\mathrm{{CO}}}_{2}$ (Kim et al.,2009). The first phase of a pilot project was completed in 2008 with processing capacity being ${50}{\mathrm{\;m}}^{3}/\mathrm{h}$ , ${\mathrm{{CO}}}_{2}$ recovery rate being above ${90}\%$ and ${\mathrm{{CO}}}_{2}$ volume fraction (concentration) being above ${95}\%$ . Base on phase one, the second phase of the pilot project was completed in 2011 with blast furnace gas processing capacity being expanded to ${1000}{\mathrm{\;m}}^{3}/\mathrm{h},{\mathrm{{CO}}}_{2}$ recovery rate being over ${90}\%$ , and the concentration of ${\mathrm{{CO}}}_{2}$ exceeding 99.5% (POSCO, 2013). In the project of COURSE50, in order to reach the target of 30% emission reduction, Japan New Energy Industrial Technology Development Organization (NEDO) commissioned the Nippon Steel & Sumitomo Metal and JEF to carry out relevant technology development under the support of the Japan Iron and Steel Federation (Li and Lu, 2009).
在技术示范领域,浦项制铁开发了一种氨吸收技术,用于从高炉煤气中分离${\mathrm{{CO}}}_{2}$。为了降低${\mathrm{{CO}}}_{2}$分离成本,利用钢铁厂的中低温余热作为${\mathrm{{CO}}}_{2}$的解吸热(Kim等人,2009)。该试点项目的第一阶段于2008年完成,处理能力为${50}{\mathrm{\;m}}^{3}/\mathrm{h}$,${\mathrm{{CO}}}_{2}$回收率高于${90}\%$,${\mathrm{{CO}}}_{2}$体积分数(浓度)高于${95}\%$。基于第一阶段,该试点项目的第二阶段于2011年完成,高炉煤气处理能力扩大到${1000}{\mathrm{\;m}}^{3}/\mathrm{h},{\mathrm{{CO}}}_{2}$,回收率超过${90}\%$,${\mathrm{{CO}}}_{2}$浓度超过99.5%(浦项制铁,2013)。在COURSE50项目中,为了实现减排30%的目标,日本新能源产业技术综合开发机构(NEDO)委托新日铁住金和JEF在日本钢铁联盟的支持下开展相关技术开发(Li和Lu,2009)。
Nippon Steel & Sumitomo Metal developed ESCAP (energy conversation ${\mathrm{{CO}}}_{2}$ absorption process) low energy consumption ${\mathrm{{CO}}}_{2}$ separation process, which uses the developed new type of amine solvent (RN) to remove ${\mathrm{{CO}}}_{2}$ from blast furnace gas, the desorption heat is low temperature waste heat that has not been utilized in previous iron works (TNCSTEEL, 2015). The process required a low regeneration temperature, and the newly developed amine solvent is less corrosive to equipment and devices. For the combined use of the new type amine solvent RN and the waste heat recovery system, ${\mathrm{{CO}}}_{2}$ capture cost was expected to be almost 50% lower than that of MEA method (30%MEA) (Goto et al., 2013). Toshiba International Corp Pty Ltd/Toshiba Corporation in collaboration with Tongfang Environment Co. Ltd proposed an amine solvent absorption method to capture ${\mathrm{{CO}}}_{2}$ in the case of Shougang Jingtang steel plant in China.
新日铁住金开发了ESCAP(能量转换${\mathrm{{CO}}}_{2}$吸收工艺)低能耗${\mathrm{{CO}}}_{2}$分离工艺,该工艺使用新开发的新型胺溶剂(RN)从高炉煤气中去除${\mathrm{{CO}}}_{2}$,解吸热为以往钢铁厂未利用的低温废热(TNCSTEEL,2015年)。该工艺所需的再生温度较低,新开发的胺溶剂对设备和装置的腐蚀性较小。对于新型胺溶剂RN和废热回收系统的联合使用,${\mathrm{{CO}}}_{2}$捕集成本预计比MEA法(30%MEA)低近50%(后藤等人,2013年)。东芝国际公司/东芝公司与同方环境有限公司合作,针对中国首钢京唐钢铁厂的情况,提出了一种胺溶剂吸收法来捕集${\mathrm{{CO}}}_{2}$。
The physical absorption method is the absorption of ${\mathrm{{CO}}}_{2}$ by means of physical dissolution. Its advantages include good absorption effect, low energy consumption and high separation recovery rate. Its disadvantages is that it is only suitable for flue gas with high ${\mathrm{{CO}}}_{2}$ content (Huang,2013). Therefore, for low ${\mathrm{{CO}}}_{2}$ content emission sources of steel/iron plant, the physical absorption method may not be technically feasible. The technologies developed by typical physical absorption method include Selexol™ system based on ethylene glycol and Rectisol® system based on methyl alcohol. The Selexol process can operate at an ambient temperature, while the Rectisol process operates as low as $- {60}^{ \circ }\mathrm{C}$ temperature condition. These systems have been applied in a large scale in the process of syngas purification and natural gas processing.
物理吸收法是通过物理溶解来吸收${\mathrm{{CO}}}_{2}$。其优点包括吸收效果好、能耗低和分离回收率高。其缺点是仅适用于${\mathrm{{CO}}}_{2}$含量高的烟气(黄,2013年)。因此,对于钢铁厂${\mathrm{{CO}}}_{2}$含量低的排放源,物理吸收法在技术上可能不可行。典型物理吸收法开发的技术包括基于乙二醇的Selexol™系统和基于甲醇的Rectisol®系统。Selexol工艺可在环境温度下运行,而Rectisol工艺在低至$- {60}^{ \circ }\mathrm{C}$温度条件下运行。这些系统已在合成气净化和天然气加工过程中大规模应用。
2.3 Adsorption Capture Technology
2.3 吸附捕集技术
Adsorption capture technology is a technology that utilizes the selectivity of the solid adsorbent for ${\mathrm{{CO}}}_{2}$ and reversible adsorption to separate ${\mathrm{{CO}}}_{2}$ from mixed feed gases containing ${\mathrm{{CO}}}_{2}$ . The adsorbent adsorbs ${\mathrm{{CO}}}_{2}$ in a low temperature (or high pressure). The ${\mathrm{{CO}}}_{2}$ is de-adsorbed when temperature increasing (temperature swing adsorption, TSA), pressure reduction (pressure swing adsorption, PSA or vacuum pressure swing adsorption, VPSA) or imposing low voltage current (electricity swing adsorption, ESA). Through periodic changes of temperature (or pressure), the ${\mathrm{{CO}}}_{2}$ is separated from a gas stream (Han et al.,2009). Currently, pressure swing adsorption process (PSA and VPSA) is more widely applied than TSA (Kuramochi et al., 2011).
吸附捕集技术是一种利用固体吸附剂对${\mathrm{{CO}}}_{2}$的选择性和可逆吸附作用,从含有${\mathrm{{CO}}}_{2}$的混合原料气中分离出${\mathrm{{CO}}}_{2}$的技术。吸附剂在低温(或高压)下吸附${\mathrm{{CO}}}_{2}$。当温度升高(变温吸附,TSA)、压力降低(变压吸附,PSA或真空变压吸附,VPSA)或施加低电压电流(电吸附,ESA)时,${\mathrm{{CO}}}_{2}$被解吸。通过温度(或压力)的周期性变化,将${\mathrm{{CO}}}_{2}$从气流中分离出来(Han等人,2009年)。目前,变压吸附过程(PSA和VPSA)比TSA应用更广泛(Kuramochi等人,2011年)。
The basic principle of pressure swing adsorption (PSA) is that using the difference of adsorption properties of a kind of gas by a solid material and the characteristic that the adsorption capacity varies with pressure. Through a periodic pressure transformation process, the separation or capture of a kind of gas can be realized. The adsorbate adsorb a specific gas (such as ${\mathrm{{CO}}}_{2}$ ) at a higher pressure, then the desorbed by reducing pressure. The process of adsorption at high pressure and desorption at normal pressure is normally called pressure swing adsorption (PSA); the process of adsorption at normal pressure or slightly higher than normal pressure, and desorption through vacuum is called vacuum pressure swing adsorption (VPSA).
变压吸附(PSA)的基本原理是利用固体材料对一种气体的吸附特性差异以及吸附容量随压力变化的特性。通过周期性的压力变换过程,可以实现一种气体的分离或捕集。被吸附物在较高压力下吸附特定气体(如${\mathrm{{CO}}}_{2}$),然后通过减压解吸。高压吸附常压解吸的过程通常称为变压吸附(PSA);常压或略高于常压吸附、真空解吸的过程称为真空变压吸附(VPSA)。
The performance of adsorbent determines the process and cost of pressure swing adsorption method. The pressure swing adsorption can use carbon-based adsorbent, zeolite and hydrotalcite-like compounds as the adsorbent and is widely applied in purification of hydrogen and ${\mathrm{{CO}}}_{2}$ . It can also be used to produce food grade ${\mathrm{{CO}}}_{2}$ , purification of $\mathrm{{CO}}$ , purification of natural gas, and oxygen and nitrogen separation.
吸附剂的性能决定了变压吸附法的工艺和成本。变压吸附可以使用碳基吸附剂、沸石和类水滑石化合物作为吸附剂,广泛应用于氢气和${\mathrm{{CO}}}_{2}$的净化。它还可用于生产食品级${\mathrm{{CO}}}_{2}$、$\mathrm{{CO}}$的净化、天然气的净化以及氧气和氮气的分离。
In the project of COURSE50, JFE steel company developed a two-stage pressure swing adsorption method (zeolite adsorbents) to separate ${\mathrm{{CO}}}_{2}$ from blast furnace gas (Qi et al., 2013). The pilot system (ASCOA-3) was developed with ${\mathrm{{CO}}}_{2}$ processing capacity of $3\mathrm{t}/\mathrm{d}$ . The system separates the flue gas with ${\mathrm{{CO}}}_{2}$ concentration of ${33}\%$ , the recovery rate of ${\mathrm{{CO}}}_{2}$ reaching ${80}\%$ and the ${\mathrm{{CO}}}_{2}$ purity being 99%. In 2011, POSCO developed a pressure swing adsorption technology (PSA) technology to separate the mixture of $\mathrm{{CO}}$ and ${\mathrm{{CO}}}_{2}$ . A small pilot with processing capacity of $1{\mathrm{{Nm}}}^{3}/\mathrm{h}$ and the concentration of captured ${\mathrm{{CO}}}_{2}$ being over 99% was established (POSCO, 2013).
在COURSE50项目中,JFE钢铁公司开发了一种两级变压吸附法(沸石吸附剂),从高炉煤气中分离${\mathrm{{CO}}}_{2}$(Qi等人,2013年)。开发了中试系统(ASCOA - 3),${\mathrm{{CO}}}_{2}$处理能力为$3\mathrm{t}/\mathrm{d}$。该系统分离${\mathrm{{CO}}}_{2}$浓度为${33}\%$的烟气,${\mathrm{{CO}}}_{2}$回收率达到${80}\%$,${\mathrm{{CO}}}_{2}$纯度为99%。2011年,浦项制铁开发了一种变压吸附技术(PSA),用于分离$\mathrm{{CO}}$和${\mathrm{{CO}}}_{2}$的混合物。建立了一个处理能力为$1{\mathrm{{Nm}}}^{3}/\mathrm{h}$、捕获的${\mathrm{{CO}}}_{2}$浓度超过99%的小型中试装置(浦项制铁,2013年)。
2.4 Membrane Capture Technology
<### 2.4 膜捕获技术
Membrane capture technology can be typed into membrane separation method and membrane-absorption method (Guo et al., 2016). Membrane separation method separates mixed gases according to the difference in permeation selectivity of membrane materials for different gases. The driving force of membrane separation is the pressure difference on both sides of the membrane. The gas with high permeability preferentially passes through the membrane and form a permeating airflow. The gas with low permeability forms a residual airflow on the other side. Two streams are led respectively to achieve gases separation (Feron & Jansen, 2002). The ability of this method to separate ${\mathrm{{CO}}}_{2}$ mainly depends on the selectivity of membrane material for ${\mathrm{{CO}}}_{2}$ (Guo et al.,2016). The membrane materials for separation of ${\mathrm{{CO}}}_{2}$ are high polymer material, inorganic material, hybrid organic-inorganic materials etc. (Wang et al., 2016). The separation process can adopt a single-stage membrane separation or a multistage membrane separation process (Fig. 3).
膜捕获技术可分为膜分离法和膜吸收法(Guo等人,2016年)。膜分离法根据膜材料对不同气体渗透选择性的差异来分离混合气体。膜分离的驱动力是膜两侧的压力差。渗透率高的气体优先透过膜并形成渗透气流。渗透率低的气体在另一侧形成残余气流。两股气流分别引出以实现气体分离(Feron和Jansen,2002年)。这种方法分离${\mathrm{{CO}}}_{2}$的能力主要取决于膜材料对${\mathrm{{CO}}}_{2}$的选择性(Guo等人,2016年)。用于分离${\mathrm{{CO}}}_{2}$的膜材料有高分子材料、无机材料、有机 - 无机杂化材料等(Wang等人,2016年)。分离过程可采用单级膜分离或多级膜分离工艺(图3)。
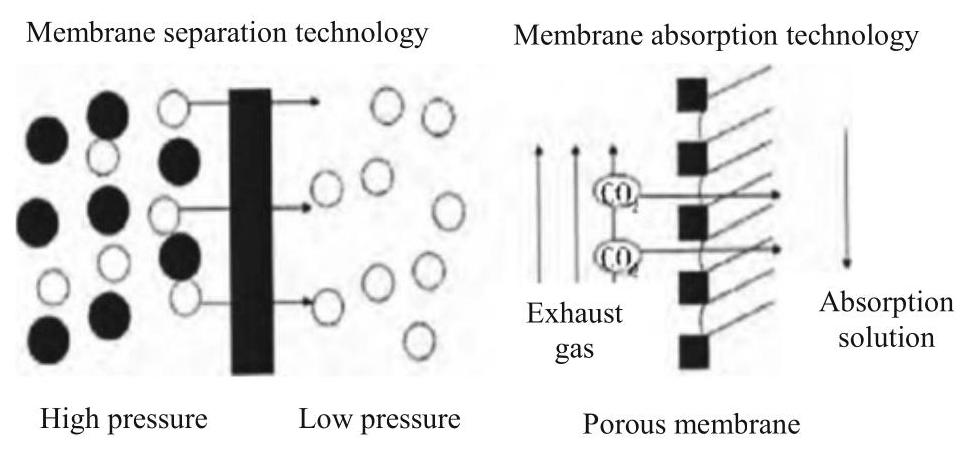
Fig. 3 Schematic principle of membrane separation ${\mathrm{{CO}}}_{2}$
<图3 膜分离${\mathrm{{CO}}}_{2}$的原理图
The membrane absorption method is driven by the pressure difference on both sides of membrane, depending on adsorption capacity of each component of gas on the membrane surface and the differences in dissolution and diffusion in membrane (difference of permeation rate), to realize separation. There is no selectivity on the raw gas for membrane itself. The membrane only provides isolation for gas and absorption liquid. The gas and the liquid is not direct contact. They flow on both sides of the membrane (Gao et al., 2016). the absorbents play a key role in the selectivity for the composition. The membrane absorption method has overcome some weaknesses of traditional gas (or ${\mathrm{{CO}}}_{2}$ ) absorption methods. In the case of low ${\mathrm{{CO}}}_{2}$ partial pressure, this method has high selectivity and large separation driving force, which can be modularized for engineering design (Zhang & Shu, 2015).
膜吸收法由膜两侧的压力差驱动,取决于气体各组分在膜表面的吸附能力以及在膜中的溶解和扩散差异(渗透率差异)来实现分离。膜本身对原料气没有选择性。膜只为气体和吸收液提供隔离。气体和液体不直接接触。它们在膜的两侧流动(Gao等人,2016年)。吸收剂在对成分的选择性方面起关键作用。膜吸收法克服了传统气体(或${\mathrm{{CO}}}_{2}$)吸收法的一些弱点。在${\mathrm{{CO}}}_{2}$分压较低的情况下,该方法具有高选择性和大分离驱动力,可模块化进行工程设计(Zhang和Shu,2015年)。
Compared with a traditional tower absorber, membrane-absorption method can increase the contact area of gas and absorption solution, and overcome the entrainment phenomenon caused by the direct contact between two-phase of gas-liquid, it has the advantages, including stable mass transfer interface, large specific surface area, high mass transfer efficiency, low energy consumption, no bubble, no flooding, small equipment size, higher operation flexibility and easy maintenance (Gao et al., 2016).
与传统的塔吸收器相比,膜吸收法可以增加气体与吸收液的接触面积,克服气液两相直接接触引起的夹带现象,具有传质界面稳定、比表面积大、传质效率高、能耗低、无气泡、无液泛、设备尺寸小、操作灵活性高和易于维护等优点(Gao等人,2016年)。
Regarding the demonstration of membrane technologies, there was few demonstration projects had been carried out. Lie J. A. et al. tested the performance of three different types of membranes in capturing ${\mathrm{{CO}}}_{2}$ from the blast furnace gas (BFG). Australia ${\mathrm{{CO}}}_{2}\mathrm{{CRC}}$ project developed a new membrane separation technology, which is applied to separate ${\mathrm{{CO}}}_{2}$ for industry gases $\left( {{\mathrm{{CO}}}_{2}\mathrm{{CRC}}}\right)$ .
关于膜技术的示范,已开展的示范项目很少。Lie J. A. 等人测试了三种不同类型的膜从高炉煤气(BFG)中捕获${\mathrm{{CO}}}_{2}$的性能。澳大利亚${\mathrm{{CO}}}_{2}\mathrm{{CRC}}$项目开发了一种新的膜分离技术,该技术应用于从工业气体$\left( {{\mathrm{{CO}}}_{2}\mathrm{{CRC}}}\right)$中分离${\mathrm{{CO}}}_{2}$。
2.5 Cryogenic Distillation Capture Technology
2.5 低温蒸馏捕集技术
Cryogenic separation technology refers to compression, liquefaction and distillation of a gas mixture at a low temperature and high pressure operating condition, according to different gas composition with different boiling points. ${\mathrm{{CO}}}_{2}$ could be removed and purified from a mixture gas under a certain temperature and pressure condition. The purity of extracted ${\mathrm{{CO}}}_{2}$ by this method is high, but it takes a lot of extra energy in the liquefaction and compression process (Xiao et al., 2012). In nature, the technology is mainly a gas liquefaction process. Normally, a flue gas is compressed and cooled until a phase change of ${\mathrm{{CO}}}_{2}$ , to achieve distillation purpose of separating ${\mathrm{{CO}}}_{2}$ from the flue gas. The advantage of cryogenic separation technology is that the technology can produce liquid ${\mathrm{{CO}}}_{2}$ directly for further transport by truck vehicle, thus avoid further compression and liquefaction of gaseous ${\mathrm{{CO}}}_{2}$ product; the disadvantage of such a technology are in two aspects: one is large energy consumption for cryogenic process, especially for low ${\mathrm{{CO}}}_{2}$ concentration gas stream; the second is blocking issue by water, which will become solid under low temperature. The technology could be more economical for high concentration of ${\mathrm{{CO}}}_{2}$ (above 60%) (Wang,2007).
低温分离技术是指在低温高压操作条件下,根据气体混合物中不同气体成分具有不同沸点,对气体混合物进行压缩、液化和蒸馏。在一定温度和压力条件下,${\mathrm{{CO}}}_{2}$ 可从混合气体中去除并提纯。用这种方法提取的 ${\mathrm{{CO}}}_{2}$ 纯度高,但在液化和压缩过程中需要大量额外能量(Xiao等人,2012年)。本质上,该技术主要是气体液化过程。通常,将烟道气压缩并冷却,直到 ${\mathrm{{CO}}}_{2}$ 发生相变,以实现从烟道气中分离 ${\mathrm{{CO}}}_{2}$ 的蒸馏目的。低温分离技术的优点是该技术可直接生产液态 ${\mathrm{{CO}}}_{2}$,便于通过卡车进一步运输,从而避免气态 ${\mathrm{{CO}}}_{2}$ 产品的进一步压缩和液化;该技术的缺点有两个方面:一是低温过程能耗大,尤其是对于低 ${\mathrm{{CO}}}_{2}$ 浓度气流;二是水的堵塞问题,水在低温下会结冰。对于高浓度的 ${\mathrm{{CO}}}_{2}$(60%以上),该技术可能更经济(Wang,2007年)。
The process flow of a cryogenic distillation capture unit is mainly divided into three parts: compression and cooling of feed gas, rectification separation and cryogenic distillation. Practically, a ${\mathrm{{CO}}}_{2}$ enriched feed gas stream is firstly compressed and cooled to about ${4.4}\mathrm{{Mpa}}$ and ${40}^{ \circ }\mathrm{C}$ , then sent to a cold tank for rectification purification. In the rectification tower, the light component is gradually gathered at the top of the tower, ${\mathrm{{CO}}}_{2}$ is gradually gathered in the tower bottom at high concentration. Finally, the high concentration ${\mathrm{{CO}}}_{2}$ is super cooled to $- {25}^{ \circ }\mathrm{C}$ and put into storage tanks with a liquid phase after throttling. The liquid ${\mathrm{{CO}}}_{2}$ is then delivered to a ${\mathrm{{CO}}}_{2}$ tank by charging pump, and transported to storage sites or utilization facilities by a vehicle. In the project of top gas recycle of blast furnace (TGRBF) under ULCOS program, ${\mathrm{{CO}}}_{2}$ was captured by pressure swing adsorption (PSA) method, followed by a cryogenic distillation technology to generate liquefied ${\mathrm{{CO}}}_{2}$ (Birat,2010).
低温蒸馏捕集单元的工艺流程主要分为三个部分:原料气的压缩和冷却、精馏分离和低温蒸馏。实际上,首先将富含 ${\mathrm{{CO}}}_{2}$ 的原料气流压缩并冷却至约 ${4.4}\mathrm{{Mpa}}$ 和 ${40}^{ \circ }\mathrm{C}$,然后送入冷罐进行精馏提纯。在精馏塔中,轻组分逐渐聚集在塔顶,${\mathrm{{CO}}}_{2}$ 以高浓度逐渐聚集在塔底。最后,将高浓度 ${\mathrm{{CO}}}_{2}$ 过冷至 $- {25}^{ \circ }\mathrm{C}$,经节流后以液相形式放入储存罐。液态 ${\mathrm{{CO}}}_{2}$ 然后通过进料泵输送至 ${\mathrm{{CO}}}_{2}$ 罐,并由车辆运输至储存地点或利用设施。在ULCOS计划下的高炉炉顶煤气回收(TGRBF)项目中,${\mathrm{{CO}}}_{2}$ 通过变压吸附(PSA)法捕集,随后采用低温蒸馏技术生产液化 ${\mathrm{{CO}}}_{2}$(Birat,2010年)。
2.6 Summary
<### 2.6 总结>
For steel/iron industry, carbon capture technology is not only a large-scale ${\mathrm{{CO}}}_{2}$ emission reduction technology with great potential, but also the only technology that can facilitate a large-scale direct emission reduction for steel/iron. It can build the capacity of large-scale enterprises in dealing with sustainable emission reduction without changing their own energy balance system.
对于钢铁行业而言,碳捕集技术不仅是一种具有巨大潜力的大规模${\mathrm{{CO}}}_{2}$减排技术,也是唯一能够助力钢铁行业大规模直接减排的技术。它可以在不改变企业自身能量平衡系统的情况下,增强大型企业应对可持续减排的能力。
A large portion of ${\mathrm{{CO}}}_{2}$ associated with steel/iron production can be sourced from post-combustion flue gas. Correspondingly, post-combustion capture technologies, including absorption separation technology, adsorption separation technology, membrane separation technology, and cryogenic distillation technology can be suitable. Overall, among these technologies, the absorption method is the most mature. In particular, chemical absorption method has already been demonstrated by two large-scale commercial demonstration projects with capacity of one million tons per annum ${\mathrm{{CO}}}_{2}$ for each in coal-fired power generation industry.
与钢铁生产相关的大部分${\mathrm{{CO}}}_{2}$可源自燃烧后烟道气。相应地,燃烧后捕集技术,包括吸收分离技术、吸附分离技术、膜分离技术和低温蒸馏技术都适用。总体而言,在这些技术中,吸收法最为成熟。特别是化学吸收法,已经在燃煤发电行业通过两个年产能均为100万吨${\mathrm{{CO}}}_{2}$的大型商业示范项目得到验证。
The physical absorption method is demonstrated by commercial application in chemical industry very early. It is relatively mature in carbon capture applications. The membrane separation method is also widely used in gas separation industry. In a steel/iron production process, different kinds of capture technologies have different technical applicability and economic performance for different gas sources, as different emission sources have different characteristics. It is necessary to provide an insightful analysis on the technical applicability and economic performance of each capture method for each gas source based on different capture requirements.
物理吸收法很早就已在化工行业得到商业应用验证。它在碳捕集应用中相对成熟。膜分离法也广泛应用于气体分离行业。在钢铁生产过程中,不同的捕集技术对于不同的气体来源具有不同的技术适用性和经济性能,因为不同的排放源具有不同的特性。有必要根据不同的捕集要求,对每种气体来源的每种捕集方法的技术适用性和经济性能进行深入分析。
3 Section 3
3 第3节
3.1 Techno-Economic Analysis of ${\mathrm{{CO}}}_{2}$ Capture from Different Sources
3.1 从不同来源捕获${\mathrm{{CO}}}_{2}$的技术经济分析
Absorption separation, adsorption separation, membrane separation, cryogenic distillation separation and other capture technologies all have their own features in terms of technology applicability and economic performance. Table 7 summarized the overall strength and weakness of each technology (Li, 2014; Han, 2009; Wang, 2016; Huang, 2008). In general, the ${\mathrm{{CO}}}_{2}$ concentration of each emission source in a steel/iron production process is low, thus physical absorption method is obviously unsuitable for its own use. a temperature swing adsorption method may not be suitable for large scale carbon capture because of a slow temperature change. As indicated in Sect. 3, because the composition, pressure and temperature properties of different emission sources in a steel production process are different, the technical and economic may be different when applied to different emission sources.
吸收分离、吸附分离、膜分离、低温精馏分离等捕获技术在技术适用性和经济性能方面都有各自的特点。表7总结了每种技术的总体优缺点(Li,2014;Han,2009;Wang,2016;Huang,2008)。一般来说,钢铁生产过程中各排放源的${\mathrm{{CO}}}_{2}$浓度较低,因此物理吸收法显然不适合其自身使用。变温吸附法可能由于温度变化缓慢而不适合大规模碳捕获。如第3节所述,由于钢铁生产过程中不同排放源的组成、压力和温度特性不同,应用于不同排放源时技术经济可能不同。
Table 7 Characteristics of ${\mathrm{{CO}}}_{2}$ separation technologies
表7 ${\mathrm{{CO}}}_{2}$分离技术的特点
| Technology | Suitable condition | Strength | Weakness | |
| Absorption | Chemical method | Low ${\mathrm{{CO}}}_{2}$ concentration gas source | High ${\mathrm{{CO}}}_{2}$ recovery rate; commercial demonstration available | Chemical process, produce secondary pollution |
| Physical method | High ${\mathrm{{CO}}}_{2}$ concentration gas source | High separation efficiency, low energy consumption | high content ${\mathrm{{CO}}}_{2}$ required | |
| Adsorption | Pressure swing adsorption | High ${\mathrm{{CO}}}_{2}$ concentration gas source | Less corrosion and environmental pollution, high ${\mathrm{{CO}}}_{2}$ recovery rate | Large land use, complex system |
| Temperature swing adsorption | High ${\mathrm{{CO}}}_{2}$ concentration gas source | Less corrosion and environmental pollution. high ${\mathrm{{CO}}}_{2}$ recovery rate | Slow temperature change, large land use, complex system |
(continued)
(续)
Table 7 (continued)
表7(续)
| Technology | Suitable condition | Strength | Weakness |
| Membrane separation | High ${\mathrm{{CO}}}_{2}$ concentration gas source | Small land use, simple system, easy operation and maintenance | High energy consumption, easy to be contaminated with particulate matter |
| Cryogenic distillation | High ${\mathrm{{CO}}}_{2}$ concentration gas source | Liquefaction ${\mathrm{{CO}}}_{2}$ can be obtained directly | High energy consumption, high investment, products can only be liquid |
In China, ${\mathrm{{CO}}}_{2}$ are classified into four different quality specifications, i.e. food grade, industrial grade, internal use, and storage grade. For a concise analysis in this study, industrial grade and food grade are grouped into an industrial grade above category, with ${\mathrm{{CO}}}_{2}$ concentration being greater than ${99.9}\%$ . The internal use require that ${\mathrm{{CO}}}_{2}$ concentration be greater than ${95}\%$ and ${\mathrm{O}}_{2},{\mathrm{H}}_{2}$ , and $\mathrm{{CO}}$ be less than ${0.5}\%$ ; while storage grade only expects the ${95}\%$ of ${\mathrm{{CO}}}_{2}$ . Capture scale can be divided into small scale (10,000 tons/year) and large scale (500,000 tons/year).
在中国,${\mathrm{{CO}}}_{2}$分为四种不同的质量规格,即食品级、工业级、内部使用级和储存级。为了本研究的简洁分析,工业级和食品级归为工业级以上类别,${\mathrm{{CO}}}_{2}$浓度大于${99.9}\%$。内部使用要求${\mathrm{{CO}}}_{2}$浓度大于${95}\%$和${\mathrm{O}}_{2},{\mathrm{H}}_{2}$,且$\mathrm{{CO}}$小于${0.5}\%$;而储存级仅要求${\mathrm{{CO}}}_{2}$的${95}\%$。捕获规模可分为小规模(10000吨/年)和大规模(500000吨/年)。
The captured ${\mathrm{{CO}}}_{2}$ has three different use purposes: internal use, large-scale external use by pipeline transportation and small-scale external use by tanker transportation. The internal use only needs to be pressurized to ${0.6}\mathrm{{Mpa}}$ to be delivered directly by an internal pipeline; the large-scale external use by pipeline transportation requires the ${\mathrm{{CO}}}_{2}$ be transported to designated locations on large scale in a supercritical/dense or a gaseous phase; the small scale external use by tanker requires the captured ${\mathrm{{CO}}}_{2}$ been transported in a liquid phase. Both different specification and different use requirements affect technical and economic assessment of carbon capture technologies.
捕获的${\mathrm{{CO}}}_{2}$有三种不同的用途:内部使用、通过管道运输的大规模外部使用和通过油轮运输的小规模外部使用。内部使用只需加压至${0.6}\mathrm{{Mpa}}$即可通过内部管道直接输送;通过管道运输的大规模外部使用要求${\mathrm{{CO}}}_{2}$以超临界/致密或气相大规模运输到指定地点;通过油轮的小规模外部使用要求捕获的${\mathrm{{CO}}}_{2}$以液相运输。不同的规格和不同的使用要求都会影响碳捕获技术的技术经济评估。
In view of multiple options of capture methods, the technical assessment of a capture method is mainly measured from the perspective of applicability and maturity in ${\mathrm{{CO}}}_{2}$ capture field. The criterion can be benchmarked by three levels: good, average and bad. The economic assessment is mainly measured based on current capital cost and operating cost and potential capital cost and operating cost by year 2025, when is the end year of phase 1 of the Plan of China’s Coal Clean and High Efficiency Utilization Key Project in Facing 2030 Key Project Program (under developing). The operation time assumed to be ${8000}\mathrm{\;h}/$ year and the final ${\mathrm{{CO}}}_{2}$ product is in as gaseous at an atmospheric pressure and temperature of ${25}^{ \circ }\mathrm{C}$ .
鉴于捕获方法有多种选择,捕获方法的技术评估主要从${\mathrm{{CO}}}_{2}$捕获领域的适用性和成熟度角度衡量。该标准可分为三个级别:好、一般和差。经济评估主要基于当前资本成本和运营成本以及到2025年的潜在资本成本和运营成本进行衡量,2025年是《面向2030年中国煤炭清洁高效利用重点项目规划》(正在制定)第一阶段的结束年份。假设运行时间为${8000}\mathrm{\;h}/$年,最终${\mathrm{{CO}}}_{2}$产品在大气压力和温度为${25}^{ \circ }\mathrm{C}$时为气态。
3.2 Techno-Economic Analysis of ${\mathrm{{CO}}}_{2}$ Capture from Blast Furnace Gas
3.2 从高炉煤气中捕集${\mathrm{{CO}}}_{2}$的技术经济分析
Taking a blast furnace gas (BFG) from a Chinese steel/iron mill as a case (Table 8), the content of combustible component CO accounts for about 21.8%, the content of ${\mathrm{{CO}}}_{2}$ and ${\mathrm{N}}_{2}$ are ${23.1}\%$ and 51.7% respectively. Pressure is ${206}\mathrm{{kPa}}$ (gauge pressure) and temperature is ${150}{}^{ \circ }\mathrm{C}$ . The particulate matter concentration in the gas stream is high containing saturated water moisture. The flue gas adopts a TRT system to recover energy in blast furnace gas. After TRT, pressure of the blast furnace gas is slightly higher than an atmospheric pressure, and the temperature is cooled to room temperature. The content of water is also reduced to a saturated level corresponding to the temperature and pressure. Therefore, there are two different gas sources for capture ${\mathrm{{CO}}}_{2}$ from the blast furnace gas, i.e., flue gases before TRT and after TRT, respectively.
以中国钢铁厂的高炉煤气(BFG)为例(表8),可燃成分CO的含量约为21.8%,${\mathrm{{CO}}}_{2}$和${\mathrm{N}}_{2}$的含量分别为${23.1}\%$和51.7%。压力为${206}\mathrm{{kPa}}$(表压),温度为${150}{}^{ \circ }\mathrm{C}$。气流中的颗粒物浓度很高,含有饱和水分。烟气采用TRT系统回收高炉煤气中的能量。经过TRT后,高炉煤气的压力略高于大气压,温度冷却至室温。水的含量也降低到与温度和压力相对应的饱和水平。因此,从高炉煤气中捕集${\mathrm{{CO}}}_{2}$有两种不同的气源,即TRT之前和之后的烟气。
3.2.1 Technical Performance
3.2.1技术性能
After dust removal and purification processes, the blast furnace gas before TRT still has a temperature of ${100}{}^{ \circ }\mathrm{C}$ and a pressure of 0.2-0.3 Mpa. If the purity of the captured ${\mathrm{{CO}}}_{2}$ is required to be industrial grade above for both internal and external uses, chemical absorption method is well technical suitable as it has advantages of high concentration of ${\mathrm{{CO}}}_{2}$ capture through selective absorption and desorption, easy removal of other impurities, and proved by large-scale demonstration project in power-generation industry. It is suitable for the capture of large-scale low concentration ${\mathrm{{CO}}}_{2}$ , but the capture process involves chemical process which is complex to iron/steel industry, and the safety and environmental protection requirements for use and storage of absorbent are high. For internal use of small-scale capture, the absorption method is also applicable.
经过除尘和净化处理后,TRT前的高炉煤气温度仍为${100}{}^{ \circ }\mathrm{C}$,压力为0.2 - 0.3 Mpa。如果捕获的${\mathrm{{CO}}}_{2}$纯度要求为内外使用的工业级以上,化学吸收法在技术上是合适的,因为它具有通过选择性吸收和解吸实现高浓度${\mathrm{{CO}}}_{2}$捕获、易于去除其他杂质的优点,并且在发电行业有大型示范项目证明。它适用于大规模低浓度${\mathrm{{CO}}}_{2}$的捕获,但捕获过程涉及化学过程,对钢铁行业来说较为复杂,并且对吸收剂的使用和储存的安全和环保要求较高。对于小规模捕获的内部使用,吸收法也适用。
The adsorption method can also be used to produce large-scale high concentration ${\mathrm{{CO}}}_{2}$ , however, requiring large land space. The small-scale capture by adsorption is more applicable, due to reduced land use space. In contrast, the cryogenic method is not applicable for ${\mathrm{{CO}}}_{2}$ capture for internal use, because the internal use ${\mathrm{{CO}}}_{2}$ can be delivered through an internal pipeline without liquefaction. With respect to the membrane separation method, it is difficult to guarantee a ${\mathrm{{CO}}}_{2}$ product quality of industrial grade above by membrane technology itself. hence, the applicability of technology only by membrane is poor. However, the combination of membrane separation method and adsorption method (PSA) can overcome the disadvantage of adsorption method (large land use), while ensuring a high quality product by adsorption method. Similarly, the integration of membrane separation with chemical absorption can also ensure a high quality ${\mathrm{{CO}}}_{2}$ product, but it is challenged by complex of membrane separation and chemical reaction process in one system.
吸附法也可用于生产大规模高浓度${\mathrm{{CO}}}_{2}$,然而,需要较大的土地空间。由于土地使用空间减少,吸附法更适用于小规模捕获。相比之下,低温法不适用于内部使用的${\mathrm{{CO}}}_{2}$捕获,因为内部使用的${\mathrm{{CO}}}_{2}$可以通过内部管道输送而无需液化。关于膜分离法,仅靠膜技术本身难以保证工业级以上的${\mathrm{{CO}}}_{2}$产品质量。因此,仅靠膜的技术适用性较差。然而,膜分离法与吸附法(PSA)的结合可以克服吸附法(土地使用量大)的缺点,同时通过吸附法确保高质量产品。同样,膜分离与化学吸收的集成也可以确保高质量的${\mathrm{{CO}}}_{2}$产品,但它受到一个系统中膜分离和化学反应过程复杂性的挑战。
Table 8 Composition of typical blast furnace gas in China
表8中国典型高炉煤气成分
| Composition | ${\mathrm{{CO}}}_{2}$ | CO | ${\mathrm{H}}_{2}$ | ${\mathrm{N}}_{2}$ | ${\mathrm{O}}_{2}$ | ${\mathrm{H}}_{2}\mathrm{O}$ |
| Vol % | 23.1 | 21.8 | 3.2 | 51.7 | 0.2 | Saturation |
For external use of ${\mathrm{{CO}}}_{2}$ with industrial grade above, the demand is normally small. The captured ${\mathrm{{CO}}}_{2}$ needs to be pressurized and liquefied, and temporally stored in a high pressure and low-temperature storage tank. Then, it is transported to the designated site by a truck. Under this circumstance, except chemical absorption and pressure swing adsorption methods, cryogenic method can also be applied. The cryogenic method that combined with membrane separation or pressure swing adsorption can obtain liquefied ${\mathrm{{CO}}}_{2}$ products directly, leading to the improvement of applicability.
对于工业级以上的${\mathrm{{CO}}}_{2}$外部使用,需求通常较小。捕获的${\mathrm{{CO}}}_{2}$需要加压和液化,并临时储存在高压低温储存罐中。然后,用卡车运输到指定地点。在这种情况下,除了化学吸收和变压吸附法外,低温法也可应用。与膜分离或变压吸附相结合的低温法可以直接获得液化的${\mathrm{{CO}}}_{2}$产品,从而提高适用性。
Overall, for internal use of food grade or industrial grade above ${\mathrm{{CO}}}_{2}$ , absorption method is a mature technology, thus more applicable than other methods without consideration of its environmental impacts; otherwise, the combination of membrane and adsorption technology is more suitable. For external use of food grade or industrial grade ${\mathrm{{CO}}}_{2}$ , the scale of project is usually small as market demand is limited. As truck transportation is preferred, membrane separation or pressure swing adsorption combined with cryogenic distillation is also applicable.
总体而言,对于食品级或工业级以上的${\mathrm{{CO}}}_{2}$内部使用,吸收法是一项成熟技术,因此在不考虑其环境影响的情况下比其他方法更适用;否则,膜和吸附技术的结合更合适。对于食品级或工业级${\mathrm{{CO}}}_{2}$的外部使用,由于市场需求有限,项目规模通常较小。由于优先选择卡车运输,膜分离或变压吸附与低温蒸馏相结合也适用。
In the situation that the captured ${\mathrm{{CO}}}_{2}$ merely needs to meet requirements for general storage or internal use purposes ( ${\mathrm{{CO}}}_{2}$ concentration is greater than 95%) (Table 10), chemical absorption method is applicable, but the advantages are less obvious than other technologies. The applicability of pressure swing adsorption method will be improved due to the reduced requirements of ${\mathrm{{CO}}}_{2}$ product, especially for smaller scale, the disadvantage of land use is not so obvious. The use of cryogenic method depends mainly on whether the final ${\mathrm{{CO}}}_{2}$ product needs to be liquefied. Because the concentration requirement of ${\mathrm{{CO}}}_{2}$ product is low, membrane separation method becomes applicable. Through the integration of membrane separation and pressure swing adsorption methods, the weakness of large land use of pressure swing adsorption method will be overcome; integration of membrane and chemical absorption method can further enhance the applicability of absorption method, but the technology is still at early demonstration stage.
在捕获的${\mathrm{{CO}}}_{2}$仅需满足一般储存或内部使用目的要求(${\mathrm{{CO}}}_{2}$浓度大于95%)的情况下(表10),化学吸收法适用,但优势不如其他技术明显。由于对${\mathrm{{CO}}}_{2}$产品的要求降低,变压吸附法的适用性将得到提高,特别是对于较小规模,土地使用的缺点不那么明显。低温法的使用主要取决于最终的${\mathrm{{CO}}}_{2}$产品是否需要液化。因为对${\mathrm{{CO}}}_{2}$产品的浓度要求较低,膜分离法变得适用。通过膜分离和变压吸附法的结合,可以克服变压吸附法土地使用量大的弱点;膜与化学吸收法的结合可以进一步提高吸收法的适用性,但该技术仍处于早期示范阶段。
After the pressure energy of blast furnace gas is recovered by TRT, gas pressure drops slightly to environmental pressure level and temperature decreases to room temperature. Although the change of pressure will affect absorption, adsorption and membrane separation processes more or less. The effect on adsorption and membrane separation methods are slightly greater than that on absorption method, because the required pressure by adsorption and membrane separation is much higher than that of absorption method. Comparing before and after TRT, for membrane separation and pressure swing adsorption method, the main difference is that the investment of a compressor can be saved in the process as pressure of feed gas before TRT is high. Correspondingly, membrane separation and pressure swing adsorption methods are more suitable before TRT than after TRT.
通过TRT回收高炉煤气的压力能后,气体压力略有下降至环境压力水平,温度降至室温。虽然压力变化或多或少会影响吸收、吸附和膜分离过程。对吸附和膜分离方法的影响略大于对吸收法的影响,因为吸附和膜分离所需的压力远高于吸收法。比较TRT前后,对于膜分离和变压吸附法,主要区别在于由于TRT前原料气压力较高,在过程中可以节省压缩机的投资。相应地,膜分离和变压吸附法在TRT前比TRT后更适用。
To summarize, under low concentration requirement of ${\mathrm{{CO}}}_{2}$ products, the applicability of adsorption and membrane separation methods has been improved effectively, especially that of the membrane separation method as its weakness of producing high concentration ${\mathrm{{CO}}}_{2}$ is no longer exist. Further, if membrane separation and pressure swing adsorption are integrated, the applicability of the integrated technology may exceed the absorption method by year 2025, especially in the situation of small-scale ${\mathrm{{CO}}}_{2}$ capture project (Tables 9 and 10).
综上所述,在${\mathrm{{CO}}}_{2}$产品低浓度要求下,吸附和膜分离方法的适用性得到了有效提高,尤其是膜分离方法,因为其产生高浓度${\mathrm{{CO}}}_{2}$的弱点不再存在。此外,如果将膜分离和变压吸附集成,到2025年集成技术的适用性可能会超过吸收法,特别是在小规模${\mathrm{{CO}}}_{2}$捕集项目的情况下(表9和表10)。
3.2.2 Economic Analysis
3.2.2 经济分析
(a) Cost analysis
(a) 成本分析
Because gas temperature and pressure are different before TRT and after TRT, the economic performance of each capture technology is also different before and after TRT. Under the case of capture rate of ${90}\%$ , Tables 11 and 12 respectively illustrate the economics performance of capture technologies for ${\mathrm{{CO}}}_{2}$ products with industrial grade above and storage grade from blast furnace gas before TRT.
由于TRT前后气体温度和压力不同,各捕集技术的经济性能在TRT前后也有所不同。在${90}\%$捕集率的情况下,表11和表12分别说明了TRT前高炉煤气中工业级以上和储存级${\mathrm{{CO}}}_{2}$产品捕集技术的经济性能。
For large-scale industrial grade ${\mathrm{{CO}}}_{2}$ before TRT, the economics of chemical absorption method is the best with current technology, especially the investment cost is significantly lower than that of other methods. However, investment cost of membrane separation method will decrease relatively quickly as it is under a quick development in China. It is estimated that by 2025, the investment cost of membrane-pressure swing adsorption integration method might be close to that of absorption method, due to a pressure of 0.2-0.3 Mpa before TRT can be utilized; meanwhile, its operating cost has obvious advantages over chemical absorption method. In the case of internal use only need 0.6 Mpa compression pressure for ${\mathrm{{CO}}}_{2}$ transportation, it is expected that by 2025, the cost of membrane-pressure swing adsorption method for blast furnace gas could be around $25-27. With the development of membrane absorption technology, its economic performance could keep up with that of chemical absorption method.
对于TRT前大规模工业级${\mathrm{{CO}}}_{2}$,目前技术下化学吸收法经济性最佳,尤其是投资成本显著低于其他方法。然而,膜分离法投资成本在中国快速发展的情况下将相对较快下降。预计到2025年,由于可利用TRT前0.2 - 0.3 Mpa的压力,膜 - 变压吸附集成法投资成本可能接近吸收法;同时,其运行成本比化学吸收法有明显优势。在仅内部使用${\mathrm{{CO}}}_{2}$运输只需0.6 Mpa压缩压力的情况下,预计到2025年,高炉煤气膜 - 变压吸附法成本可能在25 - 27美元左右。随着膜吸收技术的发展,其经济性能可能赶上化学吸收法。
Table 9 Technical applicability of technologies for industrial grade ${\mathrm{{CO}}}_{2}$ from BFG prior to TRT
表9 TRT前高炉煤气中工业级${\mathrm{{CO}}}_{2}$技术的技术适用性
| Product requirement | Technology options | Applicability | Advantage | Disadvantage |
| Internal use | Chemical absorption | Good | Easy to produce high concentration of ${\mathrm{{CO}}}_{2}$ , mature technology, less energy loss in feed gas | Involves a chemical process, the system is complex, negative effect on environment |
| Pressure swing adsorption | Average | Can produce high concentration of ${\mathrm{{CO}}}_{2}$ , can use pressure of feed gas before TRT, easy to be modular developed | High pretreatment requirement, large land use and unit size, complex system | |
| Membrane separation | Bad | N/A | Difficult to obtain high purity ${\mathrm{{CO}}}_{2}$ products alone | |
| Cryogenic distillation | Bad | N/A | Product of is in liquid state, not suitable for internal use | |
| Membrane-absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology | |
| Membrane-adsorption integration | Good | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size; enhanced system stability | Involves two processes of membrane and PSA and their integration: system is complex | |
| Membrane—cryogenic integration | Bad | N/A | Product of is in liquid state, not suitable for internal use |
(continued)
(续)
Table 9 (continued)
表9(续)
| Product requirement | Technology options | Applicability | Advantage | Disadvantage |
| External use | Chemical absorption | Good | Easy to produce high concentration of ${\mathrm{{CO}}}_{2}$ , mature technology, less energy loss in feed gas | Involves a chemical process, the system is complex, negative effect on environment |
| Pressure swing adsorption | Average | Can produce high concentration of ${\mathrm{{CO}}}_{2}$ , can use pressure of BFG before TRT, easy to be modular developed; reduced land use and unit size | High pretreatment requirement, complex system | |
| Membrane separation | Bad | N/A | Difficult to obtain high purity ${\mathrm{{CO}}}_{2}$ products alone | |
| Cryogenic distillation | Average | Product in liquid state, it is suitable for tanker transportation | Large land use and unit size | |
| Membrane—absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment: immature technology | |
| Membrane—adsorption integration | Good | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size; enhanced system stability | Involves two processes of membrane and PSA and their integration: system is complex | |
| Membrane—cryogenic integration | Good | Product in liquid state, suitable for truck transportation | Involves two processes of membrane and cryogenic separation and their integration: system is complex |
Table 10 Technical applicability of technologies for storage Grade ${\mathrm{{CO}}}_{2}$ from BFG prior to TRT
表10 TRT前高炉煤气中储存级${\mathrm{{CO}}}_{2}$技术的技术适用性
| Product requirement | Technology options | Applicability | Advantage | Disadvantage |
| Internal use | Chemical absorption | Good | Easy to produce high concentration of ${\mathrm{{CO}}}_{2}$ , mature technology, less energy loss in feed gas | Involves a chemical process, the system is complex, negative effect on environment |
| Pressure swing adsorption | Average | Can produce high concentration of ${\mathrm{{CO}}}_{2}$ , can use pressure of feed gas before TRT, easy to be modular developed | High pretreatment requirement. large land use and unit size, complex system | |
| Membrane separation | Good | Can produce storage grade ${\mathrm{{CO}}}_{2}$ , land use is small; system is simple; easy to modular development | Lack of project demonstration, rely on membrane development | |
| Cryogenic distillation | Bad | Product of is in liquid state, not suitable for internal use | N/A | |
| Membrane-absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology | |
| Membrane-adsorption Good integration | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size; enhanced system stability | Involves two processes of membrane and PSA and their integration; system is complex |
(continued)
(续)
Table 10 (continued)
表10(续)
| Product requirement | Technology options | Applicability | Advantage | Disadvantage |
| External use | Membrane—cryogenic integration | Bad | Product of is in liquid state, not suitable for internal use | N/A |
| Chemical absorption | Good | Easy to produce high concentration of ${\mathrm{{CO}}}_{2}$ , mature technology, less energy loss in feed gas | Involves a chemical process. the system is complex, negative effect on environment | |
| Pressure swing adsorption | Good | Can produce high concentration of ${\mathrm{{CO}}}_{2}$ , can use pressure of BFG before TRT, easy to be modular developed; reduced land use and unit size | High pretreatment requirement, complex system | |
| Membrane separation | Good | Can produce storage grade ${\mathrm{{CO}}}_{2}$ , land use is small; system is simple; easy to modular development | Lack of project demonstration, rely on membrane development | |
| Cryogenic distillation | Average | Product in liquid state, it is suitable for tanker transportation | Large land use and unit size | |
| Membrane-absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology |
(continued)
(续)
Table 10 (continued)
表10(续)
| Product requirement | Technology options | Applicability | Advantage | Disadvantage |
| Membrane—adsorption integration | Good | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size; enhanced system stability | Involves two processes of membrane and PSA and their integration; system is complex | |
| Membrane—cryogenic integration | Good | Product in liquid state, suitable for truck transportation | Involves two processes of membrane and cryogenic separation and their integration; system is complex |
Table 11 Economic performance of technologies for industrial grade above ${\mathrm{{CO}}}_{2}$ capture from BFG before TRT (at capture rate of 90%)
表11 TRT前高炉煤气中工业级以上${\mathrm{{CO}}}_{2}$捕集技术的经济性能(捕集率90%)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/tonne) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/tonne) |
| Large scale (1.0 mtpa) | Chemical absorption | 90-110 | 30-33 | 85–105 | 28-31 |
| PSA | 110-130 | 29-31 | 90–110 | 27-29 | |
| Membrane—absorption | 100-120 | 30-33 | 90-110 | 28-31 | |
| Membrane-PSAintegration | 120-140 | 28-30 | 90-110 | 25-27 | |
| Small scale (0.1 mtpa) | Chemical absorption | 11–13 | 30-33 | 10-12 | 28-31 |
| PSA | 12-14 | 29-31 | 11–13 | 27-29 | |
| Membrane-absorption | 11-13 | 30-33 | 10–12 | 28-31 | |
| Membrane-PSAintegration | 13-15 | 28-30 | 10–12 | 25-27 |
For storage grade ${\mathrm{{CO}}}_{2}$ , compare to other methods, the advantages of chemical absorption method will be lessened. ${\mathrm{{CO}}}_{2}$ purity requirement has little influence on chemical absorption method in terms of either investment cost or operating cost; while pressure swing adsorption method and membrane separation method are sensitive to product requirements. It is very difficult especially for membrane separation method to satisfy technical requirements of high concentration ${\mathrm{{CO}}}_{2}$ . When the purity requirement is reduced, it is technically feasible for membrane separation method. With the funding support of “membrane method capture ${\mathrm{{CO}}}_{2}$ technology and industrial demonstration project” under the “coal clean and efficient utilization and new energy conversation technology” by Ministry of Science and Technology of China in 2017, it is believed that R&D of membrane technology would be accelerated in the next 5 years. It is expected that by 2025, the investment cost of large-scale capture by membrane technology may be just a little bit higher than that of chemical absorption method. The investment cost and operating cost of membrane integrated with pressure swing adsorption technology would be highly possible less than that of chemical absorption method.
对于储存级${\mathrm{{CO}}}_{2}$,与其他方法相比,化学吸收法优势会减弱。${\mathrm{{CO}}}_{2}$纯度要求对化学吸收法投资成本和运行成本影响不大;而变压吸附法和膜分离法对产品要求敏感。尤其对于膜分离法,满足高浓度${\mathrm{{CO}}}_{2}$技术要求非常困难。当纯度要求降低时,膜分离法在技术上可行。在中国科技部2017年“煤炭清洁高效利用和新能源转换技术”下“膜法捕集${\mathrm{{CO}}}_{2}$技术及工业示范项目”资金支持下,预计未来5年膜技术研发将加速。预计到2025年,膜技术大规模捕集投资成本可能仅略高于化学吸收法。膜与变压吸附技术集成的投资成本和运行成本很可能低于化学吸收法。
| Table 12 | ||||||
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/tonne) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/tonne) | Main changes compared with industrial grade above before TRT |
| Large scale (1.0 mtpa) | Chemical absorption | 90-110 | 30-33 | 85–105 | 28-31 | Investment and operation costs of chemical absorption method are not sensitive to the requirement of ${\mathrm{{CO}}}_{2}$ products |
| PSA | 105-125 | 28-30 | 100-120 | 26-28 | Decrease of ${\mathrm{{CO}}}_{2}$ product concentration requirement, lead to the reduction of investment and operating costs | |
(continued)
(续)
Table 12 (continued)
表12(续)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/tonne) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/tonne) | Main changes compared with industrial grade above before TRT |
| Membrane separation | 115-135 | 30-32 | 100-125 | 26-28 | Membrane separation technology become feasible with reduced ${\mathrm{{CO}}}_{2}$ product requirement; investment cost and operating cost of the membrane reduce significantly | |
| Membrane absorption | 100-120 | 30-33 | 90-110 | 28-31 | Investment and operation costs of chemical absorption method are not sensitive to the requirement of ${\mathrm{{CO}}}_{2}$ products |
(continued)
(续)
Table 12 (continued)
表12(续)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/tonne) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/tonne) | Main changes compared with industrial grade above before TRT |
| Membrane—PSA integration | 110-130 | 27-29 | 80-100 | 24-26 | Decrease of ${\mathrm{{CO}}}_{2}$ product concentration requirement, lead to a significant reduction of investment and operating costs of membrane separation—PSA | |
| Small scale ( 0.1 mtpa) | Chemical absorption | 11-13 | 30-33 | 10-12 | 28-31 | Investment and operation costs of chemical absorption method are not sensitive to the requirement of ${\mathrm{{CO}}}_{2}$ products |
(continued)
(续)
Table 12 (continued)
表12(续)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/tonne) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/tonne) | Main changes compared with industrial grade above before TRT |
| Pressure swing adsorption | 11.5-13.5 | 28-30 | 10.5-12.5 | 26-28 | Decrease of ${\mathrm{{CO}}}_{2}$ product concentration requirement, lead to the reduction of investment and operating costs | |
| Membrane separation | 12-14 | 30-32 | 10.5-12.5 | 26-28 | Membrane separation technology become feasible with reduced ${\mathrm{{CO}}}_{2}$ product requirement; investment cost and operating cost of the membrane reduce significantly |
(continued)
(续)
Table 12 (continued)
表12(续)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/tonne) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/tonne) | Main changes compared with industrial grade above before TRT |
| Membrane absorption | 11-13 | 30-33 | 10-12 | 28-31 | Investment and operation costs of chemical absorption method are not sensitive to the requirement of ${\mathrm{{CO}}}_{2}$ products | |
| Membrane separation—pressure swing adsorption | 12-14 | 27-29 | 9.5-11.5 | 24-26 | Decrease of ${\mathrm{{CO}}}_{2}$ product concentration requirement, lead to a significant reduction of investment and operating costs of membrane separation—PSA |
Before TRT, as the feed gas contains high pressure, the advantage of this high pressure on membrane separation and pressure swing adsorption method is far superior to the chemical absorption method. One direct benefit is that a large-scale compressor for pressurized feed gas can be saved; in the case of after TRT, the investment of the compressor is necessary. The investment cost of a compressor is considerable due to the high volume of feed gas (Table 21).
在TRT之前,由于原料气含有高压,这种高压对膜分离和变压吸附法的优势远优于化学吸收法。一个直接的好处是可以节省用于加压原料气的大型压缩机;在TRT之后的情况下,压缩机的投资是必要的。由于原料气流量大,压缩机的投资成本相当可观(表21)。
Accordingly, the investment cost of pressure swing adsorption method, membrane separation method and membrane-pressure swing adsorption method after TRT is much higher than that of chemical absorption method. Even if after 2025, the investment cost of membrane separation and pressure swing adsorption methods after TRT is still significantly greater than that of chemical absorption method. Nevertheless, for the operating cost of membrane separation and pressure swing adsorption method, in view that the pressure energy in non- ${\mathrm{{CO}}}_{2}$ airflow can be recycled through the existing TRT system, their operating cost won’t be in disadvantageous position compared to chemical absorption method, especially after 2025.
因此,TRT之后变压吸附法、膜分离法和膜 - 变压吸附法的投资成本远高于化学吸收法。即使在2025年之后,TRT之后膜分离和变压吸附法的投资成本仍显著高于化学吸收法。然而,对于膜分离和变压吸附法的运行成本,鉴于非${\mathrm{{CO}}}_{2}$气流中的压力能可通过现有的TRT系统回收利用,它们的运行成本与化学吸收法相比不会处于劣势,特别是在2025年之后。
For small scale capture of 100,000 tons/year, the investment cost of membrane separation and pressure swing adsorption technologies before and after TRT are different. The main reason is a high cost associated with a compressor after TRT. The difference of investment cost for chemical absorption method before and after TRT is very small. Hence, for small scale capture after TRT, the economic performance of membrane separation and pressure swing adsorption is far poorer than that of chemical absorption method; while the economics before TRT is just a little inferior to that of chemical absorption method (Tables 13 and 14).
对于每年10万吨的小规模捕集,TRT前后膜分离和变压吸附技术的投资成本不同。主要原因是TRT之后压缩机成本高昂。化学吸收法TRT前后的投资成本差异非常小。因此,对于TRT之后的小规模捕集,膜分离和变压吸附的经济性能远低于化学吸收法;而TRT之前的经济性仅略逊于化学吸收法(表13和14)。
Table 13 Economic performance of technologies for industrial grade ${\mathrm{{CO}}}_{2}$ capture from BFG after TRT (capture rate of 90%)
表13 TRT后从高炉煤气中捕集工业级${\mathrm{{CO}}}_{2}$的技术经济性能(捕集率90%)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/tonne) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/tonne) | Main changes between prior to TRT and after TRT |
| Large scale (1.0 mtpa) | Chemical absorption | 90-110 | 30-33 | 85–105 | 28-31 | Investment and operating costs are unchanged |
| PSA | 125-145 | 30-32 | 105-115 | 28-30 | Compressor is added, leading to rise of investment and operating costs significantly | |
| Membrane-absorption | 90-110 | 30-33 | 85–105 | 28-31 | Investment and operating costs are unchanged | |
| Membrane-PSA integration | 135-155 | 29-31 | 115-135 | 26-28 | Compressor is added, leading to rise of investment and operating costs significantly | |
| Small scale (0.1 mtpa) | Chemical absorption | 11-13 | 30-33 | 10-12 | 28-31 | Investment and operating costs are unchanged |
(continued)
(续)
Table 13 (continued)
表13(续)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/tonne) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/tonne) | Main changes between prior to TRT and after TRT |
| PSA | 14.5-16.5 | 30-32 | 13.5-15.5 | 28-30 | Compressor is added, leading to rise of investment and operating costs significantly | |
| Membrane—absorption | 11-13 | 30-33 | 10-12 | 28-31 | Investment and operating costs are unchanged | |
| Membrane-PSA integration | 15.5-17.5 | 29-31 | 12.5-14.5 | 26-28 | Compressor is added, leading to rise of investment and operating costs significantly |
Table 14 Economic of capture ${\mathrm{{CO}}}_{2}$ of storage grade from BFG before TRT (90% capture rate)
表14 TRT前从高炉煤气中捕集储存级${\mathrm{{CO}}}_{2}$的经济性(捕集率90%)
| 0 | ||||||
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/ton) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/ton) | Main changes between prior to and after TRT |
| Large scale (1.0 mtpa) | Chemical absorption | 90-110 | 30-33 | 85–105 | 28-31 | Investment and operating costs are unchanged |
| Pressure swing adsorption | 130-150 | 29-31 | 110-130 | 27-29 | Compressor is added, leading to rise of investment and operating costs significantly | |
| Membrane separation | 130-150 | 31-33 | 115-135 | 27-29 | Compressor is added, the investment cost and operating cost rise significantly | |
| Membrane absorption | 100-120 | 30-33 | 90-110 | 28-31 | Investment cost and operating cost are unchanged | |
| Membrane separation—pressure swing adsorption | 125-145 | 28-30 | 95-105 | 25-27 | Compressor is added, leading to rise of investment and operating costs significantly | |
(continued)
(续)
Table 14 (continued)
表14(续)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/ton) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/ton) | Main changes between prior to and after TRT |
| Small scale ( 0.1 mtpa) | Chemical absorption | 11-13 | 30-33 | 10-12 | 28-31 | Investment and operating costs are unchanged |
| Pressure swing adsorption | 14-16 | 29-31 | 13-15 | 27-29 | Compressor is added, leading to rise of investment and operating costs significantly | |
| Membrane separation | 14.5-16.5 | 31-33 | 12.5-14.5 | 27-29 | Compressor is added, leading to rise of investment and operating costs significantly | |
| Membrane absorption | 11-13 | 30-33 | 10-12 | 28-31 | Investment cost and operating cost are unchanged | |
| Membrane separation—pressure swing adsorption | 14.5-16.5 | 28-30 | 12-14 | 25-27 | Compressor is added, leading to rise of investment and operating costs significantly |
(b) Benefit analysis
(b) 效益分析
On the one hand, capturing ${\mathrm{{CO}}}_{2}$ from blast furnace gas (BFG) can reduce emission ${\mathrm{{CO}}}_{2}$ , while the captured ${\mathrm{{CO}}}_{2}$ can be used to place nitrogen in iron/steel making processes; on the other hand, removal of ${\mathrm{{CO}}}_{2}$ from BFG will increase the calorific value of BFG. In case that ${\mathrm{{CO}}}_{2}$ is used to replace nitrogen. Supposing one cubic meter of ${\mathrm{{CO}}}_{2}$ is equivalent to one cubic meter of nitrogen, the benefit of one ton ${\mathrm{{CO}}}_{2}$ is about US$15.0/ton when internal price of nitrogen is US$0.03 $/{\mathrm{m}}^{3}$ . If the captured ${\mathrm{{CO}}}_{2}$ can be sold to oil companies for enhancing oil recovery, the price of ${\mathrm{{CO}}}_{2}$ can reach US$20/ton in China. In fact, when ${\mathrm{{CO}}}_{2}$ concentration meets industrial grade or food grade requirements, market sale price can be as high as US$60.0/ ton.
一方面,从高炉煤气(BFG)中捕集${\mathrm{{CO}}}_{2}$可减少排放${\mathrm{{CO}}}_{2}$,而捕集到的${\mathrm{{CO}}}_{2}$可用于在钢铁制造过程中替代氮气;另一方面,从BFG中去除${\mathrm{{CO}}}_{2}$将提高BFG的热值。如果${\mathrm{{CO}}}_{2}$用于替代氮气。假设1立方米${\mathrm{{CO}}}_{2}$相当于1立方米氮气,当氮气内部价格为0.03$/{\mathrm{m}}^{3}$美元时,1吨${\mathrm{{CO}}}_{2}$的效益约为15.0美元/吨。如果捕集到的${\mathrm{{CO}}}_{2}$可以出售给石油公司用于提高石油采收率,在中国${\mathrm{{CO}}}_{2}$的价格可以达到20美元/吨。实际上,当${\mathrm{{CO}}}_{2}$浓度满足工业级或食品级要求时,市场销售价格可高达60.0美元/吨。
Because of its low calorific value of raw BFG, before ${\mathrm{{CO}}}_{2}$ removal, BFG needs to be mixed with coke oven gas which has high calorific value. Take a mixing ratio of 9:1 as an example, (i.e., nine blast furnace gases mix with one coke oven gas). Based on a case of Chinese iron/steel plant, the unit price of blast furnace gas (BFG) and coke oven gas (COG) is assumed to be US$0.02/Nm ${}^{3}$ , respectively. Consequently, the unit price of original gas mixture will be US$0.046/Nm3. The benefit of blast furnace gas with ${\mathrm{{CO}}}_{2}$ removal is mainly due to the rise of its calorific value in response to the reduced use of coke oven gas. Under different capture rate, the extent of ${\mathrm{{CO}}}_{2}$ removal is different, thus the extent of calorific value increase is also different. Accordingly, the ratio requirement between blast furnace gas and coke oven gas is also different, leading to the cost of mixed gas is also different. The unit cost and benefit of mixed gas with ${\mathrm{{CO}}}_{2}$ removal are shown in Table 15. It is indicated that the higher the capture rate, the more the calorific value increases, the higher the benefit.
由于原始BFG的热值较低,在去除${\mathrm{{CO}}}_{2}$之前,BFG需要与高热值的焦炉煤气混合。以9:1的混合比例为例(即九份高炉煤气与一份焦炉煤气混合)。以中国钢铁厂为例,假设高炉煤气(BFG)和焦炉煤气(COG)的单价分别为0.02美元/Nm${}^{3}$。因此,原始混合气体的单价将为0.046美元/Nm3。去除${\mathrm{{CO}}}_{2}$的高炉煤气的效益主要是由于其热值的提高,这是由于焦炉煤气使用量的减少。在不同的捕集率下,${\mathrm{{CO}}}_{2}$的去除程度不同,因此热值增加的程度也不同。相应地,高炉煤气和焦炉煤气之间的比例要求也不同,导致混合气体的成本也不同。去除${\mathrm{{CO}}}_{2}$的混合气体的单位成本和效益如表15所示。结果表明,捕集率越高,热值增加越多,效益越高。
Although more ${\mathrm{{CO}}}_{2}$ can be removed with high capture rate, resulting in the rise of the combustion calorific value of blast furnace gas, both investment cost and operating cost of capture technologies may be more expensive under high capture rate. For chemical absorption method, it is easy to achieve 90% capture rate, while for membrane separation and PSA methods, when capture rate reaches 90%, the investment cost and operating cost could be very high. In case that the capture rate is reduced to 85%, the investment cost and operating cost of membrane separation and PSA methods could be significantly reduced. Therefore, it is necessary to comprehensively justify the costs and the benefits of ${\mathrm{{CO}}}_{2}$ based on a real specific business case,
虽然高捕集率可以去除更多的${\mathrm{{CO}}}_{2}$,导致高炉煤气的燃烧热值升高,但高捕集率下捕集技术的投资成本和运营成本可能更高。对于化学吸收法,很容易达到90%的捕集率,而对于膜分离和变压吸附法,当捕集率达到90%时,投资成本和运营成本可能非常高。如果捕集率降至85%,膜分离和变压吸附法的投资成本和运营成本可能会显著降低。因此,有必要根据实际具体业务案例全面权衡${\mathrm{{CO}}}_{2}$的成本和效益。
Table 15 Caloric value benefit of ${\mathrm{{CO}}}_{2}$ capture from BFG under different capture rate
表15不同捕集率下从BFG中捕集${\mathrm{{CO}}}_{2}$的热值效益
| Item | Capture rate (%) | BFG proportion | COG proportion | Original cost of mixed gas at ratio of 9:1 of BFG and COG (US\$/Nm3) | Unit cost of mixed gas after ${\mathrm{{CO}}}_{2}$ removal (US\$/Nm3) | Benefit of ${\mathrm{{CO}}}_{2}$ capture from BFG (US\$/Nm3) |
| 1 | 100 | 0.988 | 0.012 | 0.046 | 0.023 | 0.023 |
| 2 | 95 | 0.984 | 0.016 | 0.046 | 0.024 | 0.022 |
| 3 | 90 | 0.98 | 0.02 | 0.046 | 0.025 | 0.021 |
| 4 | 85 | 0.976 | 0.024 | 0.046 | 0.026 | 0.020 |
| 5 | 80 | 0.973 | 0.027 | 0.046 | 0.027 | 0.019 |
| 6 | 70 | 0.966 | 0.034 | 0.046 | 0.029 | 0.017 |
| 7 | 60 | 0.959 | 0.041 | 0.046 | 0.031 | 0.15 |
3.3 Techno-Economic Analysis of ${\mathrm{{CO}}}_{2}$ Capture from Lime Kiln Flue Gas
3.3 从石灰窑烟气中捕集${\mathrm{{CO}}}_{2}$的技术经济分析
3.3.1 Technical Performance
3.3.1 技术性能
The ${\mathrm{{CO}}}_{2}$ in lime kiln flue gas is directly sourced from the calcination of lime. The composition of lime kiln flue gas is similar to that of coal-fired power generation flue gas. ${\mathrm{{CO}}}_{2}$ concentration is about ${15} - {20}\%$ in lime kiln flue gas, which is only a little higher than 11-15% concentration of flue gas of coal-fired power plant, therefore, most of the methods and processes of post-combustion ${\mathrm{{CO}}}_{2}$ capture used by coal-fired power plant basically can be used as a reference to ${\mathrm{{CO}}}_{2}$ capture from lime kiln flue gas by iron/steel industry.
石灰窑烟气中的${\mathrm{{CO}}}_{2}$直接来源于石灰煅烧。石灰窑烟气的成分与燃煤发电烟气相似。石灰窑烟气中${\mathrm{{CO}}}_{2}$浓度约为${15} - {20}\%$,仅略高于燃煤电厂烟气11 - 15%的浓度,因此,燃煤电厂采用的大多数燃烧后${\mathrm{{CO}}}_{2}$捕集方法和工艺基本上可作为钢铁行业从石灰窑烟气中捕集${\mathrm{{CO}}}_{2}$的参考。
Tables 16 and 17 show the technical performance of capture methods for lime kiln flue gas. Compared to blast furnace gas, the ${\mathrm{{CO}}}_{2}$ concentration of lime kiln flue gas is slightly lower; thus, applicability of chemical absorption method for capturing industrial grade above ${\mathrm{{CO}}}_{2}$ is further improved compared to PSA and membrane separation methods. For the capture of storage grade ${\mathrm{{CO}}}_{2}$ , due to the lack of hydrogen and other impurities in lime kiln flue gas, the applicability of membrane separation ${\mathrm{{CO}}}_{2}$ could also be improved, however, the applicability is still at an average level due to the low ${\mathrm{{CO}}}_{2}$ concentration in flue gas. The cryogenic method could be more applicable in case that ${\mathrm{{CO}}}_{2}$ product is required to be transported in liquid phase.
表16和表17展示了石灰窑烟气捕集方法的技术性能。与高炉煤气相比,石灰窑烟气中${\mathrm{{CO}}}_{2}$浓度略低;因此,与变压吸附(PSA)和膜分离方法相比,化学吸收法捕集工业级以上${\mathrm{{CO}}}_{2}$的适用性进一步提高。对于储存级${\mathrm{{CO}}}_{2}$的捕集,由于石灰窑烟气中缺乏氢气等杂质,膜分离${\mathrm{{CO}}}_{2}$的适用性也可能提高,然而,由于烟气中${\mathrm{{CO}}}_{2}$浓度较低,适用性仍处于平均水平。如果需要以液相运输${\mathrm{{CO}}}_{2}$产品,低温法可能更适用。
Table 16 Technical performance of capture methods for industrial grade ${\mathrm{{CO}}}_{2}$ from LKFG
表16 从石灰窑烟气中捕集工业级${\mathrm{{CO}}}_{2}$的方法的技术性能
| Product requirement | Technology options | Applicability | Advantage | Disadvantages |
| Internal use | Chemical absorption | Good | Capable of producing high concentration ${\mathrm{{CO}}}_{2}$ , mature technology | Involves chemical process, complex system and negative effect on environment |
| Pressure swing adsorption | Average | Can produce high concentration of ${\mathrm{{CO}}}_{2}$ ; can be modularly developed | High pretreatment requirement, large land use and unit size, complex system | |
| Membrane separation | Bad | N/A | Poor system reliability, lack of technology demonstration; difficulty to produce high concentration ${\mathrm{{CO}}}_{2}$ | |
| Cryogenic distillation | Bad | N/A | Product of is in liquid state, not suitable for internal use | |
| Membrane—absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology | |
| Membrane-adsorption Go integration | Good | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size; enhanced system reliability | Involves two processes of membrane and PSA and their integration; system is complex |
(continued)
(续)
Table 16 (continued)
表16(续)
| Product requirement | Technology options | Applicability | Advantage | Disadvantages |
| External use | Membrane—cryogenic integration | Bad | N/A | Product of is in liquid state, not suitable for internal use |
| Chemical absorption | Good | Capable of producing high concentration ${\mathrm{{CO}}}_{2}$ , mature technology | Involves a chemical process, the system is complex, negative effect on environment | |
| Pressure swing adsorption | Average | Can produce high concentration of ${\mathrm{{CO}}}_{2}$ ; can be modularly developed | High pretreatment requirement, large land use and unit size, complex system | |
| Membrane separation | Bad | N/A | Poor system reliability, difficult to obtain high purity ${\mathrm{{CO}}}_{2}$ products alone | |
| Cryogenic distillation | Bad | N/A | ${\mathrm{{CO}}}_{2}$ concentration is too low | |
| Membrane—absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology | |
| Membrane-adsorption Goo integration | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size; enhanced system stability | Involves two processes of membrane and PSA and their integration; system is complex |
(continued)
(续)
Table 16 (continued)
表16(续)
| Product requirement | Technology options | Applicability | Advantage | Disadvantages |
| Membrane—cryogenic integration | Good | Product of is in liquid state, suitable for external use by small scale | Not suitable for pipeline transportation in super-critical phase |
Compared to blast furnace gas, another difference is that the nitrogen composition in lime kiln feed gas is high. After the pressurized feed gas pass through membrane or adsorption adsorbents, the nitrogen content in the gas stream is increased due to removal of ${\mathrm{{CO}}}_{2}$ . Without further pressurized, the gas stream with higher nitrogen content can directly generate high purity nitrogen by other nitrogen separation technologies such as membrane and thus produce nitrogen byproduct with low costs. Regarding to chemical absorption method, the separation of nitrogen from gas stream still requires additional pressure and pretreatment. From the perspective of technical maturity, a 100 kilo tonnes per year demonstration project by PSA technology for capturing ${\mathrm{{CO}}}_{2}$ from lime kiln flue gas was carried out by Shougang Jingtang steel plant located in Tangshan, China.
与高炉煤气相比,另一个不同之处在于石灰窑原料气中的氮成分较高。加压原料气通过膜或吸附剂后,由于${\mathrm{{CO}}}_{2}$被去除,气流中的氮含量增加。在不进一步加压的情况下,氮含量较高的气流可通过膜等其他氮分离技术直接生成高纯度氮气,从而低成本地生产氮气副产品。对于化学吸收法,从气流中分离氮气仍需要额外加压和预处理。从技术成熟度来看,位于中国唐山的首钢京唐钢铁厂采用变压吸附(PSA)技术开展了从石灰窑烟气中捕集${\mathrm{{CO}}}_{2}$的每年10万吨示范项目。
Although there is no demonstration projected reported on chemical absorption method, it can be directly applied to lime kiln flue gas with no doubt as it plenty of experience of post-combustion capture demonstration in coal-fired power plant which can certainly referred. Currently membrane separation method lacks technical demonstration, so the maturity of this technology is poor. However, with the accomplishment of the MOST funded “membrane method capture ${\mathrm{{CO}}}_{2}$ technology and industrial demonstration project” under the “coal clean and efficient utilization and new energy conversation technology” by 2022. It can be reasonably estimated that the maturity of membrane method could have a significant improvement by year 2025.
虽然没有关于化学吸收法的示范项目报道,但由于燃煤电厂有大量燃烧后捕集示范经验可供参考,它无疑可直接应用于石灰窑烟气。目前膜分离法缺乏技术示范,因此该技术成熟度较差。然而,随着2022年由科学技术部资助的“煤炭清洁高效利用与新能源转换技术”专项中的“膜法捕集${\mathrm{{CO}}}_{2}$技术及工业示范项目”完成。可以合理估计,到2025年膜法的成熟度会有显著提升。
3.3.2 Economic Analysis
3.3.2 经济分析
Comparatively, because the ${\mathrm{{CO}}}_{2}$ concentration in lime kiln flue gas is slightly higher than in coal-fired power generation flue gas, investment and operating costs of the corresponding technology are slightly lower than post-combustion ${\mathrm{{CO}}}_{2}$ capture in the coal-fired power plant, while also lower than capture technologies applicable to blast furnace gas capture. When considering nitrogen recovery, the investment cost will increase more. Tables 18 and 19 give the economic performance of ${\mathrm{{CO}}}_{2}$ products by industrial above grade and storage grade, respectively.
相比之下,由于石灰窑烟气中的${\mathrm{{CO}}}_{2}$浓度略高于燃煤发电烟气,相应技术的投资和运营成本略低于燃煤电厂的燃烧后${\mathrm{{CO}}}_{2}$捕集,同时也低于适用于高炉煤气捕集的捕集技术。考虑到氮气回收时,投资成本增加幅度更大。表18和表19分别给出了工业以上等级和储存等级的${\mathrm{{CO}}}_{2}$产品的经济性能。
Table 17 Technical performance of capture methods for storage grade ${\mathrm{{CO}}}_{2}$ from LKFG
表17 来自石灰窑烟道气的储存级${\mathrm{{CO}}}_{2}$捕集方法的技术性能
| Product requirement | Technology options | Applicability | Advantage | Disadvantages |
| Internal use | Chemical absorption | Good | Capable of producing high concentration ${\mathrm{{CO}}}_{2}$ , mature technology | Involves chemical process, complex system and negative effect on environment |
| Pressure swing adsorption | Average | Can produce high concentration of ${\mathrm{{CO}}}_{2}$ and can be modularly developed | High pretreatment requirement, large land use and unit size, complex system | |
| Membrane separation | Average | Can produce storage grade ${\mathrm{{CO}}}_{2}$ and can be modularly developed | Poor system reliability, lack of technology demonstration | |
| Cryogenic distillation | Bad | N/A | Product of is in liquid state, not suitable for internal use | |
| Membrane—absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology | |
| Membrane—adsorption integration | Good | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size; enhanced system stability | Involves two processes of membrane and PSA and their integration; system is complex | |
| Membrane—cryogenic integration | Bad | N/A | Product of is in liquid state, not suitable for internal use |
(continued)
(续)
Table 17 (continued)
表17(续)
| Product requirement | Technology options | Applicability | Advantage | Disadvantages |
| External use | Chemical absorption | Good | Capable of producing high concentration ${\mathrm{{CO}}}_{2}$ , mature technology | Involves chemical process, complex system and negative effect on environment |
| Pressure swing adsorption | Average | Can produce high concentration of ${\mathrm{{CO}}}_{2}$ and can be modularly developed | High pretreatment requirement, large land use and unit size, complex system | |
| Membrane separation | Average | Can produce storage grade ${\mathrm{{CO}}}_{2}$ and can be modularly developed | Poor system reliability, lack of technology demonstration | |
| Cryogenic distillation | Bad | N/A | ${\mathrm{{CO}}}_{2}$ concentration is too low | |
| Membrane—absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology | |
| Membrane—adsorption integration | Good | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size; enhanced system stability | Involves two processes of membrane and PSA and their integration; system is complex | |
| Membrane—cryogenic integration | Good | Product of is in liquid state, suitable for external use by small scale | Not suitable for pipeline transportation in super-critical phase |
For the capture of industrial grade above ${\mathrm{{CO}}}_{2}$ , the investment cost of chemical absorption method is far below that of pressure swing adsorption and other methods; even by 2025, it is still the case. For operating cost, chemical absorption method is lower than that of other methods under current technical condition, however, it might be at the same level as other methods by 2025. Because membrane method and pressure swing adsorption method are easy to produce high purity nitrogen as a by-product, the economics of membrane and pressure swing adsorption methods can be greatly improved, and can probably be higher than chemical absorption method, when this nitrogen benefit is included, At an internal price of nitrogen being USD0.03/Nm ${}^{3}$ , the benefit of nitrogen product could be as high as USD22.0/tonne. Take a lime kiln flue gas with ${17}\% {\mathrm{{CO}}}_{2}$ and ${72}\%$ nitrogen as an example, capture one tonne ${\mathrm{{CO}}}_{2}$ can generate about $53 of nitrogen benefit under scenario of ${\mathrm{{CO}}}_{2}$ capture rate being ${90}\%$ , and nitrogen capture rate being 80%.
对于捕获高于${\mathrm{{CO}}}_{2}$的工业级产品,化学吸收法的投资成本远低于变压吸附等方法;即使到2025年,情况依然如此。对于运营成本,在当前技术条件下,化学吸收法低于其他方法,然而,到2025年可能与其他方法处于同一水平。由于膜法和变压吸附法容易产生高纯度氮气作为副产品,当计入这种氮气收益时,膜法和变压吸附法的经济性可以大大提高,甚至可能高于化学吸收法。在氮气内部价格为0.03美元/立方米${}^{3}$的情况下,氮气产品的收益可能高达22.0美元/吨。以含有${17}\% {\mathrm{{CO}}}_{2}$和${72}\%$氮气的石灰窑烟气为例,在${\mathrm{{CO}}}_{2}$捕获率为${90}\%$且氮气捕获率为80%的情况下,捕获一吨${\mathrm{{CO}}}_{2}$可产生约53美元的氮气收益。
Table 18 Economic performance of technologies for industrial grade from LKFG (at capture rate of 90%)
表18 来自石灰窑烟道气的工业级技术的经济性能(捕获率为90%)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/ton) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/ton) |
| Large scale (1.0 mtpa) | Chemical absorption | 100-120 | 32-35 | 95-115 | 30-33 |
| PSA | 140-160 | 33-35 | 120-140 | 30-33 | |
| PSA & ${\mathrm{N}}_{2}$ recovery | 150-170 | 36-38 | 140-160 | 33-35 | |
| Membrane absorption | 100-120 | 32-35 | 95-115 | 30-33 | |
| Membrane-PSA integration | 145-165 | 32-34 | 120-140 | 29-31 | |
| Membrane-PSA integration & ${\mathrm{N}}_{2}$ recovery | 155-175 | 35-37 | 130-150 | 32-34 | |
| Small scale ( 0.1 mtpa) | Chemical absorption | 13-15 | 32-35 | 13-15 | 30-33 |
| PSA | 16-18 | 33-35 | 14-16 | 30-33 | |
| PSA & ${\mathrm{N}}_{2}$ recovery | 17-19 | 36-38 | 16-18 | 33-35 | |
| Membrane absorption | 13-15 | 32-35 | 13–15 | 30-33 | |
| Membrane-PSA integration | 16–18 | 32-34 | 13–15 | 29-32 | |
| Membrane-PSA integration & ${\mathrm{N}}_{2}$ recovery | 18–20 | 35-37 | 16–18 | 32-35 |
Table 19 Economic performance of technologies for storage grade from LKFG (at capture rate of ${90}\%$ )
表19 石灰窑烟气储存级技术的经济性能(捕获率为${90}\%$)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/ton) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/ton) |
| Large scale (1.0 mtpa) | Chemical absorption | 100-120 | 32-35 | 95-115 | 30-33 |
| PSA | 130-150 | 32-34 | 110-130 | 29-32 | |
| PSA & ${\mathrm{N}}_{2}$ recovery | 140-160 | 35-37 | 130-150 | 32-34 | |
| Membrane absorption | 100-120 | 32-35 | 95-115 | 30-33 | |
| Membrane separation | 135-155 | 33-35 | 105-125 | 29-32 | |
| Membrane-& ${\mathrm{N}}_{2}$ recovery | 145-165 | 36-38 | 105-125 | 32-35 | |
| Membrane-PSA integration | 135-155 | 31-33 | 110-130 | 28-30 | |
| Membrane-PSA integration & ${\mathrm{N}}_{2}$ recovery | 145-165 | 34-36 | 120-140 | 31-33 | |
| 100,000 tons/year | Chemical absorption | 13-15 | 32-35 | 13-15 | 30-33 |
| pressure swing adsorption | 15-17 | 32-34 | 13-15 | 29-32 | |
| Adsorption $+ {\mathrm{N}}_{2}$ recovery | 16-18 | 35-37 | 15-17 | 32-34 | |
| Membrane absorption | 13-15 | 32-35 | 13-15 | 30-33 | |
| Membrane separation | 15-17 | 33-35 | 13-15 | 29-32 | |
| Membrane separation $+ {\mathrm{N}}_{2}$ recovery | 16-18 | 36-38 | 15-17 | 32-34 | |
| Membrane separation—pressure swing adsorption | 15-17 | 31-33 | 12-14 | 28-31 | |
| Membrane separation—pressure swing adsorption + ${\mathrm{N}}_{2}$ recovery | 17-19 | 34-36 | 15-17 | 31-34 |
3.4 Techno-Economic Analysis of ${\mathrm{{CO}}}_{2}$ Capture from for Hot Blast Furnace Flue Gas
3.4 从热风炉烟道气中捕获${\mathrm{{CO}}}_{2}$的技术经济分析
3.4.1 Technical Analysis
3.4.1 技术分析
Hot blast furnace is one of the important facilities in the process of iron-making. Although the flue gas produced by a single hot blast furnace is generated intermittently, in the actual production process, multiple hot blast furnaces share one flue gas discharge pipeline; therefore, at the end of the pipeline, the discharge of flue gas is almost continuous. The temperature of hot blast furnace flue gas is usually high, being about ${250} - {300}{}^{ \circ }\mathrm{C}$ ; on the one hand, the high temperature has influence on some carbon capture technologies; on the other hand, the high temperature waste heat can also be recycled to offset the energy consumption of carbon capture.
热风炉是炼铁过程中的重要设施之一。虽然单个热风炉产生的烟气是间歇性的,但在实际生产过程中,多个热风炉共用一条烟气排放管道;因此,在管道末端,烟气排放几乎是连续的。热风炉烟气温度通常较高,约为${250} - {300}{}^{ \circ }\mathrm{C}$;一方面,高温对一些碳捕集技术有影响;另一方面,高温余热也可回收利用,以抵消碳捕集的能耗。
The composition of a typical hot blast furnace flue gas in Chinese steel/iron plant is shown in Table 20. The ${\mathrm{{CO}}}_{2}$ concentration is ${28.52}\%$ , which is much higher than that of blast furnace gas, lime kiln flue gas and other major ${\mathrm{{CO}}}_{2}$ emission sources in a steel plant. This high concentration of hot blast flue gas can not only benefit the applicability of chemical absorption method, but also pressure swing adsorption method and membrane separation method (Tables 4, 5, 6,7,8,9,10,11,12,13,14and 15). However, the high temperature of flue gas could affect the chemical absorbent consumption and the use of pressure swing adsorption. The advantages of absorption method and pressure swing adsorption method are able to play well when the temperature is reduced; for the membrane separation method, by using high temperature resistant membrane materials, such as zeolite membrane, it can be operated at high temperature; while for pressure swing adsorption method, the high temperature has a negative effect.
中国钢铁厂典型热风炉烟气的成分如表20所示。${\mathrm{{CO}}}_{2}$浓度为${28.52}\%$,远高于钢铁厂高炉煤气、石灰窑烟气等主要${\mathrm{{CO}}}_{2}$排放源。这种高浓度的热风炉烟气不仅有利于化学吸收法的适用性,也有利于变压吸附法和膜分离法(表4、5、6、7、8、9、10、11、12、13、14和15)。然而,烟气的高温会影响化学吸收剂的消耗和变压吸附的使用。当温度降低时,吸收法和变压吸附法的优势能够得到很好的发挥;对于膜分离法,通过使用耐高温膜材料,如沸石膜,可以在高温下运行;而对于变压吸附法,高温有负面影响。
Table 20 Composition of typical hot blast furnace flue gas in China
表20中国典型热风炉烟气成分
| Composition | ${\mathrm{{CO}}}_{2}$ | ${\mathrm{N}}_{2}$ | ${\mathrm{O}}_{2}$ | ${\mathrm{H}}_{2}\mathrm{O}$ | Ash/(mg m ${}^{-3}$ ) |
| Hot blast furnace flue gas | 28.52 | 65.15 | 2.51 | 3.82 | 5 |
Specifically, capture ${\mathrm{{CO}}}_{2}$ with industrial grade above by large scale for internal use, the chemical absorption method is more applicable, although there is a negative effect of high temperature. Due to the higher ${\mathrm{{CO}}}_{2}$ concentration in feed gas, the applicability of pressure swing adsorption method is improved. Similarly, the applicability of the pressure swing adsorption method integrated with membrane separation will also be more enhanced than that of a simple adsorption method. For the storage grade capture, both absorption and pressure swing adsorption methods can be applied when the temperature is reduced, compared to lime kiln flue gas and blast furnace gas, membrane separation method is more applicable. The applicability of pressure swing adsorption integrated with membrane separation will be further improved.
具体而言,大规模捕集工业级以上的${\mathrm{{CO}}}_{2}$供内部使用,化学吸收法更适用,尽管存在高温负面影响。由于原料气中${\mathrm{{CO}}}_{2}$浓度较高,变压吸附法的适用性得到提高。同样,与膜分离集成的变压吸附法的适用性也将比单纯的吸附法更强力。对于储存级捕集,与石灰窑烟气和高炉煤气相比,当温度降低时,吸收法和变压吸附法均可应用,膜分离法更适用。与膜分离集成的变压吸附法的适用性将进一步提高。
Similar to lime kiln flue gas, the nitrogen composition of hot blast furnace gas is high. After the pressurized feed gas passes through membrane material or pressure swing adsorption unit, the nitrogen content in the gas stream is increased due to removal of ${\mathrm{{CO}}}_{2}$ . Without further pressurized, the gas stream with higher nitrogen content can directly generate high purity nitrogen by other nitrogen separation technologies such as membrane and thus produce nitrogen by-product with low costs. While for the chemical absorption method, the gas stream rich in nitrogen still requires further high energy consumption to separate nitrogen. It is difficult for chemical absorption method itself to obtain high purity nitrogen as a by-product.
与石灰窑烟气类似,热风炉煤气中的氮气成分较高。加压原料气通过膜材料或变压吸附单元后,由于${\mathrm{{CO}}}_{2}$的去除,气流中的氮气含量增加。无需进一步加压,氮气含量较高的气流可通过膜等其他氮气分离技术直接产生高纯度氮气,从而低成本生产氮气副产品。而对于化学吸收法,富含氮气的气流仍需要进一步高能耗来分离氮气。化学吸收法本身很难获得高纯度氮气作为副产品。
From the perspective of technology maturity, the maturity of chemical absorption method is higher than that of membrane separation and pressure swing adsorption. The composition of flue gas from a hot blast furnace contains high concentration ${\mathrm{{CO}}}_{2}$ , hence, the experience of industrial gases separation by membrane separation method and pressure swing adsorption method can be referred, although there is still lack of direct technical demonstrations of these two methods (Table 21).
从技术成熟度来看,化学吸收法的成熟度高于膜分离法和变压吸附法。热风炉烟气成分中含有高浓度${\mathrm{{CO}}}_{2}$,因此,虽然这两种方法仍缺乏直接的技术示范,但可参考膜分离法和变压吸附法进行工业气体分离的经验(表21)。
3.4.2 Economic Analysis
3.4.2经济分析
The ${\mathrm{{CO}}}_{2}$ concentration in hot blast furnace flue gas is higher than that in blast furnace gas. It is nearly double the ${\mathrm{{CO}}}_{2}$ concentration in lime kiln flue gas. The investment and operating costs of the corresponding capture technologies are far less than that of hot blast furnace gas and blast furnace gas. When considering the recovery of nitrogen, the investment cost will increase. Tables 22 and 23 give the economics of ${\mathrm{{CO}}}_{2}$ product of industrial grade and storage grade, respectively.
热风炉烟气中的${\mathrm{{CO}}}_{2}$浓度高于高炉煤气中的浓度。它几乎是石灰窑烟气中${\mathrm{{CO}}}_{2}$浓度的两倍。相应捕集技术的投资和运营成本远低于高炉煤气和焦炉煤气。若考虑氮气回收,投资成本将会增加。表22和表23分别给出了工业级和储存级${\mathrm{{CO}}}_{2}$产品的经济性。
Table 21 Technical performance of technologies for hot blast furnace flue gas
表21热风炉烟气捕集技术的技术性能
| Product requirement | Technology | Applicability | Disadvantages | |
| Industrial grade | Chemical absorption | Good | Capable of producing high concentration ${\mathrm{{CO}}}_{2}$ , mature technology | Involves chemical process, complex system and negative effect on environment |
| pressure swing adsorption | Average | Easy to be modularly developed, can produce by-product nitrogen | High pretreatment requirement, large land use and unit size, complex system | |
| Membrane separation | Bad | N/A | Poor system reliability, lack of technology demonstration | |
| Cryogenic distillation | Bad | N/A | Product of is in liquid state, not suitable for internal use | |
| Membrane—absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology | |
| Membrane—adsorption integration | Good | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size; enhanced system stability | Involves two processes of membrane and PSA and their integration; system is complex | |
| Membrane—cryogenic integration | Average | Product is in liquid state, suitable for external use by small scale | Product of is in liquid state, not suitable for internal use |
(continued)
(续)
Table 21 (continued)
表21(续)
| Product requirement | Technology | Applicability | Disadvantages | |
| Storage grade | Chemical absorption | Good | Capable of producing high concentration ${\mathrm{{CO}}}_{2}$ , mature technology | Involves chemical process, complex system and negative effect on environment |
| Pressure swing adsorption | Good | Easy to be modularly developed, can produce by-product nitrogen | High pretreatment requirement, large land use and unit size, complex system | |
| Membrane separation | Good | Can be modularly developed, can produce by-product nitrogen | Poor system reliability, lack of technology demonstration | |
| Cryogenic distillation | Bad | N/A | ${\mathrm{{CO}}}_{2}$ concentration is too low | |
| Membrane—absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology | |
| Membrane—adsorption integration | Good | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size; enhanced system stability | Involves two processes of membrane and PSA and their integration; system is complex | |
| Membrane—cryogenic integration | Average | Product is in liquid state, suitable for external use by small scale | Not suitable for pipeline transportation in super-critical phase |
Table 22 Economic performance of technologies for industrial grade from hot blast furnace flue gas (at capture rate of 90%)
表22热风炉烟气工业级捕集技术的经济性能(捕集率90%)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/tonne) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/tonne) |
| Large scale (1.0 mtpa) | Chemical absorption | 80–100 | 28-30 | 75-95 | 27-29 |
| PSA | 110-130 | 28-30 | 100–120 | 26-28 | |
| PSA & ${\mathrm{N}}_{2}$ recovery | 125-145 | 31-33 | 115-135 | 29-31 | |
| Membrane absorption | 80-100 | 28-30 | 75-95 | 27-29 | |
| Membrane-PSA integration | 120-140 | 27-29 | 110-130 | 25-27 | |
| Membrane-PSA integration & ${\mathrm{N}}_{2}$ recovery | 135-155 | 33-35 | 120-140 | 30-32 | |
| Small scale (0.1 mtpa) | Chemical absorption | 11-13 | 28-30 | 10-11 | 27-29 |
| PSA | 13-15 | 28-30 | 12-14 | 26-28 | |
| PSA & ${\mathrm{N}}_{2}$ recovery | 15-17 | 31-33 | 14-16 | 29-32 | |
| Membrane absorption | 11-13 | 28-30 | 10-11 | 27-29 | |
| Membrane-PSA integration | 14-16 | 27-29 | 13–15 | 25-27 | |
| Membrane-PSA integration & ${\mathrm{N}}_{2}$ recovery | 16-18 | 33-35 | 16–18 | 30-32 |
For capture of industrial grade above ${\mathrm{{CO}}}_{2}$ , the investment cost of chemical absorption method is still lower than that of PSA and other methods, even by 2025. However, compared with blast furnace gas, this gap is much smaller. The operating cost of PSA method is low. By 2025, the operating cost of pressure swing adsorption method may be lower than that of absorption method. In particular, membrane-PSA integration method is very likely to be lower than absorption method. If considering the benefit of by-product nitrogen, the cost of membrane-PSA integration method can be greatly improved, and will be lower than that of chemical absorption method.
对于捕集高于${\mathrm{{CO}}}_{2}$的工业级产品,即使到2025年,化学吸收法的投资成本仍低于变压吸附法和其他方法。然而,与高炉煤气相比,这一差距要小得多。变压吸附法的运营成本较低。到2025年,变压吸附法的运营成本可能低于吸收法。特别是,膜 - 变压吸附集成法很可能低于吸收法。若考虑副产品氮气的收益,膜 - 变压吸附集成法的成本可大幅降低,并将低于化学吸收法。
For ${\mathrm{{CO}}}_{2}$ capture of storage grade, the economics of chemical absorption method is slight lower than that of industrial grade capture. The investment cost and operating cost of PSA method will be further declined. The cost of membrane separation is also close to the cost of absorption method and PSA method. It may likely be lower than the cost of PSA method in 2025. The cost of membrane-PSA integration method could be further reduced than that of single membrane separation method and single PSA method. At an internal price of nitrogen being USD0.03/Nm ${}^{3}$ , the benefit of nitrogen product could be as high as USD22.0/tonne. Take a lime kiln flue gas with ${28}\% {\mathrm{{CO}}}_{2}$ and ${65}\%$ nitrogen as an example, capture one tonne ${\mathrm{{CO}}}_{2}$ can generate about $30 of nitrogen benefit under scenario of ${\mathrm{{CO}}}_{2}$ capture rate being ${90}\%$ , and nitrogen capture rate being 80%. Compared with the capture of lime kiln flue gas, although the cost of ${\mathrm{{CO}}}_{2}$ capture decreases, the benefit of nitrogen also decreases.
对于储存级${\mathrm{{CO}}}_{2}$的捕集,化学吸收法的经济性略低于工业级捕集。变压吸附法的投资成本和运营成本将进一步下降。膜分离成本也接近吸收法和变压吸附法的成本。到2025年可能低于变压吸附法的成本。膜 - 变压吸附集成法的成本可比单膜分离法和单变压吸附法进一步降低。在氮气内部价格为0.03美元/立方米${}^{3}$时,氮气产品的收益可达22.0美元/吨。以含${28}\% {\mathrm{{CO}}}_{2}$和${65}\%$氮气的石灰窑烟气为例,在${\mathrm{{CO}}}_{2}$捕集率为${90}\%$且氮气捕集率为80%的情况下,捕集1吨${\mathrm{{CO}}}_{2}$可产生约30美元的氮气收益。与石灰窑烟气捕集相比,虽然${\mathrm{{CO}}}_{2}$捕集成本降低,但氮气收益也降低。
Table 23 Economic performance of technologies for storage grade from hot blast furnace flue gas (at capture rate of 90%)
表23热风炉烟气储存级捕集技术的经济性能(捕集率90%)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/ton) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/ton) |
| Large scale (1.0 mtpa) | Chemical absorption | 80–100 | 28-30 | 75-95 | 27-29 |
| PSA | 100-120 | 27-29 | 90-110 | 25-27 | |
| PSA & ${\mathrm{N}}_{2}$ recovery | 110-130 | 30-32 | 100-120 | 28-30 | |
| Membrane absorption | 80–100 | 28-30 | 75-95 | 27-29 | |
| Membrane seperation | 105-125 | 28-30 | 90-110 | 25-27 | |
| Membrane-& ${\mathrm{N}}_{2}$ recovery | 115-135 | 31-33 | 100-120 | 28-30 | |
| Membrane-PSA integration | 110-130 | 28-30 | 95-115 | 25-27 | |
| Membrane-PSA integration & ${\mathrm{N}}_{2}$ recovery | 120-140 | 31-33 | 105-125 | 28-30 | |
| Small scale ( 0.1 mtpa) | Chemical absorption | 11-13 | 28-30 | 10-11 | 27-29 |
| PSA | 12-14 | 27-29 | 11-13 | 25-27 | |
| PSA & ${\mathrm{N}}_{2}$ recovery | 14-16 | 30-32 | 13-15 | 28-30 | |
| Membrane absorption | 11-13 | 28-30 | 10-11 | 27-29 | |
| Membrane seperation | 13-15 | 28-30 | 11-13 | 25-27 | |
| Membrane-& ${\mathrm{N}}_{2}$ recovery | 15-17 | 31-33 | 13-15 | 28-30 | |
| Membrane-PSA integration | 13-15 | 26-28 | 12-14 | 24-26 | |
| Membrane-PSA integration & ${\mathrm{N}}_{2}$ recovery | 15-17 | 29-31 | 14-16 | 27-29 |
3.5 Techno-Economic Analysis of ${\mathrm{{CO}}}_{2}$ Capture for Linz-Donawitz Gas
3.5 林茨-多纳维茨气体${\mathrm{{CO}}}_{2}$捕集的技术经济分析
In a Linz-Donawitz steel-making process, under high temperature, carbon in molten iron reacts with blown oxygen to generate a mixture of carbon monoxide and a small amount of carbon dioxide. The recovered Linz-Donawitz gas (LDG) contains about ${60}\%$ of CO,15-20% of ${\mathrm{{CO}}}_{2}$ , as well as nitrogen, hydrogen and trace oxygen. Capturing ${\mathrm{{CO}}}_{2}$ from Linz-Donawitz gas is not only the need for carbon reduction, but also anti-corrosion of gas pipe caused by the presence of ${\mathrm{{CO}}}_{2}$ . Because the amount of Linz-Donawitz gas is not generated at a stable level in a smelting process, the gas usually needs to be stored in a gas cabinet temporarily after full dusting and cooling. The capacity of the gas cabinet determines the gas buffer time in the gas cabinet.
在林茨-多纳维茨炼钢工艺中,高温下铁水中的碳与吹入的氧气反应生成一氧化碳和少量二氧化碳的混合物。回收的林茨-多纳维茨气体(LDG)含有约${60}\%$的CO、15 - 20%的${\mathrm{{CO}}}_{2}$,以及氮气、氢气和微量氧气。从林茨-多纳维茨气体中捕集${\mathrm{{CO}}}_{2}$不仅是碳减排的需要,也是防止${\mathrm{{CO}}}_{2}$对气管腐蚀的需要。由于在冶炼过程中林茨-多纳维茨气体的产生量不稳定,该气体通常在完全除尘和冷却后需要临时储存在气柜中。气柜的容量决定了气体在气柜中的缓冲时间。
With the gas cabinet storage, “intermittent producing, continuous use” of the gas can be realized. ${\mathrm{{CO}}}_{2}$ in the gas stream can be captured either before the gas stream enters the cabinet or after the gas stream enters the cabinet. Capturing ${\mathrm{{CO}}}_{2}$ before the cabinet can reduce the volume of the gas stream, and increase the buffer efficiency of a cabinet; on the other hand, the dissolution of ${\mathrm{{CO}}}_{2}$ is reduced at a water sealing process through removing ${\mathrm{{CO}}}_{2}$ in the gas stream, thereby, the corrosivity of the gas stream is further undermined. When capturing ${\mathrm{{CO}}}_{2}$ after the gas cabinet, the corresponding gas volume can be continuous and stable which is particularly helpful to some capture technologies.
通过气柜储存,可以实现气体的“间歇生产、连续使用”。气流中的${\mathrm{{CO}}}_{2}$可以在气流进入气柜之前或之后进行捕集。在气柜前捕集${\mathrm{{CO}}}_{2}$可以减小气流体积,提高气柜的缓冲效率;另一方面,通过去除气流中的${\mathrm{{CO}}}_{2}$,在水封过程中${\mathrm{{CO}}}_{2}$的溶解减少,从而进一步降低气流的腐蚀性。在气柜后捕集${\mathrm{{CO}}}_{2}$时,相应的气体体积可以连续稳定,这对某些捕集技术特别有帮助。
3.5.1 Technical Analysis
3.5.1 技术分析
For capture ${\mathrm{{CO}}}_{2}$ from a LDG stream before a gas cabinet, whatever the captured ${\mathrm{{CO}}}_{2}$ product is at industrial above grade or storage grade, whatever it is by large scale or small scale, overall, the technical applicability of chemical absorption method and membrane-absorption method is obviously better than that of other methods. The main reason is that the intermittence of Linz-Donawitz gas before a cabinet storage has less influence on a chemical absorption process, while greater influence on membrane separation and pressure swing adsorption processes that require compression operation of a compressor. Especially for a centrifugal compressor, a gas stream without stable volume can result in many technical problems (Table 32).
对于在气柜之前从林茨-多纳维茨气流中捕集${\mathrm{{CO}}}_{2}$而言,无论捕集到的${\mathrm{{CO}}}_{2}$产物是工业级以上还是储存级,无论规模大小,总体而言,化学吸收法和膜吸收法的技术适用性明显优于其他方法。主要原因是气柜储存之前的林茨-多纳维茨气体的间歇性对化学吸收过程影响较小,而对需要压缩机压缩操作的膜分离和变压吸附过程影响较大。特别是对于离心压缩机,不稳定体积的气流会导致许多技术问题(表32)。
However, when capture ${\mathrm{{CO}}}_{2}$ from LDG stream after a gas cabinet, if capturing ${\mathrm{{CO}}}_{2}$ for internal use, pressure swing adsorption method and membrane separation method can also be applicable since feed gas stream can be adjusted at stable level with the cabinet. Another technical advantage of membrane and PSA separation methods is that the ${\mathrm{{CO}}}_{2}$ removed gas stream can be directly transported through pipeline without further pressure because the feed gas has been pressurized for removal the ${\mathrm{{CO}}}_{2}$ . The integration of membrane separation and PSA can further enhance the advantage. If capturing ${\mathrm{{CO}}}_{2}$ for industrial grade above, absorption method is more applicable (Tables 24, 25 and 26).
然而,当在气柜之后从林茨-多纳维茨气流中捕集${\mathrm{{CO}}}_{2}$时,如果捕集${\mathrm{{CO}}}_{2}$以供内部使用,变压吸附法和膜分离法也可适用,因为进料气流可通过气柜调节至稳定水平。膜和变压吸附分离方法的另一个技术优势是,去除${\mathrm{{CO}}}_{2}$后的气流无需进一步增压即可直接通过管道输送,因为进料气体已增压以去除${\mathrm{{CO}}}_{2}$。膜分离和变压吸附的集成可进一步增强优势。如果捕集工业级以上的${\mathrm{{CO}}}_{2}$,吸收法更适用(表24、25和26)。
3.5.2 Economic Analysis
3.5.2经济分析
Before a Linz-Donawitz gas enters a cabinet, chemical absorption is cost-effective to capture ${\mathrm{{CO}}}_{2}$ of industrial grade above and storage grade. For the project of million tonnes/year scale (large scale), because of the intermittency of feed gas, the investment cost of such a large-scale project will be greater than that of post-combustion capture project with the same concentration in a coal-fired power plant. The operating cost of a project is only slightly higher than that of the post-combustion capture project in coal-fired power plant, because the costs mostly depend on energy consumption of absorption and desorption processes, which are less affected by the intermittency of feed LDG stream. Removing ${\mathrm{{CO}}}_{2}$ from a Linz-Donawitz gas can not only increase the calorific value of the gas, but also increase the efficiency of gas storage cabinets and reduce the corrosive effect of the gas on the subsequent device and equipment. In addition, the capture process can also contribute partially to cool the gas, thus save the capital and operating costs of cooling equipment.
在林茨-多纳维茨气体进入气柜之前,化学吸收法对于捕集高于工业级和储存级的${\mathrm{{CO}}}_{2}$具有成本效益。对于百万吨/年规模(大型)的项目,由于原料气的间歇性,如此大规模项目的投资成本将高于相同浓度的燃煤电厂燃烧后捕集项目。一个项目的运营成本仅略高于燃煤电厂燃烧后捕集项目,因为成本大多取决于吸收和解吸过程的能耗,受原料林茨-多纳维茨气流间歇性的影响较小。从林茨-多纳维茨气体中去除${\mathrm{{CO}}}_{2}$不仅可以提高气体的热值,还可以提高气柜的效率,并降低气体对后续装置和设备的腐蚀作用。此外,捕集过程还可以部分地冷却气体,从而节省冷却设备的资本和运营成本。
Regarding the ${\mathrm{{CO}}}_{2}$ from LDG stream after a gas cabinet, a chemical absorption method is also cost effective. The investment cost is further reduced significantly while the operating cost also reduces as the feed gas has a stable volume. However, the feed gas before cabinet has a high corrosivity to the cabinet, and the utilization efficiency of the cabinet is also poor. Currently, the investment cost of PSA and membrane separation methods that are applicable to storage grades are far higher than that of chemical absorption method, however, after 2025, the investment cost could decrease significantly. When considering the energy consumption saved in the subsequent compressing process that ensure the gas transported through a pipeline under high pressure, the operating cost may further decrease. Considering this cost saving, by 2025, the overall cost of the technology that integrates membrane separation with PSA is probably close to the cost of chemical absorption method (Tables 27 and 28).
对于气柜之后来自林茨-多纳维茨气流中的${\mathrm{{CO}}}_{2}$而言,化学吸收法同样具有成本效益。投资成本进一步显著降低,同时运营成本也随着原料气流量稳定而降低。然而,气柜之前的原料气对气柜具有高腐蚀性,且气柜的利用效率也较差。目前,适用于储存级的变压吸附和膜分离方法的投资成本远高于化学吸收法,不过,到2025年后,投资成本可能会显著下降。当考虑到在后续压缩过程中节省的能源消耗(确保气体在高压下通过管道输送)时,运营成本可能会进一步降低。考虑到这种成本节约,到2025年,将膜分离与变压吸附相结合的技术的总成本可能接近化学吸收法的成本(表27和表28)。
Table 24 Technical performance of technologies for Linz-Donawitz gas before cabinet
表24气柜之前林茨-多纳维茨气体技术的技术性能
| Technological options | Technical applicability | Main reasons | Disadvantages |
| Chemical absorption | Good | Capable of producing high concentration ${\mathrm{{CO}}}_{2}$ , mature technology | Involves chemical process, complex system and negative effect on environment |
| Pressured swing adsorption | Bad | Compressor is difficult to operate under an intermittent condition | High pretreatment requirement, large land use and unit size, complex system |
| Membrane separation | Bad | Compressor is difficult to operate under an intermittent condition | Poor system reliability, lack of technology demonstration |
| Cryogenic distillation | Bad | Compressor is difficult to pressurize the intermittent gas | N/A |
| Membrane—absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology |
Table 25 Technical performance of technologies for industry grade ${\mathrm{{CO}}}_{2}$ from Linz-Donawitz gas after cabinet
表25气柜之后林茨-多纳维茨气体中工业级${\mathrm{{CO}}}_{2}$技术的技术性能
| Product requirement | Technology options | Applicability | Advantage | Disadvantages |
| Internal use | Chemical absorption | Good | Capable of producing high concentration ${\mathrm{{CO}}}_{2}$ , mature technology | Involves chemical process, complex system and negative effect on environment |
| Pressured swing adsorption | Average | Can produce high concentration of ${\mathrm{{CO}}}_{2}$ and can be modularly developed | High pretreatment requirement, large land use and unit size, complex system | |
| Membrane separation | Bad | N/A | Poor system reliability, lack of technology demonstration; difficulty to produce high concentration ${\mathrm{{CO}}}_{2}$ | |
| Cryogenic distillation | Bad | N/A | Product of is in liquid state. not suitable for internal use | |
| Membrane—absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology | |
| Membrane—adsorption integration | Good | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size | Involves two processes of membrane and PSA and their integration; system is complex | |
| Membrane—cryogenic integration | Bad | N/A | Product of is in liquid state, not suitable for internal use |
(continued)
(续)
Table 25 (continued)
表25(续)
| Product requirement | Technology options | Applicability | Advantage | Disadvantages |
| External use | Chemical absorption | Good | Capable of producing high concentration ${\mathrm{{CO}}}_{2}$ , mature technology | Involves a chemical process, the system is complex, negative effect on environment |
| Pressure swing adsorption | Average | Can produce high concentration of ${\mathrm{{CO}}}_{2}$ and can be modularly developed | High pretreatment requirement, large land use and unit size, complex system | |
| Membrane separation | Bad | N/A | Poor system reliability, difficult to obtain high purity ${\mathrm{{CO}}}_{2}$ products alone | |
| Cryogenic distillation | Bad | N/A | ${\mathrm{{CO}}}_{2}$ concentration is too low | |
| Membrane—absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology | |
| Membrane—adsorption integration | Good | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size | Involves two processes of membrane and PSA and their integration; system is complex | |
| Membrane—cryogenic integration | Good | Product of is in liquid state, suitable for external use by small scale | Not suitable for pipeline transportation in super-critical phase |
Table 26 Technical performance of technologies for storage grade ${\mathrm{{CO}}}_{2}$ from Linz-Donawitz Gas after cabinet
表26气柜之后林茨-多纳维茨气体中储存级${\mathrm{{CO}}}_{2}$技术的技术性能
| Product requirement | Technology options | Applicability | Advantage | Disadvantages |
| Internal use | Chemical absorption | Good | Capable of producing high concentration ${\mathrm{{CO}}}_{2}$ , mature technology | Involves chemical process, complex system and negative effect on environment |
| Pressure swing adsorption | Average | Can produce high concentration of ${\mathrm{{CO}}}_{2}$ and can be modularly developed, LDG after ${\mathrm{{CO}}}_{2}$ removal can enter pipeline without addition pressure | High pretreatment requirement, large land use and unit size, complex system | |
| Membrane separation | Average | Can be modularly developed. LDG after ${\mathrm{{CO}}}_{2}$ removal can enter pipeline without addition pressure | Poor system reliability, lack of technology demonstration | |
| Cryogenic distillation | Bad | N/A | Product of is in liquid state. not suitable for internal use | |
| Membrane-absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology |
(continued)
(续)
Table 26 (continued)
表26(续)
| Product requirement | Technology options | Applicability | Advantage | Disadvantages |
| Membrane—adsorption integration | Good | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size; enhanced system stability. LDG after ${\mathrm{{CO}}}_{2}$ removal can enter pipeline without addition pressure | Involves two processes of membrane and PSA and their integration; system is complex | |
| Membrane—cryogenic integration | Bad | N/A | Product of is in liquid state. not suitable for internal use | |
| External use of storage grade | Chemical absorption | Good | Capable of producing high concentration ${\mathrm{{CO}}}_{2}$ , mature technology | Involves chemical process, complex system and negative effect on environment |
| Pressure swing adsorption | Average | Can produce high concentration of ${\mathrm{{CO}}}_{2}$ and can be modularly developed. LDG after ${\mathrm{{CO}}}_{2}$ removal can enter pipeline without addition pressure | High pretreatment requirement, large land use and unit size, complex system | |
| Membrane separation | Average | Can be modularly developed; LDG after ${\mathrm{{CO}}}_{2}$ removal can enter pipeline without addition pressure | Poor system reliability, lack of technology demonstration | |
| Cryogenic distillation | Bad | N/A | ${\mathrm{{CO}}}_{2}$ concentration is too low |
(continued)
(续)
Table 26 (continued)
表26(续)
| Product requirement | Technology options | Applicability | Advantage | Disadvantages |
| Membrane—absorption integration | Average | Can guarantee high concentration of ${\mathrm{{CO}}}_{2}$ ; can reduce land use | Involves integration of membrane and chemical absorption; complex system, and negative impacts on environment; immature technology | |
| Membrane-adsorption integration | Good | Can produce high concentration ${\mathrm{{CO}}}_{2}$ ; reduced land use and facility size; enhanced system stability; LDG after ${\mathrm{{CO}}}_{2}$ removal can enter pipeline without addition pressure | Involves two processes of membrane and PSA and their integration; system is complex | |
| Membrane—cryogenic integration | Good | Product of is in liquid state, suitable for external use by small scale; LDG after ${\mathrm{{CO}}}_{2}$ removal can enter pipeline without addition pressure | Not suitable for pipeline transportation in super-critical phase |
Table 27 Economic performance of technologies for industrial grade ${\mathrm{{CO}}}_{2}$ from Linz-Donawitz gas after cabinet (at capture rate of 90%)
表27气柜之后林茨-多纳维茨气体中工业级${\mathrm{{CO}}}_{2}$技术的经济性能(捕集率90%)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/tonne) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/tonne) |
| Large scale ( 0.1 mtpa) | Chemical absorption | 110-130 | 33-36 | 100-120 | 31-34 |
| adsorption | 160-180 | 35-37 | 140-160 | 32-34 | |
| Membrane absorption | 130-150 | 33-36 | 120-140 | 31-34 | |
| Membrane separation—pressure swing adsorption | 160-180 | 36-38 | 140-160 | 32-34 | |
| Small scale (0.1 mtpa) | Chemical absorption | 15-17 | 33-36 | 14-16 | 31-34 |
| Pressure swing adsorption | 18-20 | 35-37 | 16-18 | i | |
| Membrane absorption | 16-18 | 33-36 | 15-17 | 31-34 | |
| Membrane separation—pressure swing adsorption | 18-20 | 36-38 | 16-18 | 33-34 |
3.5.3 Techno-Economic Analysis of ${\mathrm{{CO}}}_{2}$ Capture for Flue Gas from Coke Oven and Power Generation Unit
3.5.3 焦炉和发电单元烟气中${\mathrm{{CO}}}_{2}$捕集的技术经济分析
The coke oven flue gas in a steel/iron plant is sourced from combustion for heating a coke oven. It is the combustion product of fossil fuel in a coke oven and discharged through a coke oven chimney. The flue gas sourced from power generation unit mainly comes from combustion of fuel, such as BFG, COG, coal, natural gas. The sources and the compositions of flue gases from coke oven and power generation unit are similar, with the ${\mathrm{{CO}}}_{2}$ concentration being between 10 and 15%. Therefore, a technology that is applicable to one is roughly applicable to the other.
钢铁厂的焦炉烟气来自焦炉加热燃烧,是焦炉内化石燃料的燃烧产物,通过焦炉烟囱排放。发电单元的烟气主要来自燃料燃烧,如高炉煤气、焦炉煤气、煤炭、天然气。焦炉和发电单元的烟气来源和成分相似,${\mathrm{{CO}}}_{2}$浓度在10%至15%之间。因此,适用于一种的技术大致也适用于另一种。
For capturing storage grade ${\mathrm{{CO}}}_{2}$ from a post-combustion flue gas stream with low concentration ${\mathrm{{CO}}}_{2}$ , the chemical absorption method is the most suitable among current available capture technologies. So far, there have already been large-scale post-combustion capture demonstration projects in operation in Canada and US, respectively. The technologies and experiences leant from those two projects can be referred to capture of flue gas from a coke oven and a power generation unit in a steel/iron plant. Although the PSA method and membrane separation method are also suitable for carbon capture of storage grade, however, it is still in a technological demonstration stage for flue gas from power-generation processes. Even by 2025, it is estimated that it is difficult for large-scale commercial application mainly because the ${\mathrm{{CO}}}_{2}$ concentration in the flue gas is very low. By 2025, membrane-absorption integration method may become gradually technical mature.
对于从低浓度${\mathrm{{CO}}}_{2}$的燃烧后烟道气流中捕集储存级${\mathrm{{CO}}}_{2}$,化学吸收法是目前可用捕集技术中最合适的。到目前为止,加拿大和美国分别已有大规模燃烧后捕集示范项目在运行。从这两个项目中汲取的技术和经验可用于钢铁厂焦炉和发电单元的烟气捕集。虽然变压吸附法和膜分离法也适用于储存级碳捕集,但对于发电过程的烟气仍处于技术示范阶段。即使到2025年,估计也难以大规模商业应用,主要是因为烟气中的${\mathrm{{CO}}}_{2}$浓度很低。到2025年,膜吸收一体化法可能会逐渐技术成熟。
Table 28 Economic performance of capture ${\mathrm{{CO}}}_{2}$ of storage grade after Linz-Donawitz Gas after cabinet (90% capture rate)
表28 林茨-多纳维茨气体经气柜后储存级${\mathrm{{CO}}}_{2}$捕集的经济性能(捕集率90%)
| Scale | Technology options | Investment cost (million \$) | Operating cost (\$/tonne) | Investment cost by 2025 (million \$) | Operating cost by 2025 (\$/tonne) |
| Large scale ( 0.1 mtpa) | Chemical absorption | 110-130 | 33-36 | 100-120 | 31-34 |
| Adsorption | 150-170 | 34-36 | 130-150 | 31-33 | |
| Membrane absorption | 110-130 | 33-36 | 100-120 | 31-34 | |
| Membrane separation | 150-170 | 35-37 | 130-150 | 32-34 | |
| Membrane separation—pressure swing adsorption | 150-170 | 35-37 | 130-150 | 31-33 | |
| Small scale ( 0.1 mtpa) | Chemical absorption | 15-17 | 33-36 | 14-16 | 31-34 |
| pressure swing adsorption | 17-19 | 34-36 | 15-17 | 31-33 | |
| Membrane absorption | 15-17 | 33-36 | 14-16 | 31-34 | |
| Membrane separation | 17-19 | 35-37 | 15-17 | 32-34 | |
| Membrane separation—pressure swing adsorption | 17-19 | 35-37 | 15-17 | 32-34 |
As for economic performance, whatever investment cost or operating cost, chemical absorption method is mostly dominant over other methods, such as PSA method and membrane separation method. By year 2025, membrane-absorption method that integrates chemical absorption with membrane separation would further reduce its investment cost and operating cost. It is likely that its economic is getting better than an absorption method. Membrane separation method and PSA method as well as their integration are unlikely to be economically superior to the chemical absorption method by 2025.
在经济性能方面,无论是投资成本还是运营成本,化学吸收法大多优于其他方法,如变压吸附法和膜分离法。到2025年,将化学吸收与膜分离相结合的膜吸收法将进一步降低其投资成本和运营成本。其经济性可能会优于吸收法。到2025年,膜分离法和变压吸附法及其一体化在经济上不太可能优于化学吸收法。
3.6 Discussions
3.6 讨论
In a typical production process of steel/iron in China, main ${\mathrm{{CO}}}_{2}$ emission sources include: lime kiln flue gas, hot blast furnace gas (HBFG), blast furnace gas (BFG), Linz-Donawitz gas (LDG), and flue gas from coke oven and power generation unit. ${\mathrm{{CO}}}_{2}$ concentration as well as temperature, pressure and impurity content of these emission sources are different; therefore, technical applicability and economic performance of capture technologies are also different when applied to different emission sources. Generally, chemical absorption method is suitable for low concentration gas and PSA, membrane separation and cryogenic distillation methods are suitable for high concentration gas, while membrane separation, PSA and cryogenic methods and their integration are also suitable for gas stream with pressure over a mbient environment level, such as blast furnace gas before TRT.
在中国典型的钢铁生产过程中,主要的${\mathrm{{CO}}}_{2}$排放源包括:石灰窑烟气、热风炉煤气(HBFG)、高炉煤气(BFG)、氧气顶吹转炉煤气(LDG)以及焦炉和发电单元的烟气。这些排放源的${\mathrm{{CO}}}_{2}$浓度以及温度、压力和杂质含量各不相同;因此,捕集技术应用于不同排放源时,其技术适用性和经济性能也不同。一般来说,化学吸收法适用于低浓度气体,变压吸附(PSA)、膜分离和低温蒸馏法适用于高浓度气体,而膜分离、PSA和低温法及其组合也适用于压力高于环境水平的气流,如TRT前的高炉煤气。
The different demands on captured ${\mathrm{{CO}}}_{2}$ product also affect technical applicability and economic performance of capture technologies. In general, chemical absorption method is more suitable for obtaining ${\mathrm{{CO}}}_{2}$ of industrial level above than other methods. Membrane separation and PSA methods and their integration are also suitable for storage grade ${\mathrm{{CO}}}_{2}$ . capture; while cryogenic distillation method is not suitable for large-scale capture of low ${\mathrm{{CO}}}_{2}$ concentration gas in steel/iron plant, but it is applicable when integrated with membrane separation or PSA method for capture small-scale ${\mathrm{{CO}}}_{2}$ product with liquefaction requirement.
对捕集的${\mathrm{{CO}}}_{2}$产品的不同需求也会影响捕集技术的技术适用性和经济性能。一般来说,化学吸收法比其他方法更适合获得工业级以上的${\mathrm{{CO}}}_{2}$。膜分离和PSA法及其组合也适用于储存级${\mathrm{{CO}}}_{2}$捕集;而低温蒸馏法不适合大规模捕集钢铁厂中低${\mathrm{{CO}}}_{2}$浓度气体,但与膜分离或PSA法组合用于捕集有液化要求的小规模${\mathrm{{CO}}}_{2}$产品时适用。
The technical applicability and economic performance of capture technologies are also affected by by-product opportunity associated with the removal of ${\mathrm{{CO}}}_{2}$ . For instance, the value of blast furnace gas can be raised by ${\mathrm{{CO}}}_{2}$ removal; flue gas of hot blast furnace and lime kiln can produce a by-product of nitrogen; corrosivity of Linz-Donawitz gas can be lessened after ${\mathrm{{CO}}}_{2}$ removal.
捕集技术的技术适用性和经济性能还受到与${\mathrm{{CO}}}_{2}$去除相关的副产品机会的影响。例如,去除${\mathrm{{CO}}}_{2}$可提高高炉煤气的价值;热风炉和石灰窑的烟气可产生氮气副产品;去除${\mathrm{{CO}}}_{2}$后氧气顶吹转炉煤气的腐蚀性可降低。
The technical applicability and economic performance of capture technologies are also depended on capture rate. Chemical absorption method is less influenced by capture rate than that membrane separation and PSA methods. Under a low ${\mathrm{{CO}}}_{2}$ concentration condition, membrane separation and pressure swing adsorption technologies are difficult to achieve a capture with rate of ${90}\%$ . Even if it can be achieved through their integration, investment and operation costs would be increased significantly. It is good for membrane separation and PSA methods and their integration to improve their technical applicability and economic performance by acceptance of a capture rate as low as ${85}\%$ . The optimal capture rate should be identified through a comprehensive analysis of capture cost and benefit in a system framework.
捕集技术的技术适用性和经济性能还取决于捕集率。化学吸收法受捕集率的影响小于膜分离和PSA法。在低${\mathrm{{CO}}}_{2}$浓度条件下,膜分离和变压吸附技术难以实现${90}\%$的捕集率。即使通过它们的组合能够实现,但投资和运营成本也会显著增加。膜分离和PSA法及其组合通过接受低至${85}\%$的捕集率来提高其技术适用性和经济性能是有益的。应在系统框架内通过对捕集成本和效益的综合分析来确定最佳捕集率。
For China’s steel/iron industry, take technical applicability and economic performance of various technologies into consideration comprehensively, it is recommended that capture on blast furnace gas, hot blast furnace gas and flue gas from lime kiln be prioritized due to the following main reasons: (1) high concentration of ${\mathrm{{CO}}}_{2}$ in those gas stream; (2) calorific value of BFG can be significantly improved by removal of ${\mathrm{{CO}}}_{2}$ ; (3) nitrogen gas, which is highly demanded by iron/steel industry, can be obtained as a co-benefit to the capture. Though the ${\mathrm{{CO}}}_{2}$ concentration of lime kiln flue gas is lower than hot blast furnace gas, by-product nitrogen benefit is higher than that gas.
对于中国的钢铁行业,综合考虑各种技术的技术适用性和经济性能,建议优先对高炉煤气、热风炉煤气和石灰窑烟气进行捕集,主要原因如下:(1)这些气流中${\mathrm{{CO}}}_{2}$浓度高;(2)去除${\mathrm{{CO}}}_{2}$可显著提高BFG的热值;(3)作为捕集的协同效益,可获得钢铁行业高度需求的氮气。虽然石灰窑烟气的${\mathrm{{CO}}}_{2}$浓度低于热风炉煤气,但其副产品氮气效益高于该气体。
In fact, if taking all major carbon emission sources into account in a whole, carbon capture for iron/steel industry could be another different case, in view of interactions among carbon capture from various sources, For example, high temperature feature of hot blast furnace gas and Linz-Donawitz gas can be used for absorbent regeneration by chemical absorption method; as the result of ${\mathrm{{CO}}}_{2}$ capture, calorific value increasing of blast furnace gas can reduce the amount of feed gas for hot blast furnace heating, coke oven heating and power generation, thus could increase the ${\mathrm{{CO}}}_{2}$ concentration in their flue gases. It is then beneficial to improve the economic performance of further capture from those gases. In short, the technical applicability and economic performance of carbon capture technologies for a steel/iron industry could be affected by multiple factors and their interactions under different conditions, it is necessary to carry out future research with a real-world business case to assess the technical applicability and economic performance of ${\mathrm{{CO}}}_{2}$ capture for China iron/steel industry based on individual gas source and overall gas system, respectively.
事实上,如果从整体上考虑所有主要碳排放源,鉴于来自各种来源的碳捕集之间的相互作用,钢铁行业的碳捕集可能是另一种不同的情况。例如,热风炉煤气和氧气顶吹转炉煤气的高温特性可用于化学吸收法的吸收剂再生;由于${\mathrm{{CO}}}_{2}$捕集,高炉煤气热值的增加可减少热风炉加热、焦炉加热和发电的原料气用量,从而可提高其烟气中的${\mathrm{{CO}}}_{2}$浓度。这有利于提高从这些气体中进一步捕集的经济性能。简而言之,钢铁行业碳捕集技术的技术适用性和经济性能可能受到多种因素及其在不同条件下相互作用的影响,有必要基于实际业务案例开展未来研究,分别根据单个气源和整体气体系统评估中国钢铁行业${\mathrm{{CO}}}_{2}$捕集的技术适用性和经济性能。
4 Section 4
4 第4节
4.1 Concluding Remarks
<### 4.1 结论
Carbon capture technology is not only a large-scale ${\mathrm{{CO}}}_{2}$ emission reduction technology with great potential for China’s iron/steel industry, but also the only technology that can deliver a large-scale direct emission reduction for steel/iron industry, while it can enable large-scale iron/steel companies to achieve a sustainable emission reduction with less effect on their own established energy balance system. This study provided a comprehensive techno-economic analysis of major ${\mathrm{{CO}}}_{2}$ capture technologies for China’s steel/iron industry. Based on a typical iron/steel making process of China’s iron/steel industry, main ${\mathrm{{CO}}}_{2}$ emission sources including blast furnace gas, Linz-Donawitz gas, hot blast furnace flue gas, lime kiln flue gas and flue gases of coke oven and power generation within an iron/steel plant were characterized. It was indicated that ${\mathrm{{CO}}}_{2}$ concentration of lime kiln flue gas, hot blast furnace gas, blast furnace gas and Linz-Donawitz gas is higher than that of post-combustion flue gas of normal coal-fired power generation industry; ${\mathrm{{CO}}}_{2}$ concentration of flue gases from coke oven and power generation unit within an iron/steel plant is lower than that a post-combustion flue gas from normal coal-fired power generation industry. In general, hot blast furnace flue gas has the highest ${\mathrm{{CO}}}_{2}$ concentration, blast furnace gas ranks the second, followed by Linz-Donawitz gas and lime kiln flue gas.
碳捕集技术不仅是一项对中国钢铁行业具有巨大减排潜力的大规模${\mathrm{{CO}}}_{2}$减排技术,也是唯一能够为钢铁行业实现大规模直接减排的技术,同时它能使大型钢铁企业在对自身既定能源平衡系统影响较小的情况下实现可持续减排。本研究对中国钢铁行业主要的${\mathrm{{CO}}}_{2}$捕集技术进行了全面的技术经济分析。基于中国钢铁行业典型的钢铁制造流程,对包括高炉煤气、转炉煤气、热风炉烟气、石灰窑烟气以及钢铁厂内焦炉和发电产生的烟气等主要${\mathrm{{CO}}}_{2}$排放源进行了特征分析。结果表明,石灰窑烟气、热风炉煤气、高炉煤气和转炉煤气中的${\mathrm{{CO}}}_{2}$浓度高于常规燃煤发电行业的燃烧后烟气;钢铁厂内焦炉和发电单元产生的烟气中的${\mathrm{{CO}}}_{2}$浓度低于常规燃煤发电行业的燃烧后烟气。总体而言,热风炉烟气的${\mathrm{{CO}}}_{2}$浓度最高,高炉煤气次之,其次是转炉煤气和石灰窑烟气。
Various post-combustion capture methods, including chemical absorption, pressure swine adsorption (PSA), membrane separation, cryogenic distillation methods and their integrations, are identified and analyzed from the perspective of their technical applicability and economic performance based on features of individual gas sources. Overall, chemical absorption is the most mature technology and have been demonstrated by two large-scale to post-combustion capture projects. It is particularly applicable and cost-effective to emission source with low ${\mathrm{{CO}}}_{2}$ concentration. Regarding PSA, membrane separation and cryogenic distillation methods, they are more applicable and cost-effective to high concentration ${\mathrm{{CO}}}_{2}$ source and have excellent technical and economic performance on gas stream with high pressure.
根据各个气体源的特点,从技术适用性和经济性能的角度,对包括化学吸收、变压吸附(PSA)、膜分离、低温蒸馏方法及其集成在内的各种燃烧后捕集方法进行了识别和分析。总体而言,化学吸收是最成熟的技术,已有两个大规模燃烧后捕集项目进行了示范。它特别适用于低${\mathrm{{CO}}}_{2}$浓度的排放源,且具有成本效益。对于PSA、膜分离和低温蒸馏方法,它们更适用于高浓度${\mathrm{{CO}}}_{2}$源,并且在高压气流上具有优异的技术和经济性能。
It is recognized by this study, that many factors could affect technical and economic performances of carbon capture technologies. Different temperature, pressure, impurity content and ${\mathrm{{CO}}}_{2}$ concentration of each emission source in steel/iron production process would lead to different technical applicability and economic performance of capture technologies; different demands for ${\mathrm{{CO}}}_{2}$ product also affect technical applicability and economic performance of capture technologies; in addition, co-benefit or by-product associated with ${\mathrm{{CO}}}_{2}$ removal affect technical applicability and economic performance of capture technologies. Specifically, calorific value of blast furnace gas can be significantly improved by ${\mathrm{{CO}}}_{2}$ removal; hot blast furnace flue gas has the highest ${\mathrm{{CO}}}_{2}$ concentration and high concentration nitrogen, lead to the lowest capture cost and an opportunity to produce by-product nitrogen with membrane technology, PSA or membrane-PSA integration technologies; Though the ${\mathrm{{CO}}}_{2}$ concentration of lime kiln flue gas is lower than hot blast furnace gas, by-product nitrogen benefit is higher than that gas.
本研究认识到,许多因素会影响碳捕集技术的技术和经济性能。钢铁生产过程中每个排放源的不同温度、压力、杂质含量和${\mathrm{{CO}}}_{2}$浓度会导致捕集技术的不同技术适用性和经济性能;对${\mathrm{{CO}}}_{2}$产品的不同需求也会影响捕集技术的技术适用性和经济性能;此外,与${\mathrm{{CO}}}_{2}$去除相关的协同效益或副产品会影响捕集技术的技术适用性和经济性能。具体而言,通过去除${\mathrm{{CO}}}_{2}$可显著提高高炉煤气的热值;热风炉烟气的${\mathrm{{CO}}}_{2}$浓度最高且氮气浓度高,导致捕集成本最低,并且有机会通过膜技术、PSA或膜 - PSA集成技术生产副产品氮气;虽然石灰窑烟气的${\mathrm{{CO}}}_{2}$浓度低于热风炉煤气,但其副产品氮气效益高于该气体。
In view of interactions among carbon capture from various sources, the technical applicability and economic performance of carbon capture technologies for a steel/iron industry could be affected by multiple factors and their interactions under different conditions, it is necessary to carry out future research with a real-world business case to assess the technical applicability and economic performance of ${\mathrm{{CO}}}_{2}$ capture for China iron/steel industry based on individual gas source and overall gas system, respectively.
鉴于来自各种源的碳捕集之间的相互作用,钢铁行业碳捕集技术的技术适用性和经济性能可能会受到多种因素及其在不同条件下相互作用的影响,有必要基于实际业务案例开展未来研究,分别从单个气体源和整体气体系统评估中国钢铁行业${\mathrm{{CO}}}_{2}$捕集的技术适用性和经济性能。
4.2 A Caveat
4.2 一项提醒
Understandably, steel plants differ. This is especially true in China. As this and the previous chapter have discussed, many factors affect the technical and economic performance of CCUS, including but not limited to, temperature, pressure, content impurity, and ${\mathrm{{CO}}}_{2}$ concentration of each emission source. In turn, these varying factors would affect costs. Thus, for actual deployment of CCUS in connection with cost considerations, it goes without saying, it is necessary to conduct real-world cases to assess the technical applicability and economic performance of ${\mathrm{{CO}}}_{2}$ capture in light of local- and firm-specific engineering conditions.
可以理解的是,钢铁厂各有不同。在中国尤其如此。正如本章及上一章所讨论的,许多因素会影响碳捕集、利用与封存(CCUS)的技术和经济性能,包括但不限于温度、压力、杂质含量以及每个排放源的${\mathrm{{CO}}}_{2}$浓度。相应地,这些不同的因素会影响成本。因此,出于成本考虑,在实际部署CCUS时,不言而喻,有必要根据当地和企业特定的工程条件进行实际案例分析,以评估${\mathrm{{CO}}}_{2}$捕集的技术适用性和经济性能。
177
Acronym Full spelling
首字母缩略词 完整拼写
BF/BOF Blast furnace/basic oxygen furnace
BF/BOF 高炉/碱性氧气转炉
BFG Blast furnace gas
BFG 高炉煤气
CCUS Carbon capture, utilization and storage
CCUS 碳捕集、利用与封存
CFG Controlled flow graph
CFG 控制流图
EAF Electric arc furnace
EAF 电弧炉
HBFG Hot blast furnace gas
HBFG 热风炉煤气
LDG Linz-Donawitz gas
LDG 氧气顶吹转炉煤气
MEA Mono ethanol amine
MEA 单乙醇胺
PSA Pressure swing adsorption
PSA 变压吸附
TGRBF Top gas recycle of blast furnace
TGRBF 高炉炉顶煤气循环
TRT Top gas pressure recovery turbine
TRT 高炉炉顶煤气余压透平发电装置
VPSA Vacuum pressure swing adsorption
VPSA 真空变压吸附
References
参考文献
Birat, J. P. (2010). Carbon dioxide $\left( {\mathrm{{CO}}}_{2}\right)$ capture and storage technology in the iron and steel industry. Carbon dioxide $\left( {\mathrm{{CO}}}_{2}\right)$ capture, transport and industrial applications. Developments and innovation in carbon dioxide $\left( {\mathrm{{CO}}}_{2}\right)$ capture and storage technology (vol. 1). UK: Woodhead Publishing Ltd.
Cheng, H.-H., Shen, J.-F., & Tan, C.-S. (2010). CO2 capture from hot stove gas in steel making process. International Journal of Greenhouse Gas Control, 4, 525-531.
Cheng, H.-H., Shen, J.-F., & Tan, C.-S. (2010b). ${\mathrm{{CO}}}_{2}$ CRC. Fact sheets-Gas separation membranes. Australia Cooperative Research Centre for Greenhouse Gas Technologies $\left( {{\mathrm{{CO}}}_{2}\mathrm{{CRC}}}\right)$
${\mathrm{{CO}}}_{2}\mathrm{{CRC}}$ . Fact sheets-Gas separation membranes. Australia Cooperative Research Centre for Greenhouse Gas Technologies (CO2CRC).
Feron, P. H., & Jansen, A. E. (2002). CO2 separation with polyolefin membrane contactors and dedicated absorption liquids-performances and prospects. Separation and Purification Technology, 34(27), 231-242.
Fang, L. (2016). Automatic control of top combustion hot blast stove. Industrial Furnace, 38(4).
GCCST. (2016). The global status of CGS, 2016 (Summary Report). Global CCS Institute (GCCST).
Goto, K., Chowdhury, F. A., Kodama, S., et al. (2013). Development of a novel ${\mathrm{{CO}}}_{2}$ capture system with chemical absorption process for the integrated steel works. World Iron & Steel, 13(6).
Gielen, D. (2003). ${\mathrm{{CO}}}_{2}$ removal in the iron and steel industry. Energy Conversion and Managament, 44, 1027-1037.
IEA. (2010). Energy technology perspectives 2010—scenarios and strategies to 2050 (p. 650). Paris, France.
Jinlian, W. (2007). Study on new chemical absorbent and process that absorbs ${\mathrm{{CO}}}_{2}\left\lbrack \mathrm{D}\right\rbrack$ . Zhejiang University.
Juan, Z., Qichao, G., Yonghui, L., et al. (2017). A study on increasing the gas recovery rate of converter gas dry purification recovery system. Metallurgical Power, 3, 49-51.
Kuramochi, T., Ramírez, A., Turkenburg, W., & Faaij, A. (2011). Techno-economic assessment and comparison of ${\mathrm{{CO}}}_{2}$ capture technologies for industrial processes: Preliminary results for the iron and steel sector. Energy Procedia, 4, 1981198-1981208.
Kim, J. Y., Han, K., & Chun, H. D. (2009). CO2 absorption with low concentration ammonia liquor. Energy Procedia, 1, 757-762.
Lie, J. A., Vassbotn, T., Hägg, M.-B., Grainger, D., Kim, T.-J., & Mejdell, T. (2007). Optimization of a membrane process for ${\mathrm{{CO}}}_{2}$ capture in the steelmaking industry. International Journal of Greenhouse Gas Control, 1, 309-317.
Mingtan, W., Shenlin, X., & Zitong, X. (2016). Present state and latest development of ${\mathrm{{CO}}}_{2}$ capture technology. Contemporary Chemical Industry, 45(5), 1002-1005.
Ming, G., Limin, Z., Xiaoqiang, L., et al. (2016). Research status of ${\mathrm{{CO}}}_{2}$ capture and storage technology (CCS) in the coal-fired power plant. Gas Purification, 6, 23-26.
Peng, H. (2013). Study on adsorption of modified activated to ${\mathrm{{CO}}}_{2}$ from off-gas in power plant [D]. Hebei University of Science & Technology. POSCO. (2013). Carbon report-2013. South Korea.
Rui, R.,& Duan, W. (2006). Current situation of ${\mathrm{{CO}}}_{2}$ emission in iron and steel producing and its controlling methods. Science & Technology Review, 24(10), 53-56.
Rhee, C. H., Kim, J. Y., Han, K., Ahn, C. K., & Chun, H. D. (2011). Process analysis for ammonia based ${\mathrm{{CO}}}_{2}$ capture in ironmaking industry. Energy Procedia,4,1486-1493.
Shaodong, C. (2016). Research on production scheduling in iron and steel scrap remanufacturing under the background of carbon reduction [D]. Southeast University.
Tseitlin, M. A., Lazutkin, S. E., Styopin, G. M. (1994). A flow-chart for iron making on the basis of 100% usage of process oxygen and hot reducing gases injection. ISIJ International, 34, 570-573.
Tobiesen, F. A., Svendsen, H. F., & Mejdell, T. (2007). Modeling of blast furnace ${\mathrm{{CO}}}_{2}$ capture using amine absorbents. Industrial and Engineering Chemistry Research, 46, 7811-7819.
Wenmin, J. (2015). Process simulation and experimental study of the capture carbon dioxide by chemical absorption method [D]. Zhejiang University.
Weifeng, Z., & Jianhui, S. (2015). On the latest advancements in the membrane-based technologies for ${\mathrm{{CO}}}_{2}$ capture. Journal of Safety and Environment., ${15}\left( 3\right) ,{205} - {211}$ .
Xiaosen, L., & Tao, L. (2009). Present development situation of techniques separating carbon dioxide separation techniques inform flue gas separation. Modern Chemical Industry, 29(4), 25.
Xinfeng, S. (2008). Research and design on CO2recovery technology of limekiln tail gas [D]. Xi’an University of Architecture and Technology (in Chinese).
Xiaobing, L. (2014). Research progress on Carbon Dioxide capture and separation technology. Guangdong Chemical Industry, 41(5), 115-116.
Yoon, Y. N. S., Jung, S., & Kim, Y. (2011). K2CO3/hindered cyclic amine blend (SEFY-1) as a solvent for ${\mathrm{{CO}}}_{2}$ capture from various industries. Energy Procedia,4,267-272.
Yonggang, W., Tianhong, Y., Yujie, Z., et al. (2008). Comparison of dry cleaning and recovery technique for converter flue gas with wet one. Industrial Safety and Environmental Protection, 34(5), 10-12.
Yongjia, H., Shuli, W., Pengyu, Z., et al. (2009). Current status and advances in ${\mathrm{{CO}}}_{2}$ separation and capture technology. Natural Gas Industry, 29(12), 79-82.
Yuansheng, X., Guangquan, L., & Xianqing, Y. (2012). Research progress of carbon dioxide capture technology and mechanism. Chemical Intermediate, 10, 1-5.
Zhengping, S. (2009). Recovery and utilization of carbon dioxide in industrial waste gas. China High-Tech Enterprises, 13, 88-89.
Zhi, G., Xinmiao, Z., Chenlin, Z., et al. (2016). Research development of membrane materials for separation of ${\mathrm{{CO}}}_{2}$ from flue gas. Modern Chemical Industry, 6,42-45.
齐間等, 茂木康弘, 原岡 たかし. (2013). Development of PSA technology for the separation of carbon dioxide from blast furnace gas. JFE 技報, 32, 44.
铁诺咨询. 新日铁住金高性能 ${\mathrm{{CO}}}_{2}$ 回收装置(ESCAP®)的开发[EB/OL] (2014-10-17) [2015-08-20]. http://www.tncsteel.com/show.php?contentid=153907.
Part III
第三部分
Market
市场
Building Carbon Market in China: Take Stock and Look Ahead
条目编号“0”:# 中国碳市场建设:总结与展望
Jun Fu, Xing Chen, and Jintao Xu
傅军、陈星、徐锦涛
Addressing climate change and reducing ${\mathrm{{CO}}}_{2}$ emissions has become a consensus globally. Among major industrialized countries, policy makers have either deployed or started to contemplate about deploying market-based instruments for climate policy. In that context, the idea of “cap & trade” of the carbon market-alternatively known as emission-trading system (ETS) in Europe-has commanded much attention of late. Theoretically, between the two extreme poles of hierarchy and market, their hybrid in the form of ETS can reduce ${\mathrm{{CO}}}_{2}$ emission reductions at lower costs than direct administrative fiat such as mandated installation of emission-reduction technologies. Deployed singularly, the former is about quantities, whereas the latter is about prices. ${}^{1}$ But both are needed to fight against climate change if only because of the problem associated with free riding.
应对气候变化和减少${\mathrm{{CO}}}_{2}$排放已成为全球共识。在主要工业化国家中,政策制定者已部署或开始考虑部署基于市场的气候政策工具。在此背景下,碳市场的“总量控制与交易”理念——在欧洲也被称为排放交易体系(ETS)——近来备受关注。理论上,在层级制和市场这两个极端之间,以ETS形式存在的两者混合体能够以比直接行政指令(如强制安装减排技术)更低的成本实现${\mathrm{{CO}}}_{2}$减排。单独来看,前者关乎数量,而后者关乎价格。${}^{1}$ 但要应对气候变化,两者都不可或缺,这仅仅是因为存在搭便车问题。
In line with the above, in 2011, China designated 7 provinces/cities, i.e., Beijing, Shanghai, Tianjin, Chongqing, Guangdong, Hubei and Shenzhen as ETS pilots (Duan et al., 2014). It was part and parcel of the country’s strategy to decarbonize its economy, and this move was the first phase (2011-2017) of a 3- phased plan to build carbon market in China. The vision was that these regional ETS pilots, if successful, would serve as stepping stones for China to prepare for a nation-wide ETS in the second phase (2017-2020), and following the second phase, China would consolidate and scale up the national ETS in the third phase (after 2020). Indeed, it was expected that China’s ETS would eventually overtake EU-ETS to become the largest in the world, covering emission-trading of up to 6-9 billion tons of ${\mathrm{{CO}}}_{2} \cdot {}^{2}$ In China, whereas there is broad agreement among environmental economists about the advantages of market-based resolutions, there is much debate as to whether or not a unified national ETS is the best choice for the country in light of regional disparities in industrial structure across the country.
基于上述情况,2011年中国指定北京、上海、天津、重庆、广东、湖北和深圳7个省市作为ETS试点(段等人,2014年)。这是中国经济脱碳战略的重要组成部分,此举是中国建设碳市场三阶段计划的第一阶段(2011 - 2017年)。其愿景是,如果这些区域ETS试点取得成功,将成为中国在第二阶段(2017 - 2020年)为全国性ETS做准备的垫脚石,在第二阶段之后,中国将在第三阶段(2020年之后)巩固并扩大全国性ETS。事实上,预计中国的ETS最终将超越欧盟ETS,成为全球最大的ETS,涵盖高达60 - 90亿吨${\mathrm{{CO}}}_{2} \cdot {}^{2}$的排放交易。在中国,虽然环境经济学家们普遍认同基于市场的解决方案的优势,但鉴于全国各地产业结构的区域差异,对于统一的全国性ETS是否是中国的最佳选择存在诸多争议。
${}^{1}$ For more discussion on this, see e.g., Weitzman (1974). Mideksa and Weitzman (2019).
${}^{1}$ 关于此的更多讨论,例如可参见魏茨曼(1974年)、米德克萨和魏茨曼(2019年)。
The original version of this chapter was revised: Few words corrections on page 198 have been updated. The correction to this chapter can be found at https://doi.org/10.1007/978- 981-16-4310-1_8.
本章的原始版本已修订:第198页的少量文字更正已更新。本章的更正内容可在https://doi.org/10.1007/978 - 981 - 16 - 4310 - 1_8上找到。
J. Fu $\left( \infty \right) \cdot$ J. Xu
傅军$\left( \infty \right) \cdot$ 徐锦涛
National School of Development, Peking University, Beijing, China
中国北京北京大学国家发展研究院
X. Chen
陈星
School of International Relations and Public Affairs, Fudan University, Shanghai, China
中国上海复旦大学国际关系与公共事务学院
In any event, are these regional ETS pilots working, albeit still at an early and experimental stage? What lessons can we learn from these regional ETS for the benefits of designing and developing a national ETS in the years ahead?
无论如何,这些区域ETS试点是否有效,尽管仍处于早期试验阶段?未来几年,我们能从这些区域ETS中学到哪些经验,以利于设计和发展全国性ETS?
This chapter aims to investigate these questions. The chapter is organized into four Sections. Section 1 starts with a brief review of the theoretical basis and the current practice of ETS worldwide and then outlines the evolving policy framework for China’s ETS. Section 2 looks at the institutional designs and operational mechanics of these regional ETSs. In Section 3, adding rigor and going beyond a prima facie analysis, we deploy synthetic control method to evaluate the performance of China’s regional ETSs. Key takeaways and policy recommendations follow in Section 4.
本章旨在研究这些问题。本章分为四个部分。第1节首先简要回顾全球ETS的理论基础和当前实践,然后概述中国ETS不断演变的政策框架。第2节审视这些区域ETS的制度设计和运行机制。在第3节中,我们运用合成控制法进行严谨分析,超越表面分析,评估中国区域ETS的绩效。第4节给出关键要点和政策建议。
1 Section 1
1 第1节
1.1 “Cap & Trade”: Theory and Practice of ETS
1.1 “总量控制与交易制度”:碳排放交易体系的理论与实践
The theoretical basis of “cap & trade” of emission-trading system (ETS) can be traced back to the economic thinking of Nobel laureate Ronald Coase, which made it possible to frame the discourse on pollution control in terms of rights instead of taxes, as previously advocated by Arthur Pigou (Pigou, 1929). According to Coase’s theme, by identifying certain rights, such as the right to emit greenhouse gas (GHG) emissions, and enabling the rights to be transferable, private negotiations could lead to the optimal allocation of resources, as long as transaction costs are sufficiently low (Coase, 1960).
排放交易体系(ETS)“总量控制与交易”的理论基础可以追溯到诺贝尔奖获得者罗纳德·科斯的经济思想,这使得关于污染控制的讨论能够从权利而非税收的角度进行构建,就像之前亚瑟·庇古所主张的那样(庇古,1929年)。根据科斯的观点,通过确定某些权利,比如排放温室气体(GHG)的权利,并使这些权利能够转让,只要交易成本足够低,私人谈判就能实现资源的最优配置(科斯,1960年)。
${}^{2}$ This is an estimation with the following assumptions: (1) China controls yearly ${\mathrm{{CO}}}_{2}$ emissions under 10 billion tons in 2016-2020; (2) it peaks ${\mathrm{{CO}}}_{2}$ emissions at 15 billion tons by 2030, and (3) the coverage of China’s ETS will be at the same level of EU-ETS, i.e., 60%. Assuming that the turn-over rate is at 300%, the trading volume of China’s ETS could reach 18-27 billion tons. In monetary terms, the value could reach 1.8-2.7 trillion RBM, assuming the price then is RMB 100/tCO2. According to UNEP, China’s CO2 emissions were 9.839 billion tons in 2019, accounting for 27.2% of the world’s total.
${}^{2}$ 这是基于以下假设的一项估算:(1)中国在2016 - 2020年将年度${\mathrm{{CO}}}_{2}$排放量控制在100亿吨以下;(2)到2030年${\mathrm{{CO}}}_{2}$排放量峰值为150亿吨,且(3)中国碳排放交易体系(ETS)的覆盖范围将与欧盟碳排放交易体系相同,即60%。假设周转率为300%,中国碳排放交易体系的交易量可能达到180 - 270亿吨。按货币计算,假设届时价格为100元/吨二氧化碳,则价值可达1.8 - 2.7万亿元人民币。根据联合国环境规划署的数据,2019年中国的二氧化碳排放量为98.39亿吨,占全球总量的27.2%。
Essentially, the “cap & trade” scheme affects levels of greenhouse gases (GHG) emissions by way of establishing a market for emission permits allocated to emitters under a total amount of emissions allowed-hence the “cap”. The total amount of allowable emissions then is divided into some emission permits allocated to individual business entities under certain rules (Weitzman, 2012, 2017). Recognizing the marginal cost difference of different emitters, the scheme allows trading of emission permits to eventually arrive at an equilibrium price-hence the “trade”. The equilibrium price provides a signal of the scarcity of emission permits (Spence and Weitzman, 1978), which in turn can guide individual emitters to choose between different strategies, e.g., increasing GHG emissions or reducing GHG emissions by investing in new technologies.
从本质上讲,“总量控制与交易”计划通过为排放者建立一个排放许可市场来影响温室气体(GHG)排放水平,这些排放许可被分配到允许的排放总量之下——因此称为“总量控制”。然后,允许的排放总量被按照一定规则划分为一些排放许可,分配给各个商业实体(Weitzman,2012年,2017年)。该计划认识到不同排放者的边际成本差异,允许排放许可的交易,最终达成一个均衡价格——因此称为“交易”。均衡价格提供了排放许可稀缺性的信号(Spence和Weitzman,1978年),这反过来又可以引导各个排放者在不同策略之间做出选择,例如增加温室气体排放或通过投资新技术来减少温室气体排放。
The first large-scale practical implementation of emission trading was the US sulfur dioxide $\left( {\mathrm{{SO}}}_{2}\right)$ “cap & trade” program. The program started in 1995 intending to address the problem of acid rain in the northeastern United States by mandating significant reductions in total annual ${\mathrm{{SO}}}_{2}$ emissions from coal-fired power plants (Stavins, 2001). The success of the program resulted in the emission-trading scheme being adopted as a crucial element of the design of the Kyoto Protocol in 1997 (UNFCCC, 1998). Worldwide, the practice of “cap & trade” includes Chicago Climate Exchange (CCX), UK Emissions Trading Group (ETG), National Trust of Australia (NSW), and the EU GHG Emission Trading System (EU-ETS).
排放交易的首次大规模实际实施是美国的二氧化硫$\left( {\mathrm{{SO}}}_{2}\right)$“总量控制与交易”计划。该计划始于1995年,旨在通过强制大幅减少燃煤发电厂的年度${\mathrm{{SO}}}_{2}$总排放量来解决美国东北部的酸雨问题(斯塔文斯,2001年)。该计划的成功导致排放交易计划在1997年被采纳为《京都议定书》设计的关键要素(《联合国气候变化框架公约》,1998年)。在全球范围内,“总量控制与交易”的实践包括芝加哥气候交易所(CCX)、英国排放交易集团(ETG)、澳大利亚新南威尔士州国家信托(NSW)以及欧盟温室气体排放交易体系(EU-ETS)。
At present, the European Union (EU) is leading in terms of building GHG emission-trading systems. The EU-ETS started in 2005, and by 2015, it had covered 31 EU countries, accounting for 50% of EU’s total carbon emissions (European Commission, 2015). As envisioned, from 2015 to 2020, the EU-ETS has been undergoing three phases of construction. During the first phase (2005-2007), the EU-ETS covers industries such as power, petrochemical, steel, construction materials, and paper-making, and it sets a yearly ${\mathrm{{CO}}}_{2}$ emission cap at 2.299 billion tons. During the second phase (2008-2012), the EU-ETS expands its industry coverage to include aviation, and it sets a yearly ${\mathrm{{CO}}}_{2}$ emission cap at 2.081 billion tons. During the third phase (2013-2020), the EU-ETS further expands its industry coverage to include chemicals and electrolytic aluminum, and it sets a yearly ${\mathrm{{CO}}}_{2}$ emission cap at 1.846 billion tons.
目前,欧盟在建设温室气体排放交易体系方面处于领先地位。欧盟排放交易体系始于2005年,到2015年,已覆盖31个欧盟国家,占欧盟碳排放总量的50%(欧盟委员会,2015年)。按照设想,2015年至2020年期间,欧盟排放交易体系经历了三个建设阶段。在第一阶段(2005 - 2007年),欧盟排放交易体系覆盖电力、石化、钢铁、建材和造纸等行业,设定的年度${\mathrm{{CO}}}_{2}$排放上限为22.99亿吨。在第二阶段(2008 - 2012年),欧盟排放交易体系将行业覆盖范围扩大到航空业,设定的年度${\mathrm{{CO}}}_{2}$排放上限为20.81亿吨。在第三阶段(2013 - 2020年),欧盟排放交易体系进一步将行业覆盖范围扩大到化工和电解铝行业,设定的年度${\mathrm{{CO}}}_{2}$排放上限为18.46亿吨。
Another salient feature of the EU-ETS is that it would gradually increase emission permits from free allowance to auction. Specifically, while auction does not exceed 5% in the first phase, it will increase to 10% during the second phase, and again to ${30}\%$ during the third phase. The general idea was to increase the competitive force of the market overtime (European Commission, 2003).
欧盟排放交易体系的另一个显著特点是,它将逐步增加排放许可,从免费配额转向拍卖。具体而言,虽然在第一阶段拍卖的比例不超过5%,但在第二阶段将增至10%,在第三阶段将再次增至${30}\%$。总体思路是随着时间的推移增强市场的竞争力(欧盟委员会,2003年)。
1.2 Policy Framework for Regional ETS Pilots in China
1.2中国区域碳排放交易体系试点的政策框架
Under the UN Framework Convention for Climate Change (UNFCCC), in 2009, China had pledged to reduce carbon intensity per unit of GDP by 40-45% in 2020 from the 2005 level. Subsequently, China incorporated the concept of “carbon intensity” into its 12th Five Year Plan (FYP, 2011-2015) for the first time, and the country decided to “gradually [emphasis added] establish a carbon emission trading market” to control GHG emissions. The wording with respect to ETS in the FYP indicated that China’s approach would be a phased and gradual one. In other words, “testing it out and then scaling it up” was the way to go. In retrospect, China took its international pledge seriously, and the gradual approach for the construction of ETS was no surprise, as it followed the same logic of the overall reform and opening-up program of the whole country during the past 40 or so years.
在《联合国气候变化框架公约》(UNFCCC)下,2009年中国承诺到2020年将单位GDP碳强度在2005年的基础上降低40%-45%。随后,中国首次将“碳强度”概念纳入其“十二五”规划(2011-2015年),并决定“逐步[重点添加]建立碳排放交易市场”以控制温室气体排放。“十二五”规划中关于碳排放交易体系的措辞表明中国将采取分阶段、渐进的方式。换句话说,“先试点再推广”是可行之道。回首往事,中国认真履行了其国际承诺,碳排放交易体系建设采取渐进方式并不奇怪,因为这遵循了过去40多年来全国整体改革开放计划的相同逻辑。
In October 2011, the National Development and Reform Commission of China (NDRC) issued the “Notice on Conducting Carbon Trading Pilots"to seven provinces/cities in China-Beijing, Shanghai, Tianjin, Chongqing, Guangdong, Hubei and Shenzhen. In effect, this NDRC notice was an instruction for the seven provinces/cities to prepare for the institutional groundwork for the launch of ETS pilots in 2013-2014. The seven regional ETS pilots covered about 18% of China’s population, and 30% of the country’s GDP
2011年10月,中国国家发展和改革委员会(NDRC)向中国的七个省/市——北京、上海、天津、重庆、广东、湖北和深圳发布了《关于开展碳排放权交易试点工作的通知》。实际上,国家发展和改革委员会的这份通知是对这七个省/市的指示,要求它们为2013-2014年启动碳排放交易体系试点做好制度准备。七个区域碳排放交易体系试点覆盖了中国约18%的人口和30%的国内生产总值。
Table 1 documents the legislative or policy framework at the seven localities to clear ways for the launch of the seven regional ETS pilots. As these regional ETS pilots were rolled out in 2013, it was expected that based on their experience, China would build a nationwide ETS to accelerate the process to decarbonize its economy. Indeed, according to the Joint China-US Presidential Statement in 2015, China promised to launch the national carbon market by the end of 2017.
表1记录了七个地方的立法或政策框架,为七个区域碳排放交易体系试点的启动扫清道路。由于这些区域碳排放交易体系试点于2013年推出,预计基于它们的经验,中国将建立全国性的碳排放交易体系以加速其经济脱碳进程。事实上,根据2015年中美联合声明,中国承诺在2017年底前启动全国碳市场。
Table 1 Policy framework of regional ETS pilots in China
表1中国区域碳排放交易体系试点的政策框架
| Localities | Key documents |
| Beijing | Resolution of Beijing Municipality to Carry out Carbon Trade Pilot and to Control Carbon Emissions (Standing Committee, Beijing Municipal People's Congress) |
| Shanghai | Shanghai Carbon Emissions Management Provisional Guidelines (Shanghai Municipal People's Government, November 18, 2013) |
| Guangdong | Guangdong Carbon Emissions Management Provisional Guidelines (Guangdong People's Government, January 15, 2014) |
| Shenzhen | Regulation of Shenzhen Special Economic Zone on Carbon Emissions Management (Shenzhen Municipal People's Congress, December 30, 2012) |
| Tianjin | Interim Measures of Tianjin Carbon Emission Trading (General Office of Tianjin Municipal People's Government) |
| Hubei | Hubei Interim Measures on Carbon Emissions Trade Management (Hubei Provincial Government, April 23, 2014) |
| Chongqing | Chongqing Carbon Emissions Trade Management Interim Measures (Chongqing Municipal People's Government, March 27, 2014) |
Source Websites of local DRC of Beijing, Shanghai, Tianjin, Chongqing, Guangdong, Hubei and Shenzhen
北京、上海、天津、重庆、广东、湖北和深圳地方发改委的来源网站
2 Section 2
2 第2节
2.1 Institutional Designs of ETS Pilots
2.1 碳排放权交易试点的制度设计
Good institutional designs were critical for the success of the seven regional ETS pilots in China, and eventually, for the success of the national ETS, which China planned to launch by the end of 2017. As discussed in the previous section, China embarked on building carbon markets more or less from scratch, as a long-term strategic move to develop a low-carbon economy in view of the country’s pledge in 2009 to the international community to reduce carbon intensity of GDP by 40- 45% by 2020 from the 2005 level. After a couple of years of initial preparations starting in 2011, China started seven regional ETS pilots in 2013.
良好的制度设计对于中国七个地区碳排放权交易试点的成功至关重要,最终对于中国计划在2017年底启动的全国碳排放权交易体系的成功也至关重要.如前所述.鉴于中国在2009年向国际社会承诺到2020年将国内生产总值的碳强度在2005年的基础上降低40% ~ 45%,中国几乎从零开始建设碳市场,这是发展低碳经济的一项长期战略举措。经过从2011年开始的几年初步准备,中国于2013年启动了七个地区碳排放权交易试点。
These regional ETS pilots were intended for the country to learn from experience before moving on to build a nationwide ETS. Given regional disparities in industrial structure, the advantage of such a strategy-i.e., regional pilots rather than one-swoop-go–is that local governments had the flexibility to design, operate, and adjust their ETS in light of local conditions. In Chinese aphorism, it is “crossing the river by touching the stones underneath”, so to speak, and there was a lot of “learning by doing” and “learning by watching” going on in the initial years. Indeed, during the initial phase, the regional ETS pilots had all learnt to expand industry coverage, improve permit allocations, and develop derivative products. And as a reflection of their demonstration effects, other provinces (e.g., Jiangsu, Xinjiang, and Zhejiang) increasingly showed interest in having their own ETSs. Fujian province, for instance, launched its own ETS in late 2016.
这些地区碳排放权交易试点旨在让国家在推进建设全国碳排放权交易体系之前积累经验。鉴于产业结构的地区差异,这种策略(即地区试点而非一蹴而就)的优势在于地方政府能够根据当地情况灵活设计、运营和调整其碳排放权交易体系。可以说,这就是中国俗语中的“摸着石头过河”,在最初几年里有大量的“边做边学”和“边看边学”。事实上,在初始阶段,地区碳排放权交易试点都学会了扩大行业覆盖范围、改进配额分配并开发衍生产品。作为其示范效应的体现,其他省份(如江苏、新疆和浙江)对建立自己的碳排放权交易体系的兴趣日益浓厚。例如,福建省于2016年底启动了自己的碳排放权交易体系。
A brief observation shows that China’s regional ETS pilots exhibit the following institutional features:
简要观察表明,中国的地区碳排放权交易试点呈现出以下制度特征:
These regional ETS pilots fall under the local Development and Reform Commission’s (DRC) jurisdiction, and the Local Finance Bureaus.
这些地区碳排放权交易试点由地方发展和改革委员会(发改委)以及地方财政局管辖。
All regional ETS pilots generally distribute permits in a fashion of grandfather-ing (free distribution), except Guangdong, Shenzhen, and Hubei where permits are auctioned. ${}^{3}$
2. 除广东、深圳和湖北通过拍卖方式分配配额外,所有地区碳排放权交易试点通常都以免费分配(祖父式)的方式分配配额。${}^{3}$
The government regularly intervenes in these pilot markets for data collection, allocation of permits and/or auction, and pricing if need be.
政府会定期干预这些试点市场,进行数据收集、配额分配和/或拍卖,必要时还会进行定价。
The regional ETS pilots cover mostly energy-intensive industries such as electricity, steel, cement, chemicals. ETSs in Beijing, Shanghai, and Tianjin, however, also cover building and service sectors. In all, some 20 industries are covered. ${}^{4}$
地区碳排放权交易试点主要覆盖电力、钢铁、水泥、化工等能源密集型行业。然而,北京、上海和天津的碳排放权交易体系也涵盖建筑和服务业。总共涵盖约20个行业。${}^{4}$
All ETS pilots only cover ${\mathrm{{CO}}}_{2}$ emissions, except Chongqing, which covers 6 GHGs $\left( {{\mathrm{{CO}}}_{2},{\mathrm{{CH}}}_{4},{\mathrm{\;N}}_{2}\mathrm{O},\text{ HFCs, HFCs, }{\mathrm{{SF}}}_{6}}\right)$ . Most ETS pilots cover both direct and indirect emissions, although indirect emission definition differs. Some account for purchased electricity only; others cover purchased electricity and heat. Hubei only trades direct emissions.
除重庆涵盖6种温室气体$\left( {{\mathrm{{CO}}}_{2},{\mathrm{{CH}}}_{4},{\mathrm{\;N}}_{2}\mathrm{O},\text{ HFCs, HFCs, }{\mathrm{{SF}}}_{6}}\right)$外,所有碳排放权交易试点仅涵盖${\mathrm{{CO}}}_{2}$排放。大多数碳排放权交易试点涵盖直接和间接排放,尽管间接排放的定义有所不同。一些仅计入购买的电力;其他的则涵盖购买的电力和热力。湖北仅交易直接排放。
All regional ETS pilots recognize China Certified Emission Reduction (CCER) by NDRC, although some set ceilings for their use, ranging from 50 to 70%.
所有地区碳排放权交易试点都认可国家发改委的中国核证自愿减排量(CCER),尽管有些试点对其使用设定了50% ~ 70%的上限。
All regional ETS pilots set up two thresholds for market access: transaction threshold (for emission control firms) or reporting threshold (for reporting firms). The latter, albeit not included in trading yet, must report emissions to the government to consider future inclusion (Fig. 1).
所有地区碳排放权交易试点都设定了两个市场准入门槛:交易门槛(针对排放控制企业)或报告门槛(针对报告企业)。后者虽然尚未纳入交易,但必须向政府报告排放情况,以便考虑未来纳入(图1)。
3 Shanghai ETS represented another alternative, i.e., grandfathering + auction. See compliance/sanction below.
3 上海碳排放权交易体系代表了另一种方式,即免费分配+拍卖。见下文的合规/制裁。
${}^{4}$ By 2020, close to 3,000 fossil-heavy industrial firms covered.
${}^{4}$ 到2020年,覆盖近3000家化石能源密集型工业企业。
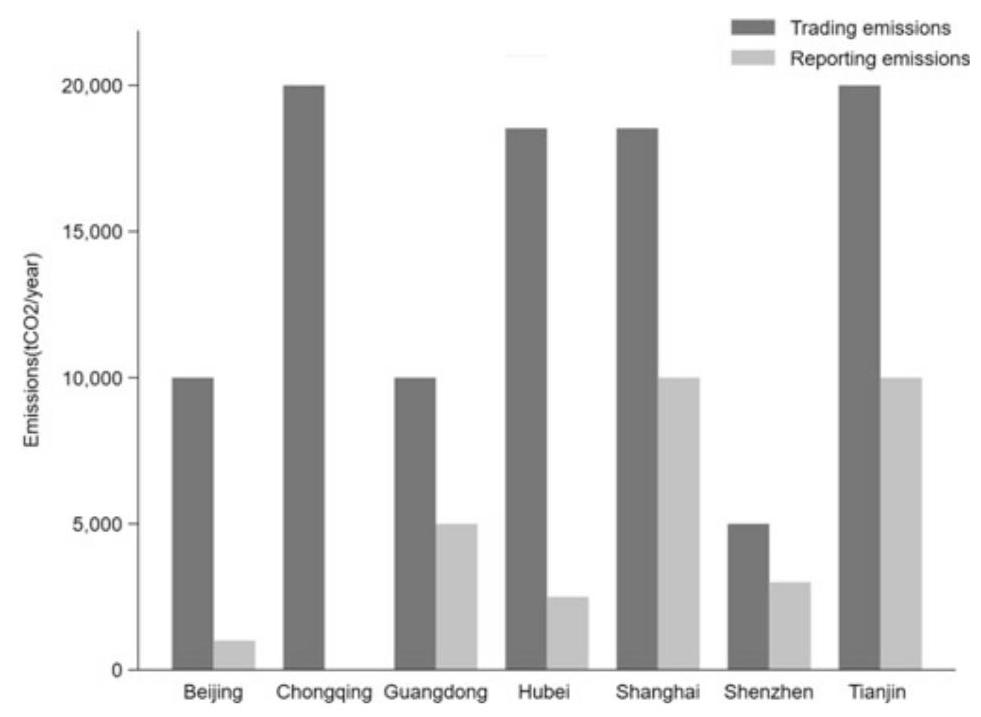
Fig. 1 ETS Pilots in China: Transaction Threshold and Reporting Threshold. Note 1. Data. Source Websites of local DRC in 7 regional ETS pilots; 2. Reporting emissions of Chongqing is unavailable
图1 中国碳排放权交易试点:交易门槛和报告门槛。注:1. 数据来源:7个地区碳排放权交易试点的地方发改委网站;2. 重庆的报告排放数据不可用
2.2 ETS Pilots in Operation
2.2 正在运行的碳排放交易体系试点
Institutional designs aside, let us take a look at the actual performance of China’s regional ETS pilots. For the purposes of this study, we look at the five domains as key performance indicators (KPI) of the ETS pilots: (1) emission permit allocation, (2) MRV (monitoring, reporting and verification), (3) compliance/sanctions, (4) CCER (China certified emission reduction), (5) behavioral change, and (6) pricing. Table 2 lists the six categories of KPIs. Below, we schematically elaborate a bit more on each of the six categories of KPIs.
抛开制度设计不谈,让我们看看中国区域碳排放交易体系试点的实际表现。在本研究中,我们将五个领域视为碳排放交易体系试点的关键绩效指标(KPI):(1)排放许可分配,(2)监测、报告与核查(MRV),(3)合规/制裁,(4)中国核证自愿减排量(CCER),(5)行为变化,以及(6)定价。表2列出了这六类关键绩效指标。下面,我们将对这六类关键绩效指标逐一进行简要阐述。
Table 2 China’s regional ETS pilots in operation
表2 中国正在运行的区域碳排放交易体系试点
| Tasks Allocation of allowances | Indicator | Control agency | Data source | Status check |
| Time & allocation of permits to firms | Total amount of permits allocated | Local DRC | Local DRC website | Permits allocated in 2013 and 2014, with 730 million tons and 1285 million tons respectively |
| Information collection | Indicator | Control agency | Data source | Status |
| Collection of emission reports including verification | Total number of emission reports collected | Local DRC | Local DRC Website; interview with ETS staff | Collected emission and verification reports from 1736 firms in 5 ETS pilots |
| Random checks on verification reports | Total number of random checks | Local DRC | Local DRC Website; interviews with ETS staff | No data on random checks on verification reports |
| Information disclosure on trading volume and price | Publication patterns of trading volume and price | Local DRC or carbon trading exchange | Local DRC Website; trading exchange; K-line website | All carbon trading exchanges released all information on trading volume and price except Guangdong, whose data is only on most recent trading |
(continued)
(续)
Table 2 (continued)
表2(续)
| Tasks Allocation of allowances | Indicator | Control agency | Data source | Status check |
| Information disclosure on compliance | Information compliance rate | Local DRC | Local DRC Website | All ETS pilots published information on compliance within 3 months after a compliance cycle |
| Compliance and sanction | Indicator | Control agency | Data source | Status check |
| Rules and sanctions on non-compliance | Total number of sanctions imposed | Local DRC | Local DRC Website; news reports | 14 firms were sanctioned for non-compliance. Nature of sanction unknown |
| Other policy instruments | Indicator | Control agency | Data Source | Status check |
| China Certified Emission Reduction (CCER) | Total CCER issued | NDRC | China CCER Exchange Info-Platform | A total of 13.72 million tons of CCER were issued by Jan. 14, 2015 |
| Behavioral change | ||||
| Firms behavior | Indicator | Control agency | Data source | Status check |
(continued)
(续)
Table 2 (continued)
表2(续)
| Tasks Allocation of allowances | Indicator | Control agency | Data source | Status check |
| Behavioral changes or adaptions | Amount of emission permit traded | Local Carbon Trading Exchanges | Local Carbon Trading Exchanges | A total of 114.58 million tons of permits was traded by June 30, 2017 |
| Adaption to compliance | Compliance rate | Local DRC | Local DRC Website | Compliance rates in 2013: Beijing 97%, Shanghai 100%, Guangdong 98%, Shenzhen 99%; Tianjin 96% |
a415 firms in Beijing, 191 in Shanghai, 184 in Guangdong, 114 in Tianjin, and 635 firms and 197 buildings in Shenzhen Source Websites of local DRC in 7 regional ETS pilots
北京有415家企业,上海有191家,广东有184家,天津有114家,深圳有635家企业和197栋建筑 7个区域碳排放交易体系试点中地方发改委的源网站
1. Emission Permit Distribution
1. 排放许可分配
${\mathrm{{CO}}}_{2}$ emission permit allocation is a prerequisite for the carbon market to operate. Once the government sets the cap of emissions, it has to find a way to allocate allowances to emitters in a timely fashion (Pang and Duan 2016). The way that the regional ETS pilots in China operate in this area was that the government of each pilot launched a dedicated e-platform or website for registration and allocation of emission permits. By government, it referred to local DRC in each case. Allocation of emission permits had two ways: grandfathering and auction. In the case of Guangdong, Shenzhen, and Hubei, it was auction; and in the case of Beijing, Chongqing, Shanghai, and Tianjin, it was free distribution. In all, free distribution accounted for over 90%. There was room for the websites of these regional ETS pilots to improve. A quick browse in a comparative perspective indicated that these e-platforms were not equally user-friendly. For instance, the website of Beijing did not disclose data on how permits were allocated in 2013 and 2014.
${\mathrm{{CO}}}_{2}$ 排放许可分配是碳市场运行的前提条件。一旦政府设定了排放上限,就必须找到一种方法及时向排放者分配配额(庞和段,2016年)。中国区域碳排放权交易试点在这方面的运作方式是,每个试点地区的政府都推出了一个专门的电子平台或网站,用于排放许可的登记和分配。这里的政府,在每种情况下指的是当地的发展改革委。排放许可分配有两种方式:祖父式分配和拍卖。在广东、深圳和湖北,采用的是拍卖方式;在北京、重庆、上海和天津,采用的是免费分配方式。总体而言,免费分配占比超过90%。这些区域碳排放权交易试点的网站还有改进的空间。从比较的角度快速浏览一下就会发现,这些电子平台的用户友好程度并不相同。例如,北京的网站没有披露2013年和2014年排放许可如何分配的数据。
2.MRV System
2.监测、报告与核查体系
Transparency and accuracy of information is essential for market transactions. In the case of ETS, a robust MRV (monitoring, reporting and verification) system for corporate ESG (environment, social responsibility and corporate governance) is vital to minimize the risks of “greenwashing”. Here, it is the role of the government to collect information at the firm level with respect to emissions, trading, compliance, etc. Currently, all ETS pilots in China would require emission control firms to submit emission reports verified by a third party designated by the government. These reports then would be subject to random checks by the government to increase accuracy and reliability. Again, a quick browse of the websites of these regional ETS pilots showed that whereas information on trade volume and price was readily available, that of compliance was patchy, and that of verification was not available-a critical area that need further investigation.
信息的透明度和准确性对于市场交易至关重要。就碳排放交易体系而言,一个健全的企业环境、社会责任和公司治理(ESG)监测、报告与核查(MRV)体系对于将“漂绿”风险降至最低至关重要。在此,政府的职责是收集企业层面有关排放、交易、合规等方面的信息。目前,中国所有碳排放交易体系试点都要求排放控制企业提交由政府指定第三方核查的排放报告。然后,这些报告将接受政府的随机检查,以提高准确性和可靠性。同样,快速浏览这些区域碳排放交易体系试点的网站可以发现,虽然交易量和价格信息很容易获取,但合规信息参差不齐,而核查信息则无法获取——这是一个需要进一步调查的关键领域。
3. Compliance/Sanctions
3. 合规/制裁
A robust regulatory framework has to put in place the so-called “teeth” of enforcement so that it can encourage or rather compel firms to take emission limits seriously and participate in carbon trading actively. Here, the rules regarding compliance and sanctions across these regional ETS pilots were vague, although there were sporadic reports on sanctions. For instance, in late 2013, Beijing and Guangdong imposed sanctions on a total of 14 firms for their failure of timely compliance, although little information was available as to what kind of penalty was imposed. In Tianjin, there was report that 4 firms had failed to perform their
一个强有力的监管框架必须具备所谓的执法“牙齿”,以便能够鼓励甚至迫使企业认真对待排放限制并积极参与碳交易。在此,尽管有关于制裁的零星报道,但这些区域碳排放交易体系试点中有关合规和制裁的规则并不明确。例如,2013年末,北京和广东对总共14家未能及时合规的企业实施了制裁,不过关于施加了何种处罚的信息很少。在天津,有报道称4家企业未能及时履行其2013年的义务,但天津的暂行办法并未包含处罚条款、罚款或其他内容。在深圳,有报道称政府给予了宽限期以敦促合规。在合规和制裁方面,北京和广东似乎最为严格,而天津在规则执行方面最为宽松。
2013 obligations in a timely fashion, and yet Tianjin Interim Measures did not contain penalty clauses, fines or otherwise. In Shenzhen, there were reports that grace periods were granted by the government to urge for compliance. It seemed that in terms of compliance and sanctions, Beijing and Guangdong were the most stringent, whereas Tianjin was most lax in enforcement of rules.
及时履行2013年的义务,但天津的暂行办法未包含处罚条款、罚款或其他内容。在深圳,有报道称政府给予了宽限期以敦促合规。在合规和制裁方面,北京和广东似乎最为严格,而天津在规则执行方面最为宽松。
Shanghai ETS represented another alternative. Apparently, there was no case of non-compliance or sanctions in 2013. But the way that Shanghai ETS operated was that when the deadline (June 30) for compliance was approaching, the government auctioned off additional 580,000 tons of ${\mathrm{{CO}}}_{2}$ emissions permits that firms could buy for compliance. The result was high compliance rate.
上海碳排放交易体系代表了另一种情况。显然,2013年没有违规或制裁的案例。但上海碳排放交易体系的运作方式是,当合规截止日期(6月30日)临近时,政府拍卖了额外的58万吨${\mathrm{{CO}}}_{2}$排放许可,企业可以购买这些许可用于合规。结果是合规率很高。
4. CCER (China certified emission reduction)
4. 中国核证自愿减排量(CCER)
All seven regional ETS pilots recognized project-based CCER (China certified emission reduction) approved and issued by NDRC, and information for authenticity and verification of these credits was available at China CCER Exchange Platform. In 2016, in terms of project number, Hubei ETS had 122 projects, Beijing ETS had 16, Chongqing ETS had 15, Guangdong ETS had 47, Shanghai ETS had 18, Tianjin ETS had 6, and Shenzhen ETS had 5, with a total of 229. Prominent among these projects were wind, solar, hydraulic power, and methane gas. ${}^{5}$ While the set ceiling for the use of CCER credits varies across the seven regional ETS pilots, ranging from 1 to ${10}\% ,{}^{6}$ CCER credits could count as emission allowances for compliance.
所有七个区域碳排放交易体系试点均认可国家发展改革委批准签发的基于项目的中国核证自愿减排量(CCER),这些减排量的真实性和核查信息可在中国核证自愿减排量交易平台获取。2016年,从项目数量来看,湖北碳排放交易体系有122个项目,北京碳排放交易体系有16个,重庆碳排放交易体系有15个,广东碳排放交易体系有47个,上海碳排放交易体系有18个,天津碳排放交易体系有6个,深圳碳排放交易体系有5个,共计229个。这些项目中突出的有风能、太阳能、水力发电和沼气。${}^{5}$ 虽然七个区域碳排放交易体系试点对中国核证自愿减排量的使用上限规定各不相同,从1到${10}\% ,{}^{6}$不等,但中国核证自愿减排量可作为合规的排放配额。
5. Behavioral Change
5. 行为变化
Does ETS change firms’ behavior, and if yes, to what extent? Are there variations across the seven regional ETS pilots? For the purposes of this study, we look at three key indicators-trading volume, trading turnover, and active ratio-defined as the ratio between the number of days that have trading volume and the total trading days. Our statistical deadline is June 30, 2017 and the results are tabulated in Table 3.
碳排放交易体系是否改变了企业行为?如果是,改变程度如何?七个地区性碳排放交易体系试点之间是否存在差异?为了本研究的目的,我们考察三个关键指标——交易量、交易周转率和活跃率,活跃率定义为有交易量的天数与总交易天数之比。我们的统计截止日期是2017年6月30日,结果列于表3。
${}^{5}$ They accounted for over ${80}\%$ in terms of project number in 2020.
${}^{5}$ 2020年,它们在项目数量方面占比超过${80}\%$。
${}^{6}$ Specifically, offset limit of CCERs as a share of annual allowance was set at ${10}\%$ for Hubei, Shenzhen, Tianjin, 8% for Chongqing, 5% for Beijing, and 1% for Shanghai. Note also that credits from hydro projects are not allowed in most ETS pilots. In the case of Guangdong, the ceiling was set at 1.5 million offsets, and both CCERs and Pu Hui Certified Emission Reduction (PHCERs) were accepted, but at least 70% had to come from local projects in Guangdong province.
${}^{6}$ 具体而言,湖北、深圳、天津的核证自愿减排量(CCERs)抵消上限设定为年度配额的${10}\%$,重庆为8%,北京为5%,上海为1%。另请注意,大多数碳排放交易体系试点不允许水电项目产生的信用额。在广东,上限设定为150万个抵消额,CCERs和广东普惠制核证减排量(PHCERs)均被接受,但至少70%必须来自广东省内的本地项目。
Table 3 ETS Pilots: trading indicators
表3 碳排放交易体系试点:交易指标
| ETS Pilots | Starting date | Total trading days | Active ratio (%) | Average price(rmb) | Average trading volume(ton) | Average trading turnover(rmb) | Share of total (%) |
| Shenzhen | Jun-13 | 1885 | 89 | 38 | 14,349 | 546,882 | 12 |
| Beijing | Nov-13 | 1765 | 64 | 60 | 8169 | 488,521 | 6 |
| Shanghai | Dec-13 | 1750 | 62 | 31 | 10,183 | 315,377 | 8 |
| Guangdong | Dec-13 | 1750 | 86 | 24 | 43,495 | 1,023,164 | 32 |
| Tianjin | Dec-13 | 1744 | 38 | 18 | 5827 | 105,497 | 4 |
| Hubei | Apr-14 | 1674 | 96 | 23 | 47,771 | 1,101,884 | 34 |
| Chongqing | Jun-14 | 1623 | 35 | 17 | 5392 | 92,240 | 4 |
| Average | 1742 | 67 | 30 | 19,312 | 524,795 | - |
Note 1. Active rate means the ratio between number of days that have trading volume and total trading days; 2. The statistical deadline is set at Dec 31, 2020; 3. Total trading days excludes holidays; 3. Data source http://k.tanjiaoyi.com/..
注1. 活跃率指有交易量的天数与总交易天数之比;2. 统计截止日期设定为2020年12月31日;3. 总交易天数不包括节假日;3. 数据来源http://k.tanjiaoyi.com/..
The Table 3 shows that in terms of trading volume, Hubei was the highest and Tianjin was the lowest; in trading turnover, Hubei was the highest and Tianjin was the lowest; and in terms of active ratio, Hubei, again, was the highest and Tianjin was the lowest. Across the seven regional ETS pilots, the average active ratio was 66%. Above that ratio, there were Hubei (96%), Shenzhen (90%), Guang-dong (71%), and Beijing (69%), and below that ratio, there were Shanghai (63%), Tianjin (52%), and Chongqing (18%).
表3显示,在交易量方面,湖北最高,天津最低;在交易周转率方面,湖北最高,天津最低;在活跃率方面,湖北同样最高,天津最低。在七个地区性碳排放交易体系试点中,平均活跃率为66%。高于该比率的有湖北(96%)、深圳(90%)、广东(71%)和北京(69%),低于该比率的有上海(63%)、天津(52%)和重庆(18%)。
It seemed clear that, having operated for more than 3 years, the 3 ETS pilots, i.e., Hubei, Guangdong, and Shenzhen, were more active in trading than the other 4, i.e., Shanghai, Beijing, Chongqing, and Tianjin. Amongst the seven regional ETS pilots, Hubei ETS, in particular, was relatively successful, in terms of trading volume and turnover. By June 30, 2017, Hubei ETS sold 40.48 million tons of permits, with a turnover of RMB 797.82 million. But by international standards, even the best of China’s ETS pilots still had a long way to go. For instance, on a single day on January 21, 2015, the trading volume of California carbon market surged to 10 million tons, about of 2/3 of China’s total trading volume in all seven regional pilots (Fig. 2). ${}^{7}$ In the case of China, as Fig. 2 shows, the sudden and onetime spikes in trading volume around June 2015 indicate that many firms perhaps take emissions trading as political cooperation rather than investment opportunity. Carbon assets were not considered valuable.
显然,运行三年多后,湖北、广东和深圳这三个碳排放交易体系试点在交易方面比上海、北京、重庆和天津这四个试点更活跃。在七个地区性碳排放交易体系试点中,特别是湖北碳排放交易体系在交易量和周转率方面相对成功。截至2017年6月30日,湖北碳排放交易体系售出4048万吨配额,交易额为7.9782亿元人民币。但按照国际标准,即使是中国最好的碳排放交易体系试点仍有很长的路要走。例如,2015年1月21日,加利福尼亚碳市场的交易量单日飙升至1000万吨,约为中国所有七个地区性试点总交易量的2/3(图2)。${}^{7}$ 就中国而言,如图2所示,2015年6月左右交易量的突然一次性飙升表明,许多企业可能将排放交易视为政治合作而非投资机会。碳资产未被视为有价值的资产。
${}^{7}$ http://calcarbondash.org/.
${}^{7}$ http://calcarbondash.org/.
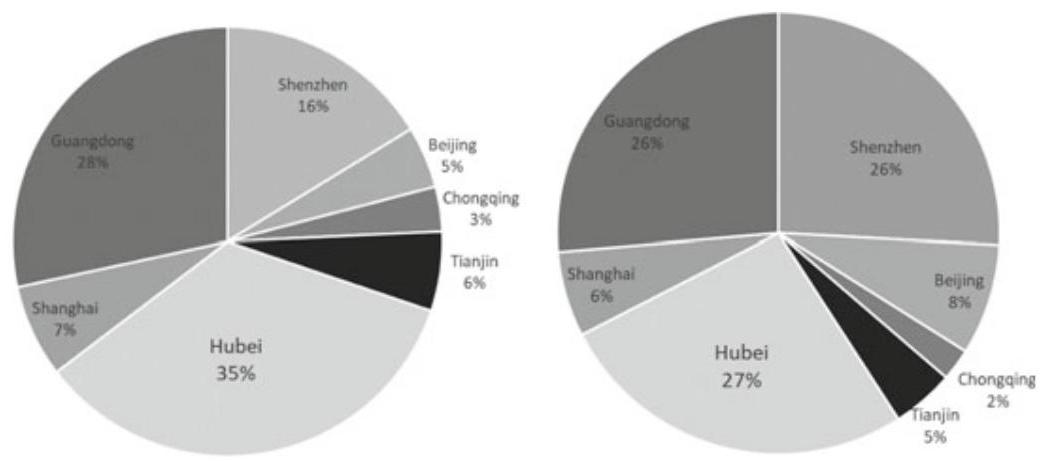
Fig. 2 Share of trading volume/trading turnover. Data source http://k.tanjiaoyi.com/
图2 交易量/交易周转率占比。数据来源http://k.tanjiaoyi.com/
6. Pricing
6. 定价
Price is central to market (also see Fig. 2), and yet, given the fact that the regional pilots of carbon market in China remained divided, it was expected that carbon prices would vary across different regions. Indeed, there was a great variation of carbon price among these ETS pilots with a minimum of RMB 28 and a maximum of RMB 143 per ton of ${\mathrm{{CO}}}_{2}$ emissions. By June 30,2017, the total trading volume of the seven ETS pilots reached 114.58 million tons. As Table 2 shows that amongst the seven regional ETS pilots, average price for ${\mathrm{{CO}}}_{2}$ emissions was the highest in Beijing, about RMB 50/ton, followed by Shenzhen, with RMB 47/ton. The price in Shanghai, Chongqing, Hubei, and Tianjin was close, about RMB 20-25/ton. As an average of all seven ETS pilots, it was about RMB 30/ton-a price perhaps too low (still trending downwards, see Fig. 2) to significantly motivate a firm’s strategic investment in shifting towards better technology or cleaner energy. To highlight the point here, the current cost of CCUS technology is estimated at US$ 600/ton. ${}^{8}$ Moreover, the price divergence across different regions was also indication of the great challenges lying ahead in setting up a unified carbon market in China.
价格是市场的核心要素(另见图2),然而,鉴于中国碳市场的区域试点仍处于分割状态,预计不同地区的碳价格会有所差异。事实上,这些碳排放权交易体系(ETS)试点之间的碳价格差异很大,每吨${\mathrm{{CO}}}_{2}$排放量的最低价格为28元人民币,最高价格为143元人民币。截至2017年6月30日,七个ETS试点的总交易量达到1.1458亿吨。如表2所示,在七个区域ETS试点中,北京的${\mathrm{{CO}}}_{2}$排放平均价格最高,约为50元/吨,其次是深圳,为47元/吨。上海、重庆、湖北和天津的价格相近,约为20 - 25元/吨。作为所有七个ETS试点的平均价格,约为30元/吨——这个价格可能过低(仍在下降趋势,见图2),不足以显著激励企业在转向更好技术或清洁能源方面进行战略投资。在此强调一点,目前碳捕获、利用与封存(CCUS)技术的成本估计为600美元/吨。${}^{8}$此外,不同地区的价格差异也表明中国建立统一碳市场面临巨大挑战。
${}^{8}$ For more discussions on carbon capture, utilization and storage, see Chapters 3 and 4 of this study.
${}^{8}$ 关于碳捕获、利用与封存的更多讨论,请参见本研究的第3章和第4章。
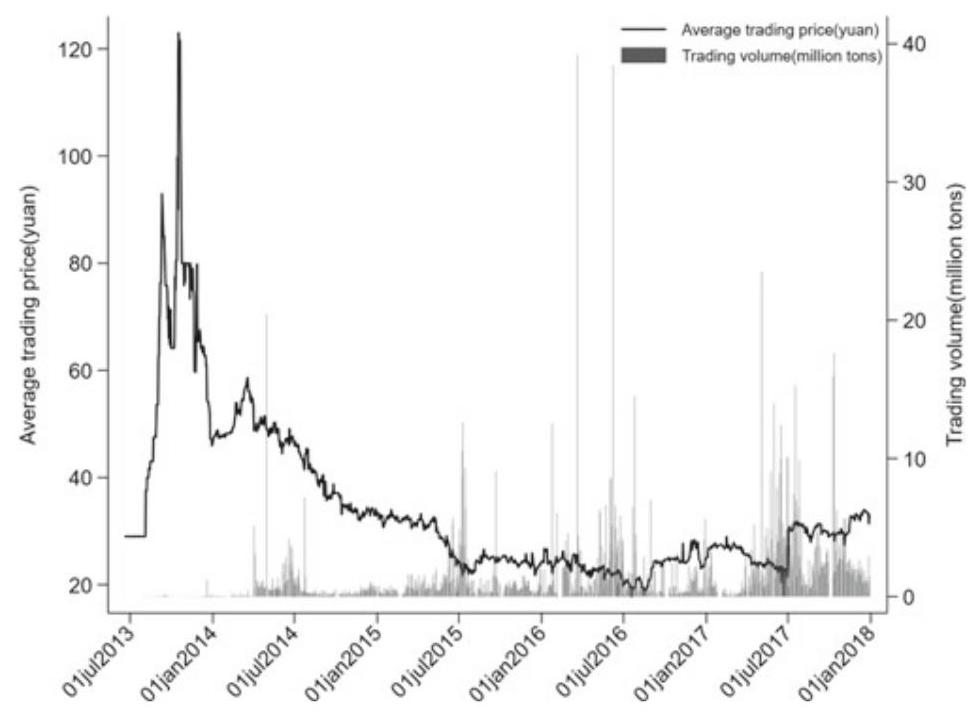
Fig. 3 Trends of emission permit trading in China. Data source http://k.tanjiaoyi.com/
图3 中国排放许可交易趋势。数据来源http://k.tanjiaoyi.com/
For international comparative perspectives, average carbon price in EU-ETS was about RMB 100/ton (or US$ 16/ton) before 2018 and poised to rise significantly; ${}^{9}$ globally, the price range was between US$ 1/ton and US$ 130/ton (Fig. 3).
从国际比较的角度来看,2018年之前欧盟排放交易体系(EU - ETS)的平均碳价格约为100元/吨(或16美元/吨),且有望大幅上涨;${}^{9}$ 在全球范围内,价格范围在1美元/吨至130美元/吨之间(图3)。
3 Section 3
3 第3节
3.1 Assessing ${\mathrm{{CO}}}_{2}$ Emission Reduction by ETS Pilots
3.1 评估碳排放交易体系试点对${\mathrm{{CO}}}_{2}$减排的成效
In the previous two sections, we have reviewed the theoretical basis of carbon market and looked at the institutional designs and operational mechanics of China’s regional ETS pilots. In this section, building upon that knowledge, our aim is to go beyond mere descriptive statistics to assess the actual performance of the ETS pilots in reducing ${\mathrm{{CO}}}_{2}$ emissions. To increase the rigor of our examination beyond a prima facie case, we will deploy the method of synthetic control in our statistical analyses, trying to pin down the impact, if any, of the regional ETS pilots on the reduction of ${\mathrm{{CO}}}_{2}$ emissions. Strictly speaking, doing scientific experiments means that one must isolate variables, and in so doing, tests must proceed under strictly (often lab-) controlled conditions. The same logic would apply to serious policy studies by a trained eye-he or she must be keenly aware that real world knowledge based on inductive inference can never be deterministic, and worse, “controlled conditions” in policy settings at the aggregate level are elusive at best if not totally absent.
在前两节中,我们回顾了碳市场的理论基础,并审视了中国区域碳排放交易体系试点的制度设计与运行机制。在本节中,基于这些知识,我们的目标是超越单纯的描述性统计,评估碳排放交易体系试点在减少${\mathrm{{CO}}}_{2}$排放方面的实际成效。为了使我们的检验比表面情况更严谨,我们将在统计分析中采用合成控制法,试图确定区域碳排放交易体系试点对${\mathrm{{CO}}}_{2}$减排的影响(若有)。严格来说,进行科学实验意味着必须隔离变量,这样做时,测试必须在严格(通常是实验室)控制的条件下进行。同样的逻辑也适用于训练有素的人进行的严肃政策研究——他或她必须敏锐地意识到,基于归纳推理的现实世界知识永远无法确定,更糟糕的是,在总体层面的政策环境中,“控制条件”充其量只是难以捉摸,甚至可能完全不存在。
${}^{9}$ It reached 25 Euro per ton in 2019.
${}^{9}$ 2019年时达到了每吨25欧元。
Mindful of these pitfalls, in the three subsections that follow, we will first introduce and then deploy the method of synthetic control. Second, we report investigation results based on that method. Third, we perform a placebo-like robustness test to check the confidence level of whatever impact we may find of the ETS pilots on the reduction of ${\mathrm{{CO}}}_{2}$ emissions.
考虑到这些陷阱失误,在接下来的三个子部分中,我们将首先介绍并运用合成控制法。其次,我们报告基于该方法的调查结果。第三,我们进行类似安慰剂的稳健性检验,以检验我们可能发现碳排放交易体系试点对${\mathrm{{CO}}}_{2}$减排产生的任何影响的置信水平。
3.2 Method of Synthetic Control
3.2 合成控制法
Frequently researchers are called upon to examine the effects of policy interventions, and in so doing they often resort to comparative case studies. But that job is easier said than done. For the challenge is that at the aggregate level how can the researcher seriously compare the results of an allegedly “affected” group vis- à-vis an allegedly “unaffected” group, when in fact there is no controlled group? Indeed, in our present case of ETS and ${\mathrm{{CO}}}_{2}$ emissions, it would be difficult to estimate ${\mathrm{{CO}}}_{2}$ reduction achievement of carbon trading in the absence of solid control groups.
研究人员经常需要考察政策干预的效果,在此过程中,他们常常诉诸比较案例研究。但说起来容易做起来难。问题在于,在总体层面上,当实际上不存在控制组时,研究人员如何能够认真比较所谓“受影响”组与所谓“未受影响”组的结果呢?的确,在我们当前关于碳排放交易体系和${\mathrm{{CO}}}_{2}$排放的案例中,如果没有可靠的控制组,就很难估计碳交易在${\mathrm{{CO}}}_{2}$减排方面的成效。
In this context, we need relevant statistical tools and the method of synthetic control is helpful in estimating effects of policy settings where a single group (or a firm or a state) is exposed to policy intervention. The method of synthetic control was first developed and used by Abadie et al. Studies, employing the synthetic method, include the assessment of the economic impact of conflict in Basque (Abadie and Gardeazabal, 2003), the impact of tobacco control program on tobacco sales in California, USA, (Abadie et al., 2010), the economic impact of the 1990 German reunification on West Germany (Abadie et al., 2015). There are also many studies on China. Deploying synthetic control method, Liu and Fan (2018) have examined the economic impact of property tax in Chongqing. Zhang et al. (2016) have tried to respond to the query—“Did Olympic Games improve air quality in Beijing?” by using synthetic control method.
在这种情况下,我们需要相关的统计工具,而合成控制法有助于估计单一组(或一家公司或一个州)受到政策干预时政策设置的效果。合成控制法最初由阿巴迪等人开发并使用。采用合成法的研究包括对巴斯克地区冲突的经济影响评估(阿巴迪和加德亚扎巴尔,2003年)、美国加利福尼亚州烟草控制计划对烟草销售的影响(阿巴迪等人,2010年)、1990年德国统一对西德的经济影响(阿巴迪等人,2015年)。也有许多针对中国的研究。刘和范(2018年)运用合成控制法考察了重庆房产税的经济影响。张等人(2016年)试图通过使用合成控制法来回应“奥运会是否改善了北京的空气质量?”这一疑问。
Drawing upon Abadie et al. (2010), for the purposes of our investigation of ETS, we build a model that has the rationale for synthetic control method. Assume that we have $M + 1$ regions, and region #1 is exposed to policy intervention (i.e., ETS in our case), then we have the remaining $M$ regions as control units. Let ${T}_{0}$ be the number of pre-intervention periods, with $1 < {T}_{0} < T$ . Assume ${Y}_{it}^{N}$ is the counterfactual outcome that would be observed for region i at time $t$ with the absence of policy intervention for unit ${\mathrm{s}}_{\mathrm{i}}$ , and time period ${\mathrm{s}}_{\mathrm{t}}$ . Let ${Y}_{it}^{I}$ be the outcome that would be observed for region i at time $\mathrm{t}$ with policy intervention in after ${T}_{0}$ . We also assume that the policy intervention has no effect on the outcome before the implementation period, so that for all $i$ in period $t \in \left\{ {1,2,\ldots ,{T}_{0}}\right\}$ , we would have that ${Y}_{it}^{N} = {Y}_{it}^{I}$ . Let ${\alpha }_{it} = {Y}_{it}^{I} - {Y}_{it}^{N}$ be the effect of the policy intervention for unit $i$ at time $t$ . Our aim here is to estimate:
借鉴阿巴迪等人(2010年)的研究,为了我们对碳排放交易体系的调查,我们构建一个具有合成控制法原理的模型。假设我们有$M + 1$个地区,其中地区1受到政策干预(即我们案例中的碳排放交易体系),那么我们将其余$M$个地区作为控制单元。设${T}_{0}$为干预前时期的数量,其中$1 < {T}_{0} < T$ 。假设${Y}_{it}^{N}$是在没有对单元${\mathrm{s}}_{\mathrm{i}}$进行政策干预且处于时期${\mathrm{s}}_{\mathrm{t}}$的情况下,地区i在时间$t$会观察到的反事实结果。设${Y}_{it}^{I}$是在经过${T}_{0}$次干预后地区i在时间$\mathrm{t}$会观察到的结果。我们还假设政策干预在实施期之前对结果没有影响,因此对于时期$t \in \left\{ {1,2,\ldots ,{T}_{0}}\right\}$中的所有$i$,我们有${Y}_{it}^{N} = {Y}_{it}^{I}$ 。设${\alpha }_{it} = {Y}_{it}^{I} - {Y}_{it}^{N}$是单元$i$在时间$t$的政策干预效果。我们在此的目标是估计:
$$ {\alpha }_{1t} = {Y}_{1t}^{I} - {Y}_{1t}^{N} $$where ${Y}_{it}^{I}$ is observed, so we only need to estimate ${Y}_{1t}^{N}$ . Let $\left( {\mathrm{M} \times 1}\right)$ be a vector of weights ${W}^{ * } = \left( {{w}_{2}^{ * },\cdots ,{w}_{j + 1}^{ * }}\right)$ such that ${W}_{m} \geq 0$ for $\mathrm{m} = 2,\ldots ,\mathrm{M} + 1$ and ${w}_{2} + \cdots + {w}_{M + 1} = 1$ . Each value of the vector ${W}^{ * }$ denotes a potential synthetic control, which corresponds to a particular weighted average of control regions. The value of the outcome variable for each synthetic control indexed by ${W}^{ * }$ is:
其中${Y}_{it}^{I}$是可观察到的,所以我们只需要估计${Y}_{1t}^{N}$ 。设$\left( {\mathrm{M} \times 1}\right)$是权重${W}^{ * } = \left( {{w}_{2}^{ * },\cdots ,{w}_{j + 1}^{ * }}\right)$的向量,使得对于$\mathrm{m} = 2,\ldots ,\mathrm{M} + 1$和${w}_{2} + \cdots + {w}_{M + 1} = 1$有${W}_{m} \geq 0$ 。向量${W}^{ * }$的每个值表示一个潜在的合成控制,它对应于控制地区的特定加权平均值。由${W}^{ * }$索引的每个合成控制的结果变量值为:
$$ \mathop{\sum }\limits_{{m = 2}}^{{M + 1}}{w}_{m}{Y}_{it} = {\partial }_{t} + {\theta }_{t}\mathop{\sum }\limits_{{m = 2}}^{{M + 1}}{w}_{m}{Z}_{m} + {\lambda }_{t}\mathop{\sum }\limits_{{m = 2}}^{{M + 1}}{w}_{m}{\mu }_{i} + \mathop{\sum }\limits_{{m = 2}}^{{M + 1}}{w}_{m}{\varepsilon }_{it} $$Abadie and his associates (2011) have proved that $\mathop{\sum }\limits_{{j = 2}}^{{J + 1}}{w}_{j}^{ * }{Y}_{jt}$ is an unbiased estimate of ${Y}_{it}^{N}$ , where ${T}_{0} < t \leq T$ . So ${\alpha }_{1t} = {Y}_{it} - \mathop{\sum }\limits_{{j = 2}}^{{J + 1}}{w}_{j}^{ * }{Y}_{jt}$ is the unbiased estimation of ${\alpha }_{1t}$ .
阿巴迪及其同事(2011年)证明,$\mathop{\sum }\limits_{{j = 2}}^{{J + 1}}{w}_{j}^{ * }{Y}_{jt}$是${Y}_{it}^{N}$的无偏估计量,其中${T}_{0} < t \leq T$。所以${\alpha }_{1t} = {Y}_{it} - \mathop{\sum }\limits_{{j = 2}}^{{J + 1}}{w}_{j}^{ * }{Y}_{jt}$是${\alpha }_{1t}$的无偏估计。
For the purposes of this investigation, the outcome variable of our interest is annual ${\mathrm{{CO}}}_{2}$ emissions. We calculated ${\mathrm{{CO}}}_{2}$ emissions based on energy consumption at provincial level by using energy consumption data in 1997-2017 period (Provincial Statistical Yearbook). Since China’s seven regional ETS pilots began operation in 2013, we mark 2013 as the year of policy intervention (i.e., ETS). This gives us 16 years of pre-policy intervention data. Based on the method proposed by CEADs, ${}^{10}$ we calculate annual ${\mathrm{{CO}}}_{2}$ emission level for all provinces in China.
在本调查中,我们感兴趣的结果变量是年度${\mathrm{{CO}}}_{2}$排放量。我们根据1997 - 2017年期间省级能源消耗数据(省级统计年鉴)计算${\mathrm{{CO}}}_{2}$排放量。由于中国七个区域碳排放交易体系试点于2013年开始运行,我们将2013年标记为政策干预年份(即碳排放交易体系)。这为我们提供了16年的政策干预前数据。基于CEADs提出的方法,${}^{10}$我们计算了中国所有省份的年度${\mathrm{{CO}}}_{2}$排放水平。
To see the “synthetic” part of the method as a benchmark devise, let us take Hubei as an example. We use the synthetic control techniques described above to construct a “synthetic Hubei”. This synthetic Hubei is a best weighted average with a set of value predictors of carbon emissions in Hubei before policy intervention (i.e., ETS) began. In this context, the “synthetic Hubei” is meant to indicate the level of carbon emissions that we would have observed in the absence of ETS. We thus drop from the donor pool all the provinces/cities that have adopted ETS during the sample period (i.e., Beijing, Guangdong (including Shenzhen), Shanghai, Tianjin, and Chongqing). However, since some key economic indicators of Tibet and Ningxia are not available during sample period, a total of 23 provinces/cities have remained in our donor pool (Table 5).
为了将该方法的“合成”部分视为一个基准设计,我们以湖北为例。我们使用上述合成控制技术构建一个“合成湖北”。这个合成湖北是在政策干预(即碳排放交易体系)开始前,对湖北碳排放的一组价值预测变量进行的最佳加权平均。在这种情况下,“合成湖北”旨在表明在没有碳排放交易体系的情况下我们可能观察到的碳排放水平。因此,我们从捐赠池中剔除了在样本期内采用碳排放交易体系的所有省份/城市(即北京、广东(包括深圳)、上海、天津和重庆)。然而,由于西藏和宁夏的一些关键经济指标在样本期内不可用,共有23个省份/城市留在了我们的捐赠池中(表5)。
Using the techniques described above, we construct a synthetic province/city one by one for Hubei, Guangdong (including Shenzhen), Tianjin, Shanghai, Beijing, Chongqing that mirrors the level of carbon emissions before ETS was put in place. Based on that, we estimate the emission reduction effect of policy intervention of ETS after 2013 as the difference in carbon emissions between real Hubei (with ETS) and synthetic Hubei (without ETS). We then perform a series of placebo tests to see whether or not the estimated effects of ETS are unusually large in light of the estimate distribution that we obtain by applying the same procedure to the provinces/cities in our donor pool. Finally, we repeat the same procedure for other ETS pilots-Guangdong (including Shenzhen), Beijing, Shanghai, Chongqing, and Tianjin.
使用上述技术,我们逐个为湖北、广东(包括深圳)、天津、上海、北京、重庆构建一个反映碳排放交易体系实施前碳排放水平的合成省份/城市。在此基础上,我们将2013年后碳排放交易体系政策干预的减排效果估计为实际湖北(有碳排放交易体系)与合成湖北(无碳排放交易体系)之间的碳排放差异。然后,我们进行一系列安慰剂检验,以根据我们对捐赠池中省份/城市应用相同程序获得的估计分布,判断碳排放交易体系的估计效果是否异常大。最后,我们对其他碳排放交易体系试点——广东(包括深圳)、北京、上海、重庆和天津重复相同的程序。
3.3 Test Results
<### 3.3测试结果
As explained above, by deploying the synthetic control method, we construct a synthetic Hubei as the combination of provinces/cities in our donor pool. This synthetic Hubei resembles Hubei in terms of predictor of ${\mathrm{{CO}}}_{2}$ emissions before policy intervention (i.e., ETS). Table 4 exhibits the test results, which have compared the features of real Hubei with synthetic Hubei before policy intervention. The same comparison includes the other regional ETS pilots. Table 5 shows the weights of all control provinces/cities for each ETS pilot.
如上所述,通过采用合成控制方法,我们构建了一个合成湖北,作为我们的捐赠池中省份/城市的组合。这个合成湖北在政策干预(即碳排放交易体系)之前的${\mathrm{{CO}}}_{2}$排放预测指标方面与湖北相似。表4展示了测试结果,该结果比较了政策干预前真实湖北与合成湖北的特征。同样的比较也包括其他区域碳排放交易体系试点。表5显示了每个碳排放交易体系试点的所有控制省份/城市的权重。
10 China Emission Accounts & Datasets: https://www.ceads.net/.CEADs is made of a group of experts from the UK, the US, and China who have worked on China’s emission accounting
10中国排放账户与数据集:https://www.ceads.net/。CEADs由来自英国、美国和中国的一组专家组成,他们致力于中国的排放核算工作
Table 4 Economic features of real pilots versuss synthetic pilots
表4真实试点与合成试点的经济特征
| HB | HB_syn | BJ | BJ_syn | SH | SH_syn | TJ | TJ | CQ | CQ_syn | GD | GD_syn | |
| GDP | 7862.2 | 7887.3 | 7172.3 | 5186.2 | 9186.0 | 9141.2 | 4385.7 | 3414.2 | 4029.2 | 4048.1 | 23,489.4 | 17,520.6 |
| GDP_per | 13,703.1 | 13,746.8 | 42,862.0 | 17,454.5 | 47,094.2 | 21,964.8 | 37,534.3 | 14,944.7 | 13,678.4 | 13,286.3 | 24,596.6 | 24,505.5 |
| Population | 5742.4 | 5759.0 | 1544.7 | 2108.6 | 1848.4 | 3309.1 | 1086.8 | 1979.9 | 2850.1 | 2860.6 | 9033.3 | 6532.9 |
| Sec_rate | 42.6 | 42.8 | 29.9 | 33.5 | 46.5 | 50.4 | 52.8 | 48.9 | 44.2 | 44.3 | 48.4 | 49.0 |
note 1 sec rate refers to second industry as share of total GDP; 2. Data source China statistical yearbook
注1. 第二产业占GDP比重;2. 数据来源:《中国统计年鉴》
Table 5 Synthetic weight for synthetic pilots
表5合成试点的合成权重
| Region | Hubei_weight | Beijing_weight | Shanghai_weight | Tianjin_weight | Chongqing_weight | Guangdong_weight |
| Anhui | 0.036 | 0 | 0 | 0 | 0.027 | 0 |
| Fujian | 0.025 | 0 | 0 | 0 | 0.03 | 0 |
| Gansu | 0.019 | 0 | 0 | 0 | 0.047 | 0 |
| Guangxi | 0.033 | 0 | 0 | 0 | 0.031 | 0 |
| Guizhou | 0.025 | 0 | 0 | 0 | 0.042 | 0 |
| Hainan | 0.096 | 0.682 | 0 | 0 | 0.08 | 0.144 |
| Hebei | 0.026 | 0 | 0 | 0 | 0.02 | 0 |
| Heilongjiang | 0.018 | 0 | 0 | 0 | 0.034 | 0 |
| Henan | 0.045 | 0 | 0 | 0 | 0.015 | 0 |
| Hunan | 0.059 | 0 | 0 | 0 | 0.023 | 0 |
| InnerMongolia | 0.024 | 0 | 0.018 | 0 | 0.036 | 0 |
| Jiangsu | 0.057 | 0 | 0 | 0 | 0.012 | 0.856 |
| Jiangxi | 0.025 | 0 | 0 | 0 | 0.034 | 0 |
| Jilin | 0.017 | 0 | 0 | 0.566 | 0.04 | 0 |
| Liaoning | 0.024 | 0 | 0 | 0 | 0.026 | 0 |
| Qinghai | 0.013 | 0 | 0.352 | 0.381 | 0.301 | 0 |
| Shaanxi | 0.02 | 0 | 0 | 0 | 0.036 | 0 |
| Shandong | 0.027 | 0 | 0 | 0 | 0.01 | 0 |
| Shanxi | 0.017 | 0 | 0 | 0 | 0.039 | 0 |
(continued)
(续)
Table 5 (continued)
表5(续)
| Region | Hubei_weight | Beijing_weight | Shanghai_weight | Tianjin_weight | Chongqing_weight | Guangdong_weight |
| Sichuan | 0.322 | 0 | 0 | 0 | 0.02 | 0 |
| Xinjiang | 0.021 | 0 | 0 | 0 | 0.043 | 0 |
| Yunnan | 0.025 | 0 | 0 | 0 | 0.036 | 0 |
| Zhejiang | 0.029 | 0.318 | 0.629 | 0.052 | 0.02 | 0 |
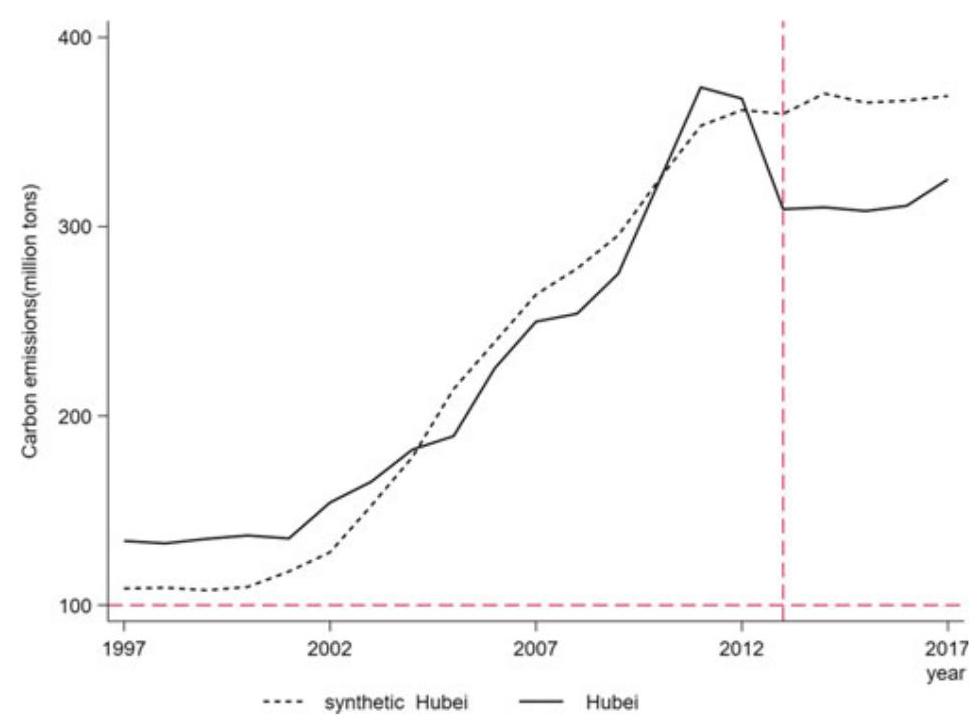
Fig. $4{\mathrm{{CO}}}_{2}$ emissions between Hubei and synthetic Hubei
图$4{\mathrm{{CO}}}_{2}$湖北与合成湖北之间的排放
Due to significant variations of social and economic conditions across different regions in China, we have divergent synthetic results. Generally speaking, the closer to the China’s average level, the better the synthetic results. For instance, Hubei and Guangdong have displayed better synthetic results than that of the other pilots.
由于中国不同地区的社会经济条件存在显著差异,我们得到了不同的合成结果。一般来说,越接近中国平均水平,合成结果越好。例如,湖北和广东的合成结果比其他试点更好。
Figure 4 shows the trend of carbon emissions in real Hubei and synthetic Hubei. The result shows that after 2013, carbon emissions in real Hubei and synthetic Hubei diverged significantly. For impact assessment at a higher level of granularity, so that causal link has a higher degree of certainty, we also apply the same procedure to specific industries, i.e., non-ferrous metals, ferrous metals, electricity industry and six polluting industries ${}^{11}$ in Hubei ETS pilot. The results also demonstrate that these industries in Hubei have all reduced carbon emissions substantially (Fig. 5). ${}^{12}$
图4显示了真实湖北和合成湖北的碳排放趋势。结果表明,2013年之后,真实湖北和合成湖北的碳排放出现了显著差异。为了在更高粒度水平上进行影响评估,以便因果关系具有更高的确定性,我们还对特定行业,即湖北碳排放交易体系试点中的有色金属、黑色金属、电力行业和六个污染行业${}^{11}$应用了相同的程序。结果还表明,湖北的这些行业都大幅减少了碳排放(图5)。${}^{12}$
methods and applications. They provide most up-to-date carbon emission, social, economic, and trade data.
方法与应用。它们提供了最新的碳排放、社会、经济和贸易数据。
${}^{11}$ Six polluting industries include electric power, ferrous metals, nonferrous metals, raw chemical materials and chemical products, nonmetal mineral products, petroleum processing and coking.
${}^{11}$六个污染行业包括电力、黑色金属、有色金属、化学原料和化学制品、非金属矿物制品、石油加工和炼焦。
${}^{12}$ High granularity, industry-specific investigations are particularly important because they may yield insights in terms of cross-region homogeneity or heterogeneity. These insights, if
${}^{12}$高粒度、特定行业的调查尤为重要,因为它们可能会在跨区域同质性或异质性方面产生见解。这些见解,如果
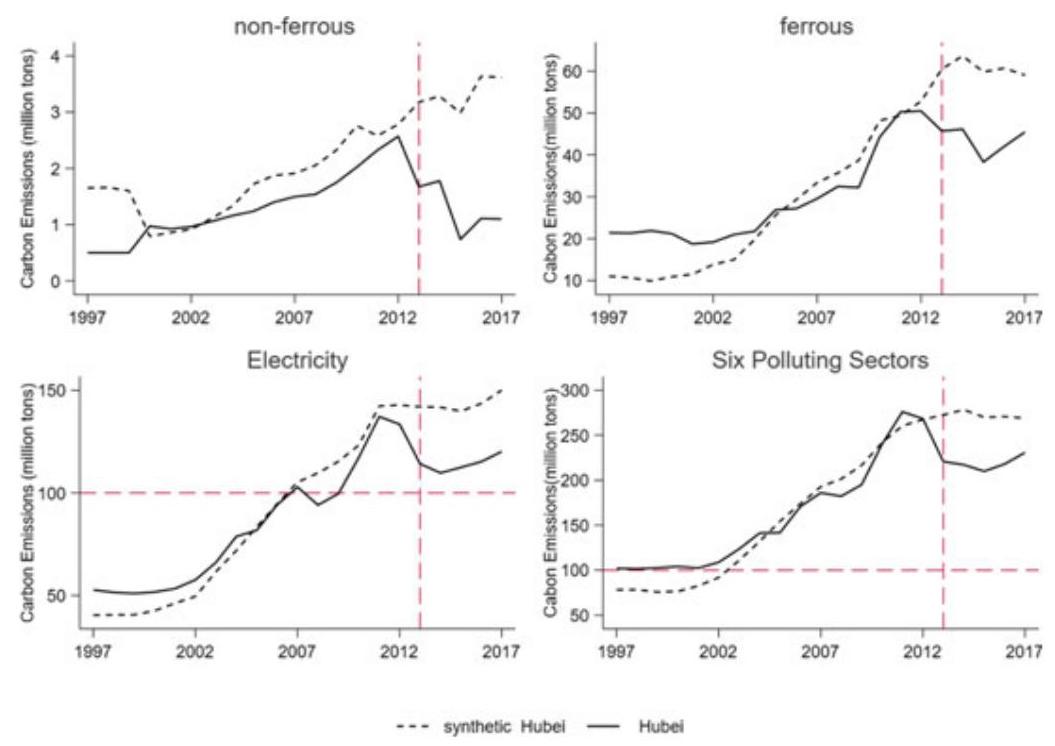
Fig. $5\;{\mathrm{{CO}}}_{2}$ emissions of polluting industries between Hubei and synthetic Hubei
图$5\;{\mathrm{{CO}}}_{2}$湖北与合成湖北之间污染行业的排放
Likewise, Fig. 6 shows that before 2013, the synthetic data fits the actual data reasonably well in the case of Guangdong as well. After 2013, however, the two lines began to diverge significantly, indicating that Guangdong ETS pilot had made a significant difference in the reduction of carbon emissions.
同样,图6显示,在2013年之前,在广东的案例中,合成数据与实际数据也拟合得相当好。然而,2013年之后,两条线开始显著 diverge,表明广东碳排放交易体系试点在减少碳排放方面产生了显著差异。
In the previous section, we have learnt that in terms of trading volume, trading turnover, and active ratio, Hubei and Guangdong (including Shenzhen) scored higher than other regional ETS pilots. Our synthetic test results support our expectation or validate our hypothesis, that is, more trading volume leads to higher levels of emission reduction.
在上一节中,我们了解到,在交易量、交易周转率和活跃度方面,湖北和广东(包括深圳)的表现高于其他区域碳排放交易体系试点。我们的综合测试结果支持了我们的预期或验证了我们的假设,即交易量越大,减排水平越高。
By contrast, the case of Tianjin shows very different results. Figure 7 plots trends of carbons emissions in real Tianjin and synthetic Tianjin. However, the test result shows that since 2013, carbon emissions in real Tianjin and synthetic Tianjin did not differ notably. The result comes as no surprise. As discussed in the previous section, Tianjin ETS pilot was way below average among the seven regional ETS pilots in many performance indicators.
相比之下,天津的情况则显示出截然不同的结果。图7绘制了真实天津和合成天津的碳排放趋势。然而,测试结果表明,自2013年以来,真实天津和合成天津的碳排放量并无显著差异。这个结果并不意外。正如上一节所讨论的,天津碳排放交易体系试点在许多绩效指标上远低于七个区域碳排放交易体系试点的平均水平。
When the same procedure is applied to Beijing, Shanghai, and Chongqing, we cannot get clear-cut simulation results, indicating that it is perhaps too early to assess the actual performance of their ETS pilots at this moment. Or perhaps there are other “noises” that are not factored in and controlled for in our tests. For instance, in the case of Beijing, the dramatic bifurcation between real Beijing and synthetic Beijing had stated around 2008, indicating that there had been much more powerful forces going on other than mere the setup of ETS (Fig. 8). One plausible explanation may have to do with the hosting of Olympic Games in 2008, which had prompted Beijing to relocate much of its manufacturing out of Beijing proper.
当对北京、上海和重庆应用相同的程序时,我们无法得到明确的模拟结果,这表明目前评估其碳排放交易体系试点的实际表现可能还为时过早。或者也许存在其他“干扰因素”,我们在测试中没有考虑到并加以控制。例如,在北京的案例中,真实北京和合成北京之间的显著分歧大约在2008年就开始了,这表明除了碳排放交易体系的设立之外,还有更强大的力量在起作用(图8)。一个合理的解释可能与2008年奥运会的举办有关,这促使北京将许多制造业迁出了市区。
any, can help in designing strategies of convergence between regional and national ETSs in the future.
无论如何,这有助于未来设计区域和国家碳排放交易体系之间的融合策略。
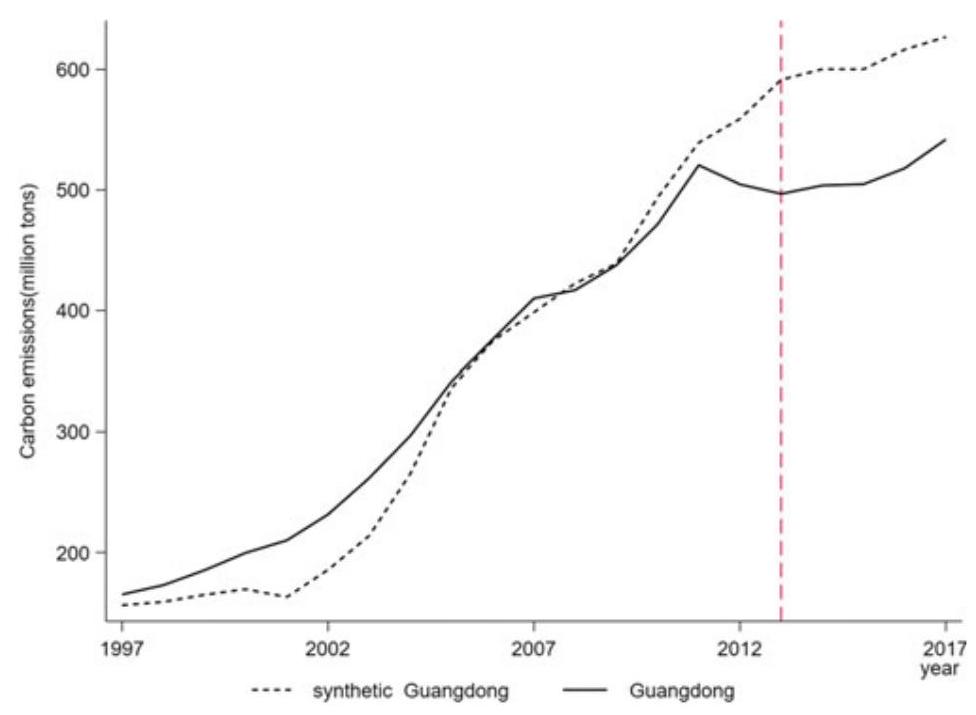
Fig. $6{\mathrm{{CO}}}_{2}$ emissions between Guangdong and synthetic Guangdong
图$6{\mathrm{{CO}}}_{2}$广东与合成广东之间的排放
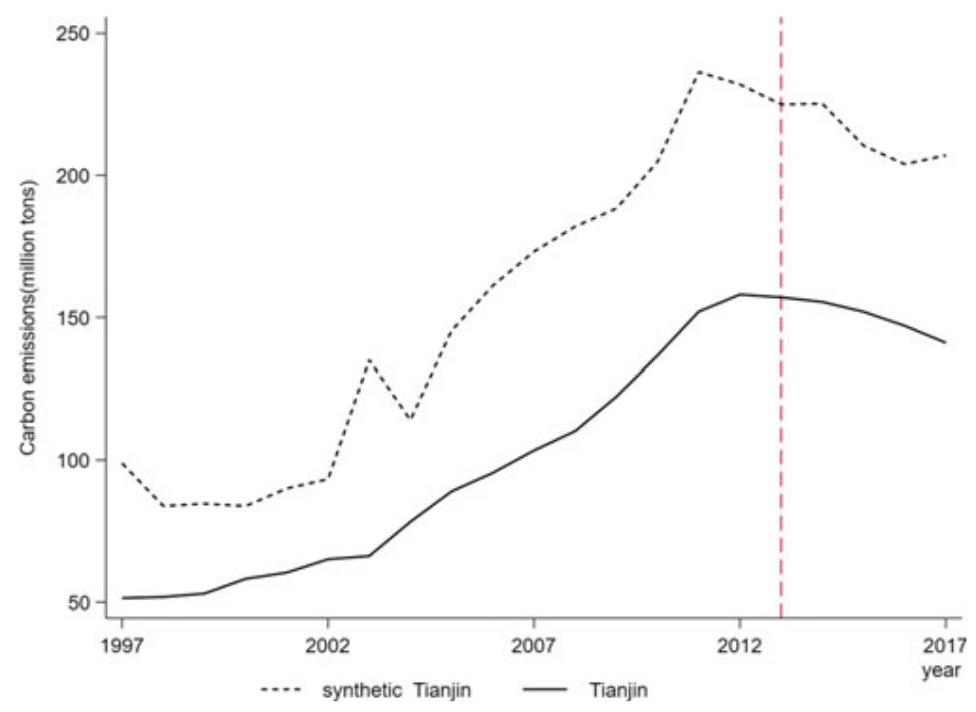
Fig. $7{\mathrm{{CO}}}_{2}$ Emissions between Tianjin and synthetic Tianjin
图$7{\mathrm{{CO}}}_{2}$天津与合成天津之间的排放
And in the case Shanghai, the bifurcation-also very dramatic-had happened even earlier, around 2002 (Fig. 9), which warrants further investigation. Anyway, we must continue to watch Shanghai ETS carefully. Shanghai’s sophisticated dual deployment of grandfathering and auction of ${\mathrm{{CO}}}_{2}$ emission permits and its high compliance rate indicates that it has a nuanced understanding the role of state vis-à-vis that of the market, which normally would lend the city well to address issues related to climate change. After all, it takes both the state and the market to deal with the challenge of climate change and, as our theoretical discussion in Section I indicates, at the axiomatic level of carbon market is politics or public policy. It ultimately goes back to the question raised by Ronald Coase, i.e., where do we draw the line between the state and the market?
而在上海的案例中,这种分歧——同样非常显著——甚至更早发生,大约在2002年(图9),这值得进一步调查。无论如何,我们必须继续密切关注上海的碳排放交易体系。上海在免费分配和拍卖${\mathrm{{CO}}}_{2}$排放许可证方面的复杂双重部署以及其高合规率表明,它对国家与市场的作用有着细致入微的理解。这通常会使这座城市很好地应对与气候变化相关的问题。毕竟,应对气候变化需要国家和市场共同努力,正如我们在第一节中的理论讨论所表明的,在碳排放交易体系的公理层面是政治或公共政策。这最终又回到了罗纳德·科斯提出的问题,即我们如何划分国家与市场之间的界限?
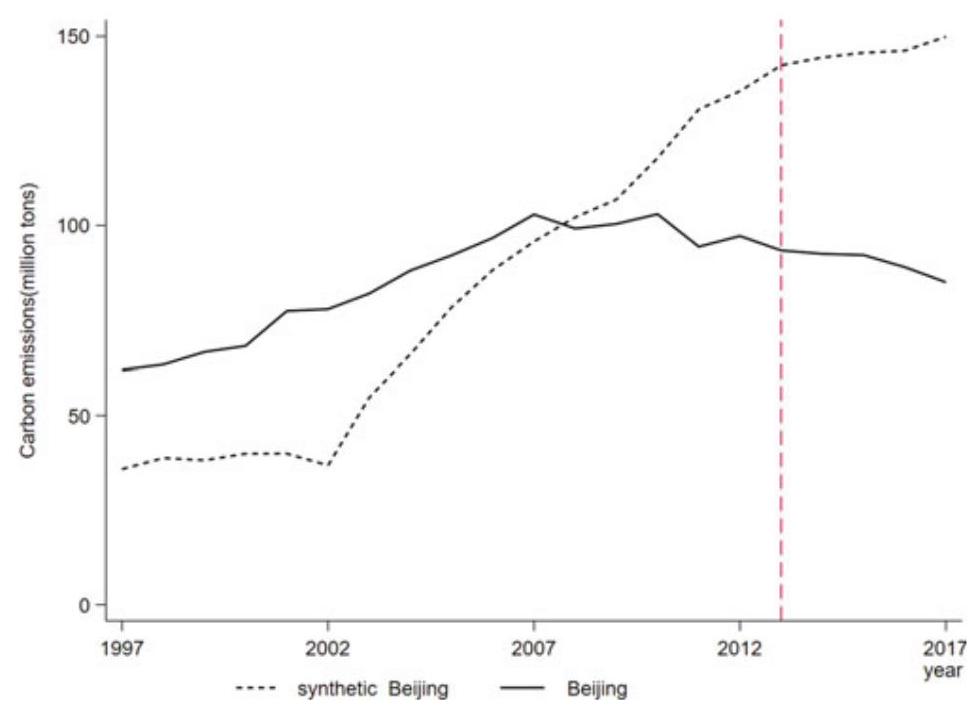
Fig. $8{\mathrm{{CO}}}_{2}$ emissions between Beijing and synthetic Beijing
图$8{\mathrm{{CO}}}_{2}$北京与合成北京之间的排放
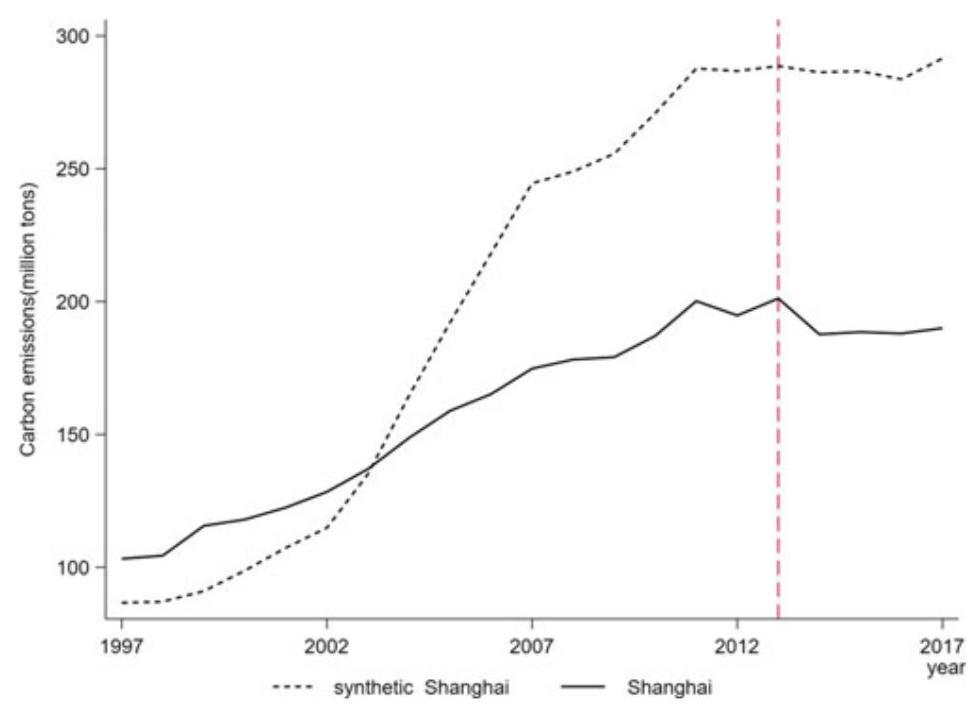
Fig. $9{\mathrm{{CO}}}_{2}$ emissions between Shanghai and synthetic Shanghai
图$9{\mathrm{{CO}}}_{2}$上海与合成上海之间的排放
By comparison, the test result for Chongqing is not compelling, and we put it in the Appendix.
相比之下,重庆的测试结果并不令人信服,我们将其放在附录中。
3.4 Robustness Test
3.4稳健性检验
To increase confidence level to our analyses, we also perform robustness test here. Let us begin by looking at Hubei ETS pilot again. As previously discussed, the test results we obtained by deploying the synthetic control method demonstrated that there was a significant gap of carbon emissions between synthetic Hubei and real Hubei. But how reliable are these results? As an exercise of inductive inference, our knowledge thus obtained can never be deterministic. Indeed, it all boils down to a matter of probability. In this context, a placebo test is appropriate, and it can be regarded as a permutation test in statistics. Our hypothesis testing here is to check statistical significance of our results. In other words, what is the probability that other provinces/cities showing as large a gap as Hubei ETS pilot does between Hubei and synthetic Hubei?
为了提高我们分析的置信水平,我们在此也进行稳健性检验。让我们再次从湖北碳排放权交易试点开始。如前所述,我们通过运用合成控制法得到的测试结果表明,合成湖北与真实湖北之间存在显著的碳排放差距。但这些结果的可靠性如何呢?作为归纳推理的一种实践,我们由此获得的知识永远无法确定。实际上,这一切都归结为一个概率问题。在这种情况下,安慰剂检验是合适的,它可以被视为统计学中的排列检验。我们这里的假设检验是为了检验我们结果的统计显著性。换句话说,其他省份/直辖市在湖北与合成湖北之间呈现出与湖北碳排放权交易试点同样大差距的概率是多少?
To answer the question, we employ the synthetic control method to estimate the effect of policy intervention of ETS on every other province/city. First, we need to drop the provinces/cities that show a poor fit for original data prior to the year when ETS began. Our concern is that even if the gap may not be caused after the policy intervention, it may result from the poor fitness before the policy intervention. Therefore, we have to drop the provinces/cities whose MSPE (mean square percent error) prior to 2013 is larger than 100. Finally, having done these procedures, we have 22 provinces in total as potential control units.
为了回答这个问题,我们运用合成控制法来估计碳排放权交易政策干预对其他每个省份/直辖市的影响。首先,我们需要剔除那些在碳排放权交易开始年份之前对原始数据拟合不佳的省份/直辖市。我们担心的是,即使差距可能不是政策干预后造成的,也可能是政策干预前拟合不佳导致的。因此,我们必须剔除那些2013年之前均方百分比误差(MSPE)大于100的省份/直辖市。最后,完成这些步骤后,我们总共得到22个省份作为潜在的控制单元。
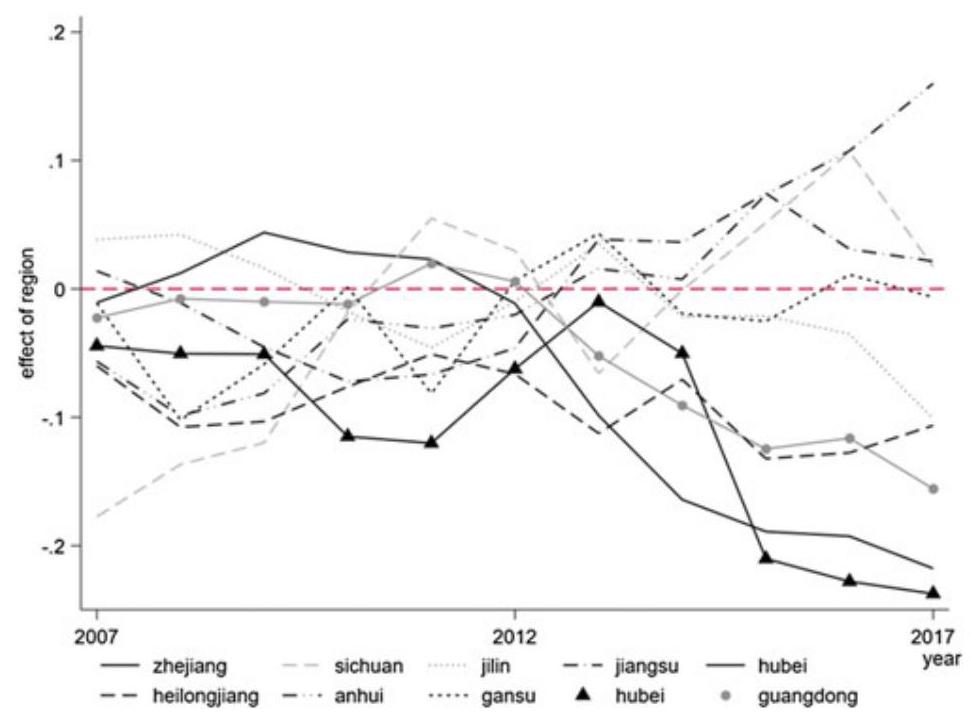
Fig. 10 Placebo test
图10安慰剂检验
Figure 10 displays the placebo or permutation test results.
图10展示了安慰剂或排列检验的结果。
Here, each province/city is taken as a policy-intervened entity each time, with systematic comparison of carbon emissions between real and synthetic situations. From the test results, we can see that Hubei province is below the zero lines, which indicates that the probability of seeing a gap of Hubei’s level in our dataset is $1/{22}$ , or statistically significant only at ${4.5}\%$ or so. Conversely, these test results would increase our confidence level when we say that policy intervention in Hubei in the form of ETS has made a difference in reducing carbon emissions, even though it is still in early stage.
在此,每次将每个省份/直辖市视为一个政策干预实体,系统地比较真实情况与合成情况之间的碳排放。从测试结果中我们可以看到,湖北省位于零线以下,这表明在我们的数据集中出现湖北这种水平差距的概率为$1/{22}$,或者仅在${4.5}\%$左右具有统计显著性。相反,当我们说以碳排放权交易形式对湖北进行的政策干预在减少碳排放方面产生了影响时,尽管仍处于早期阶段,但这些测试结果会提高我们的置信水平。
However, the same thing cannot be said-i.e., with the same level of confidence-for Chongqing (see Fig. 11 in Appendix)and Tianjin at this stage of development. In the case of Beijing and Shanghai, as discussed above, their situations seem to be more complex, and further investigation (e.g., field research) is needed. For the time being, however, in the case of Shanghai, the mixed use of grandfathering and auction in terms of carbon emission permits, together with high rates of compliance, indicates that Shanghai, itself already a financial center, is more sophisticated in setting up a robust MRV system in a cost-effective way. The point here is that while MRV system is vital to ETS, MRV itself is not transaction cost-free. Thus, efforts should be made to minimize the transaction cost in the future design of China’s national ETS.
然而,在当前发展阶段,对于重庆(见附录图11)和天津,不能以同样的置信水平这么说。就北京和上海而言,如上所述,它们的情况似乎更为复杂,需要进一步调查(例如实地研究)。然而目前,以上海为例,碳排放许可的祖父条款与拍卖的混合使用,以及高履约率,表明上海作为一个已经是金融中心的城市,在以具有成本效益的方式建立稳健的监测、报告与核查(MRV)体系方面更为成熟。这里的关键在于,虽然MRV体系对碳排放权交易至关重要,但MRV本身并非没有交易成本。因此,在未来中国全国碳排放权交易体系的设计中应努力将交易成本降至最低。
4 Section 4
4 第4节
4.1 Main Takeaways
4.1 主要结论
At this early stage of construction of carbon market in China, there is initial evidence that the regional ETS pilots are not liquid enough to function well. Trading was low, price was low, and firms did not appear to be enthusiastic about carbon trading. For one thing, information disclosure and transparency have much room for improvement. For another, as regional ETS pilots, policy constraints exist and indeed prohibit cross-region emissions trading, and as a result, carbon price varies significantly across different regions. Arguably, this has made China’s carbon market less attractive to potential investors, especially large institutional investors.
在中国碳市场建设的这个早期阶段,有初步证据表明区域碳排放交易体系试点的流动性不足,无法良好运行。交易量低,价格低,企业似乎对碳交易缺乏热情。一方面,信息披露和透明度有很大的改进空间。另一方面,作为区域碳排放交易体系试点,存在政策限制,实际上禁止跨区域排放交易,因此,不同地区的碳价格差异很大。可以说,这使得中国的碳市场对潜在投资者,尤其是大型机构投资者的吸引力降低。
There is also evidence that the level of awareness of and participation in these regional ETS pilots has remained low. It is especially noteworthy that in the month just before the compliance date there is a sudden and one-time high trading volume. This perhaps indicates that most of the firms would take emissions trading as political cooperation rather than investment opportunity. Carbon assets are not considered valuable for many firms, which arguably is both a cause and effect of low carbon price in China. Overall, the average carbon price among all seven ETS pilots remained low, about RMB 30/ton—perhaps too low for firms seriously to consider strategic shifts towards a low-carbon growth path. ${}^{13}$ By comparison, carbon price in the US and EU was about US$ 15-16/ton (World Bank Group, 2018) and is expected to rise rapidly in the years to come.
也有证据表明,这些区域碳排放交易体系试点的认知度和参与度仍然很低。特别值得注意的是,在履约日期前一个月,交易量突然出现一次性大幅增长。这或许表明,大多数企业将排放交易视为一种政治合作,而非投资机会。对许多企业来说,碳资产并不被视为有价值的资产,这可以说是中国碳价格低的一个原因,也是其结果。总体而言,所有七个碳排放交易体系试点的平均碳价格仍然很低,约为30元/吨——这可能太低了,企业难以认真考虑向低碳增长路径的战略转变。${}^{13}$ 相比之下,美国和欧盟的碳价格约为15 - 16美元/吨(世界银行集团,2018年),预计在未来几年将迅速上涨。
${}^{13}$ However, in 2020 the Chinese government made a new pledge to international community to peak carbon emission prior to 2030 and achieve carbon neutrality by 2060. In light of this, it is expected that carbon price would rise more rapidly under much harder constraints of “cap and trade” scheduled over the next 40 years, thus generating more pressure for fossil-fuel heavy firms to plan and shift more aggressively towards green growth. The new pledge also indicates that the centrality of China’s climate policy in terms of international commitments has shifted from one that emphasized “carbon equity” to one that aims at “carbon neutrality”.
${}^{13}$ 然而,2020年中国政府向国际社会作出新的承诺,即到2030年前实现碳排放达峰,并在2060年前实现碳中和。有鉴于此,预计在未来40年“总量控制与交易”的更严格约束下,碳价格将更快上涨,从而给化石燃料密集型企业带来更大压力,促使它们更积极地规划和转向绿色增长。这一新承诺还表明,中国气候政策在国际承诺方面的核心地位已从强调“碳公平”转向旨在“碳中和”。
Our analyses show that while success of these regional ETS pilots at this stage is very limited, it still varies considerably across different regions. Among the seven regional ETS pilots, Hubei is the best performer, and it has reduced about 59 million tons of ${\mathrm{{CO}}}_{2}$ emissions in 2015. Guangdong and Shenzhen have done reasonably well, each having reduced about 37 million tons of ${\mathrm{{CO}}}_{2}$ emissions in 2015. In the case of Beijing and Shanghai, the effects of ETSs, while not immediately visible, may have been overwhelmed by earlier policy inventions (e.g., holding 2008 Olympics in Beijing), which warrants further (field-trip) investigations beyond our current setup of econometrics. However, Tianjin has performed poorly during the same period.
我们的分析表明,虽然这些区域碳排放交易体系试点现阶段的成功非常有限,但不同地区之间仍存在很大差异。在七个区域碳排放交易体系试点中,湖北表现最佳,2015年减少了约5900万吨 ${\mathrm{{CO}}}_{2}$ 排放。广东和深圳表现也不错,2015年各自减少了约3700万吨 ${\mathrm{{CO}}}_{2}$ 排放。就北京和上海而言,碳排放交易体系的效果虽然不立竿见影,但可能被早期的政策举措(如北京举办2008年奥运会)所掩盖,这需要在我们目前的计量经济学设置之外进行进一步的(实地考察)调查。然而,天津在同一时期表现不佳。
Why? Some preliminary explanations are handy. Hubei has been a province with a progressive environmental agenda. In 2009, a pilot program for converting punitive levy of pollution to environmental tax was launched in Hubei. Zheng’s research (2015) indicates that such pilot programs significantly reduced domestic pollutions, which might also have better prepared industrial firms in Hubei for the carbon trading scheme. During the whole era of reform and opening-up, Shenzhen has always been China’s leading city in innovations and was China’s first city to realize its “Blue Sky Plan.” The general orientation of the government and the business sector of Shenzhen are market-driven, and so is Guangdong province. As such, the relatively good performance of Guangdong ETS pilot comes as no surprise. At the moment, we do not know exactly what is going on in Tianjin. Anyway, its low trading volume indicates that Tianjin is not ready as an active player in the carbon market in China. A plausible cause may have to do with firm ownership and industrial structure of the city for historical reasons. Deeper research is needed here.
为什么?一些初步解释很容易找到。湖北一直是一个有着进步环境议程的省份。2009年,湖北启动了将污染惩罚性征收转换为环境税的试点项目。郑(2015年)的研究表明,此类试点项目显著减少了国内污染,这可能也让湖北的工业企业为碳交易计划做好了更好的准备。在改革开放的整个时期,深圳一直是中国创新的领先城市,也是中国第一个实现“蓝天计划”的城市。深圳政府和商业部门的总体取向是市场驱动的,广东省也是如此。因此,广东碳排放交易体系试点表现相对较好也就不足为奇了。目前,我们并不确切知道天津的情况。无论如何,其低交易量表明天津还没有准备好成为中国碳市场的积极参与者。一个合理的原因可能与该市的企业所有权和产业结构有关,这是历史原因造成的。这里需要更深入的研究。
4.2 Policy Recommendations
<### 4.2 政策建议
The ETS is purported to give China additional market-based tools to realize its Paris commitments. Since 2013, seven regional ETS pilots have been launched to test their validity in the context of China. According to China’s overall roadmap of ETS construction, if these ETS pilots are successful during the first phase of construction (2011-2017), China would scale up them to the national level by the end of 2017 and begin the second phase (2017-2020) of construction of carbon market. In this context, our study represents an initial assessment of these regional ETS pilots, with an aim to provide lessons for the construction of a future unified ETS at the national level. We find that the success so far is limited and uneven amongst the seven regional ETS pilots, which warrants further investigation into the underlying causes.
碳排放交易体系旨在为中国提供更多基于市场的工具,以实现其巴黎承诺。自2013年以来,中国已启动七个区域碳排放交易体系试点,以检验其在中国背景下的有效性。根据中国碳排放交易体系建设的总体路线图,如果这些试点在建设的第一阶段(2011 - 2017年)取得成功,中国将在2017年底将其扩大到国家层面,并开始碳市场建设的第二阶段(2017 - 2020年)。在此背景下,我们的研究对这些区域碳排放交易体系试点进行了初步评估,旨在为未来国家层面统一碳排放交易体系的建设提供经验教训。我们发现,到目前为止,七个区域碳排放交易体系试点的成功有限且不均衡,这值得进一步调查其背后的原因。
The limited and uneven success of these regional ETS pilots calls for caution when thinking about nationwide expansion of carbon market. More systematic evaluation and deeper investigation should be conducted to pin down the underlying social and economic causes before decision of expansion to the national level is made.
这些区域碳排放交易体系试点有限且不均衡的成功,在考虑碳市场全国性扩张时需要谨慎。在决定向国家层面扩张之前,应进行更系统的评估和更深入的调查,以确定潜在的社会和经济原因。
To begin with, information transparency about actual carbon emissions is necessary. There, China urgently needs to build up a sophisticated system of monitoring, reporting, and verification (MRV) for corporate ESG (environment, social responsibility, and corporate governance), including the training of manpower. Indeed, a clean, reliable and robust MRV system is an integral part of the basic infrastructure of ETS. This is especially important when China launches a national ETS in the near term (in 2020), and in the medium- and long-term, integrates its ETS with international ETSs. In short, a unified digital MRV system should be treated as a prerequisite for current regional ETSs to scale up to a higher level in the future. ${}^{14}$ Here, regional and international cooperation and coordination with an aim to converge (rather than diverge) in the future is desired. This is especially the case were it also to reduce risks and facilitate long-term cross-border business investments. Besides, there are other two points to make at this moment, and they are as follow:
首先,实际碳排放的信息透明度至关重要。在此,中国迫切需要建立一个完善的企业环境、社会责任和公司治理(ESG)监测、报告和核查(MRV)体系,包括人力培训。事实上,一个清洁、可靠且强大的MRV体系是碳排放交易体系基础设施的重要组成部分。当中国在近期(2020年)启动国家碳排放交易体系,并在中长期将其与国际碳排放交易体系整合时,这一点尤为重要。简而言之,统一的数字MRV体系应被视为当前区域碳排放交易体系未来向更高水平发展的先决条件。${}^{14}$ 在此,期望开展区域和国际合作与协调,以在未来实现趋同(而非分歧)。如果这样做还能降低风险并促进长期跨境商业投资,情况尤其如此。此外,此刻还有另外两点需要说明,如下所示:
First, the limited achievement of ETS pilots triggers a more fundamental issue. That is, the role of local government officials. Indeed, it has been long argued that the incentive for local government officials has been the weakest link in the value chain of environmental protection in China. So far, the principal pursuit of Chinese local government officials is economic growth measured by GDP rather than long-term concerns of sustainable development. The ETS scheme will probably not be sufficient to alter the behavior of local government officials especially when carbon emission permits are distributed in a fashion of grandfathering. Indeed, there is initial evidence that those with auctions (e.g., Shenzhen, Guangdong, Hubei) performed better than those without (e.g., Chongqing, Tianjin) among the seven regional ETS pilots.
首先,碳排放交易体系试点有限的成果引发了一个更根本的问题。即地方政府官员的作用。长期以来,人们一直认为地方政府官员的激励机制是中国环境保护价值链中最薄弱的环节。到目前为止,中国地方政府官员的主要追求是以国内生产总值衡量的经济增长,而非可持续发展的长期考量。碳排放交易体系计划可能不足以改变地方政府官员的行为,特别是当碳排放许可以免费分配的方式进行时。事实上,初步证据表明,在七个区域碳排放交易体系试点中那些采用拍卖方式(如深圳、广东、湖北)的地区表现优于未采用拍卖方式的地区(如重庆、天津)。
In the future, a priced carbon permit should be tested in ways similar to that of EU-ETS, where auction is allowed and the proportion of auction (relative to free allowances) gradually goes up over time. It might even be better if a carbon tax scheme be tested as an additional policy tool. France, for instance, imposes carbon tax of US$ 55/ton and so does Norway at US$ 64/ton. ${}^{15}$
未来,应采用类似于欧盟碳排放交易体系的方式对碳排放许可定价进行测试,即允许拍卖,且拍卖比例(相对于免费配额)随时间逐渐提高。如果将碳税方案作为额外的政策工具进行测试,可能会更好。例如,法国征收每吨55美元的碳税,挪威征收每吨64美元的碳税。${}^{15}$
${}^{14}$ Understandably, the building of the data centers of digital MRV system for these regional ETS pilots would be an incremental process. But to think and plan ahead, these data centers as critical backbones of ETS networks should go green themselves. That is, they should not be driven by fossil energy but by renewable energy.
${}^{14}$ 可以理解,为这些区域碳排放交易体系试点构建数字MRV系统的数据中心将是一个渐进的过程。但为了提前思考和规划,这些作为碳排放交易体系网络关键支柱的数据中心自身应实现绿色化。也就是说,它们不应由化石能源驱动,而应由可再生能源驱动。
Second, the uneven success across the seven regional ETS pilots may reflect regional variations in firm ownership and industrial structure due to historical reasons. If it is true, caution is needed when one considers scaling-up regional ETS pilots to a unified national carbon market in China after 2017. It would seem that a big bang rather than a gradual approach is not appropriate. A better approach has to be sector-sensitive with phase-in mechanisms. More specifically, it would allow different phase-in periods for various sectors in the national ETS, while at the same time keeping some region-specific industries in the regional ETSs before the two systems-the national and the regional ETSs-converge incrementally and eventually join tracks in the long-run. The same approach should also apply to forging links with international ETSs in the long run.
其次,七个区域碳排放交易体系试点成功程度的不均衡可能反映了由于历史原因导致的企业所有权和产业结构的区域差异。如果是这样,在考虑2017年后将区域碳排放交易体系试点扩大到统一的国家碳市场时需要谨慎。似乎“大爆炸”式而非渐进式的方法并不合适。更好的方法必须对行业敏感并采用逐步引入机制。更具体地说,这将允许国家碳排放交易体系中不同行业有不同的逐步引入期,同时在国家和区域碳排放交易体系逐步趋同并最终在长期接轨之前,将一些特定区域的行业保留在区域碳排放交易体系中。从长远来看,同样的方法也应适用于与国际碳排放交易体系建立联系。
Indeed, as we discussed earlier in the chapter, EU-ETS has phase-in designs, although the industrial structure of its member states is far more homogeneous than that of China. Otherwise, as unintended consequences, we may run the risk of making rich regions richer and poor regions poorer. In the meantime, fiscal subsidies or transfers across regions by the central government may serve as remedial measures to ameliorate the problem, one may argue. But ultimately, these measures contradict-or at least generate tensions with-the market principle of equality if and when China tries to join international ETSs in the long run. Beware of these tensions, as one moves forward.
事实上,正如我们在本章前面所讨论的,欧盟排放交易体系有逐步实施的设计,尽管其成员国的产业结构比中国的产业结构更加同质化。否则,作为意外后果,我们可能会面临使富裕地区更富、贫困地区更穷的风险。有人可能会说,与此同时,中央政府在地区间的财政补贴或转移支付可以作为缓解这一问题的补救措施。但从长远来看,如果中国试图加入国际排放交易体系,这些措施与平等的市场原则相矛盾,或者至少会产生紧张关系。在向前推进时,要警惕这些紧张关系。
That said and looking ahead, we would recommend that the overall approach to market-building of ETS should move with a vector from regional equilibrium to general equilibrium. In other words, given the experience gained thus far from these regional ETSs, what China should do years down the road is to build not just a simple and static model of “cap & trade” but a complex and dynamic model somewhat along the line from RICE to DICE model developed by Nobel Laureate in economics Nordhaus (2000). ${}^{16}$ The complex model should simultaneously consider the economic, political, and institutional aspects of environmental intervention, along with international cooperation and coordination. Indeed, facing the enormous challenge of climate change, what is needed is not just breakthrough “hardware technologies” but also “sophisticated institutional technologies” to reduce GHG on this small village that we call Earth (Fu, 2009).
话虽如此,展望未来,我们建议排放交易体系市场建设的总体方法应从区域均衡向一般均衡转变。换句话说,鉴于从这些区域排放交易体系中获得的经验,中国未来几年应该做的不仅仅是建立一个简单静态的“总量控制与交易”模型,而是建立一个复杂动态的模型,类似于诺贝尔经济学奖得主诺德豪斯(2000年)开发的从RICE到DICE模型。${}^{16}$这个复杂的模型应同时考虑环境干预的经济、政治和制度方面,以及国际合作与协调。事实上,面对气候变化的巨大挑战,我们不仅需要突破性的“硬件技术”,还需要“先进的制度技术”来在我们称之为地球的这个小村庄减少温室气体排放(傅,2009年)。
${}^{15}$ Of late the EU has started to consider imposing CBAM taxes (or cross border adjustment mechanism) to avoid carbon leakage. Although difficulties still exist at the moment in terms of data availability and exact calculations, if that happens, it would have immediate impact on Chinese exports, e.g., steel products. The long process of steelmaking (BF/BOF), which still dominates the Chinese steel sector (about 90%) is much more carbon intensive than the short process (EAF). EAF accounts for about 47% globally, excluding China. See Chapters 2, 3 and 4 of this book. Ceteris paribus, in case of imposing cross-border carbon tax, the global market share of Chinese steel exports would be squeezed.
${}^{15}$最近欧盟已开始考虑征收碳边境调节机制税(CBAM)以避免碳泄漏。尽管目前在数据可用性和精确计算方面仍存在困难,但如果实施,这将对中国出口产生直接影响,例如钢铁产品。在中国钢铁行业仍占主导地位(约90%)的长流程炼钢(高炉/转炉)比短流程(电弧炉)的碳密集度高得多。电弧炉在全球(不包括中国)约占47%。见本书第2、3和4章。在其他条件相同的情况下,如果征收跨境碳税,中国钢铁出口的全球市场份额将受到挤压。
${}^{16}$ RICE and DICE are a pair of models integrating climate change with economics developed by William Nordhaus, a 2018 Nobel Prize winner in Economic Sciences. RICE stands for regional dynamic integrated model of climate and the economy, whereas DICE stands for dynamic integrated model of climate and the economy.
${}^{16}$RICE和DICE是由2018年诺贝尔经济学奖得主威廉·诺德豪斯开发的一对将气候变化与经济学相结合的模型。RICE代表区域气候与经济动态综合模型,而DICE代表气候与经济动态综合模型。
Appendix
附录
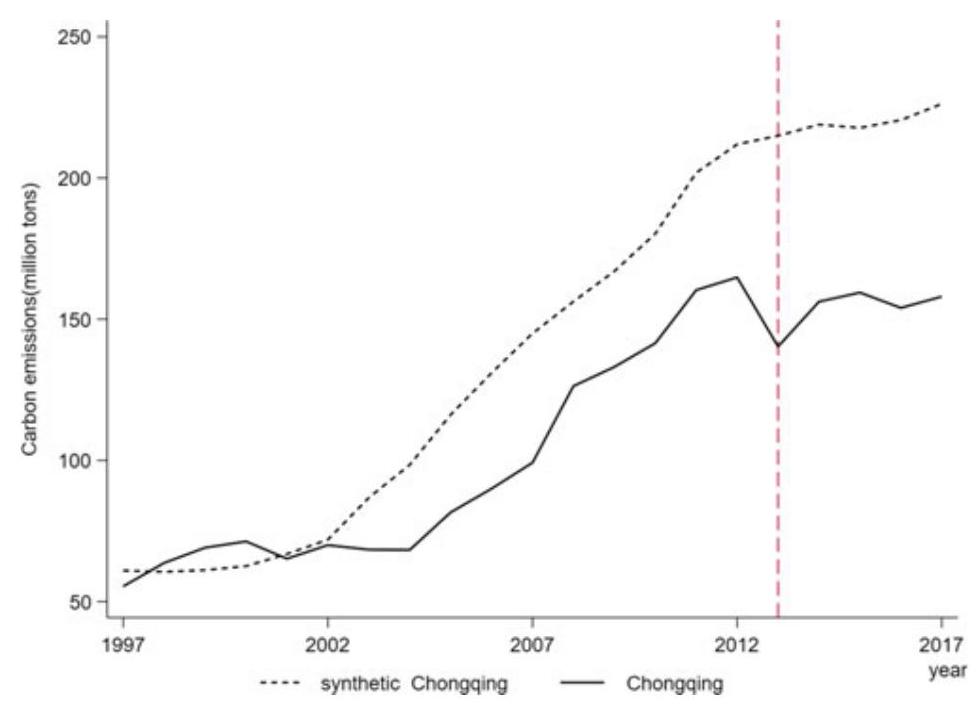
Fig. 11 ${\mathrm{{CO}}}_{2}$ emissions between Chongqing and synthetic Chongqing
图11重庆与合成重庆之间的${\mathrm{{CO}}}_{2}$排放
Acronym Full spelling
首字母缩写 全称
CBAM Cross border adjustment mechanism
CBAM 跨境调整机制
CCER China certified emission reduction
CCER 中国核证自愿减排量
CCX Chicago climate exchange
CCX 芝加哥气候交易所
DICE Dynamic integrated model of climate and the economy
DICE 气候与经济动态综合模型
ESG Environment, social responsibility, and corporate governance
ESG 环境、社会责任和公司治理
ETG Emissions Trading Group
ETG 排放交易集团
ETS Emission-trading system
ETS 排放交易体系
EU-ETS European union greenhouse gas emission trading system
EU-ETS 欧盟温室气体排放交易体系
FYR Five year plan
FYR 五年计划
GHG Greenhouse gas
GHG 温室气体
KPI Key performance indicators
KPI 关键绩效指标
MRV Monitoring, reporting and verification
MRV 监测、报告与核查
MSPE Mean square percent error
MSPE 均方百分比误差
NDRC National development and reform commission
国家发展和改革委员会
NSW National Trust of Australia
澳大利亚国家信托
RICE Regional dynamic integrated model of climate and the economy
区域气候与经济动态综合模型
UNFCCC United Nations framework convention on Climate Change
《联合国气候变化框架公约》
References
参考文献
Abadie, A., & Gardeazabal, J. (2003). The economic costs of conflict: A case study of the basque country. American Economic Review, 93(1), 113-132.
Abadie, A., Diamond, A., & Hainmueller, J. (2010). Synthetic control methods for comparative case studies: Estimating the effect of california’s tobacco control program. Journal of the American Statistical Association, 105(490), 493-505.
Abadie, A., Diamond, A. J., et al. (2015). Comparative politics and the synthetic control method. American Journal of Political Science, 59(2), 495-510.
Ando, M. (2015). Dreams of urbanization: Quantitative case studies on the local impacts of nuclear power facilities using the synthetic control method. Journal of Urban Economics, 85(C), 68-85.
Coase, R. H. (1960). “The Problem of Social Cost”. Journal of Law and Economics, The University of Chicago Press, vol. 3, October, 1-44.
Duan, M., Tao, P., & Zhang, X. (2014). Review of carbon emissions trading pilots in China. Energy & Environment, 25, 527-550.
European Commission. (2003). Directive 2003/87/87/EC of the European Parliament and of the Council of October 2003 establishing a scheme for greenhouse gas emission allowance trading within the Community and amending Council Directive 96/61/EC.
European Commission. (2015). EU ETS handbook. European Commission.
Fu, J. (2009). The Dao of the Wealth of Nations. Peking University Press. p 373.
Kossoy, A., Oppermann, K., Platonovaoquab, A., et al. (2015). State and trends of carbon pricing. World Bank Group Climate Change, Washington DC: October 2015.
Mideksa, T. K., & Weitzman, M. L. (2019). Prices versus quantities across jurisdictions. Journal of the Association of Environmental and Resouce Economisits., 6(5), 883-891.
Liu, J., & Fan, Z. (2018). Research on the influence of industrial transfer from the property taxes: Empirical research from Chongqing and Shanghai(in Chinese). China Industrial Economics, 11, 98-116.
Nordhaus, W. D., & Boyer, J. (2000). Warming the world: economic models of global warming. The MIT Press (2000).
Pang, T., & Duan, M. (2016). Cap setting and allowance allocation in China’s emissions trading pilot programs: Special issues and innovative solutions. Climate Policy, 16, 815-835.
Pigou, A. C. (1929). The economics of welfare. London: MacMillan and Co., Ltd.
Spence, A. M., & Weitzman, M. L. (1978). Regulatory strategies for pollution control. In: A. F. Friediaender (Ed.), Approaches to controlling air pollution. Cambridge MA: MIT Press.
Stavins, R. (2001). experience with market-based environmental policy instruments. Resource for the Future.
UNFCCC. (1998). Kyoto protocol to the United Nations framework convention on climate change. United Nations. Available at http//unfccc.int/Convkp/kpeng/kpeng.pdf.
Weitzman, M. L. (1974, October). Prices vs. Quantities. The Review of Economics Studies, 41(4), 477-491.
Weitzman, M. L. (2012). GHG targets as insurance against catastrophic climate damages. Journal of Public Economic Theory., 14(2), 221-244.
Weitzman, M. L. (2017). On a World Climate Assembly and the Social Cost of Carbon. Economica, 84(336), 559-586.
World Bank Group. (2018). State and trends of carbon pricing 2018 (p. 2019). World Bank Group.
Zhang, J., Zhong, C., & Ming, Y. (2016). Did Olympic Games improve air quality in Beijing? Based on the synthetic control method. Environmental Economics and Policy Studies, 18, 21-39.
Design Options of ETS: How to Incentivize CCUS
条目编号“0”:排放交易体系(ETS)的设计选项:如何激励碳捕获、利用与封存(CCUS)
Mengfei Jiang, Xi Liang, Ming Lei, Francisco Ascui, Qianguo Lin, Muxin Liu, and Li Wang
姜梦菲、梁熙、雷鸣、弗朗西斯科·阿斯库伊、林乾国、刘慕昕、王莉
The urgency of rapid and ambitious climate action was underscored in IPCC Special Report on ${1.5}{}^{ \circ }\mathrm{C}$ . In the report, IPCC also emphasized that strong carbon price signals, coupled with further policy instruments, can support ambitious and cost-effective ${\mathrm{{CO}}}_{2}$ emission reductions. As contracting states to the Paris Agreement look to implement their domestic climate policies, carbon markets are emerging and evolving to fill an important role in their strategic transition to a green economy. Worldwide, carbon markets, or emissions trading systems (ETS), have become a critical part of the policy response. China is no exception. As the previous chapter discussed, China rolled out 7 regional ETS pilots in 2013. Subsequently, as this chapter will discuss as a follow-up, China’s national ETS was launched in 2017 and was expected to become operational around ${2020.}^{1}$
IPCC关于${1.5}{}^{ \circ }\mathrm{C}$的特别报告强调了迅速且雄心勃勃地采取气候行动的紧迫性。该报告中,IPCC还强调,强劲的碳价格信号,再加上其他政策工具,能够支持雄心勃勃且具有成本效益的${\mathrm{{CO}}}_{2}$减排。随着《巴黎协定》缔约国寻求实施其国内气候政策,碳市场正在兴起并不断发展,以在其向绿色经济的战略转型中发挥重要作用。在全球范围内,碳市场或排放交易体系(ETS)已成为政策应对措施的关键组成部分。中国也不例外。如前一章所述,中国于2013年推出了7个区域ETS试点。随后,正如本章将作为后续讨论的那样,中国的国家ETS于2017年启动,预计将在${2020.}^{1}$左右投入运营
${}^{1}$ At the time when this study went to the press, on July 16,2021, China’s national ETS officially went into operation, covering 2162 power plants and over 4 billion tons of carbon emissions annually. It thus became the largest of the 31 ETSs currently extant in the world. Whereas Beijing hosted China’s national ETS center, Shanghai was tasked with trading, and Hubei with registration. The price of the first deal on that day was RMB52.78/tCO2-much higher as compared to the average price of about RMB40/tCO ${}_{2}$ of China’s 7 regional ETS pilots in past two years. It has been expected that China’s national ETS will eventually cover petrochemical, chemical, building material, iron/steel, nonferrous, paper-making, and aviation industries as well.
${}^{1}$ 在本研究付梓之时,即2021年7月16日,中国国家碳排放交易体系正式启动,涵盖2162家发电厂,每年碳排放超过40亿吨。这使其成为目前全球现存的31个碳排放交易体系中规模最大的一个。北京是中国国家碳排放交易体系的中心,上海负责交易,湖北负责注册。当日首笔交易价格为52.78元/吨二氧化碳,相比过去两年中国7个区域碳排放交易试点约40元/吨二氧化碳${}_{2}$ 的平均价格要高得多。预计中国国家碳排放交易体系最终还将覆盖石化、化工、建材、钢铁、有色、造纸和航空等行业。
M. Lei ( )
雷明( )
School of Management, Peking University, Beijing, China
中国北京 北京大学光华管理学院
M. Jiang - X. Liang - F. Ascui - Q. Lin
姜梦菲 - 梁熙 - 弗朗西斯科·阿斯库伊 - 林乾国
University of Edinburgh Business School, Edinburgh, UK
英国爱丁堡 爱丁堡大学商学院
M. Liu - L. Wang
刘慕昕 - 王莉
UK-China (Guangdong) CCUS Center, Guangzhou, China
中国广州 英国 - 中国(广东)CCUS中心
According to the International Energy Agency (IEA), the steel sector accounts for over 5% of global anthropogenic GHG emissions. China is the largest steel producer in the world, accounting for about 51% of global crude steel production in 2018. Currently, the steel sector accounts for over 10% of China’s total domestic anthropogenic ${\mathrm{{CO}}}_{2}$ emissions, making it the third largest source of ${\mathrm{{CO}}}_{2}$ emissions in China-after power and cement. How best to decarbonize the steel sector in China in the years ahead? Essentially, there are basic four pathways to de-carbonize the iron/steel sector: (a) switching to zero-emission fuels (e.g., hydrogen), (b) improving energy efficiency, (c) structural adjustment (e.g., from long to short process), and (d) implementing carbon capture, utilization and storage (CCUS). ${}^{2}$ As pathway (a) would incur large costs to change the exiting outlay of the steeling making process, thus far China has largely relied on pathways (b) and (c); but the marginal effects of (b) and (c) have been on the decline. In this context, one would expect that pathway (d), i.e., CCUS, will increasingly become important in the years ahead.
根据国际能源署(IEA)的数据,钢铁行业占全球人为温室气体排放的5%以上。中国是世界上最大的钢铁生产国,2018年约占全球粗钢产量的51%。目前,钢铁行业占中国国内人为${\mathrm{{CO}}}_{2}$排放总量的10%以上,使其成为中国仅次于电力和水泥的第三大${\mathrm{{CO}}}_{2}$排放源。未来几年,如何在中国实现钢铁行业的最佳脱碳?从本质上讲,钢铁行业脱碳有四条基本途径:(a)改用零排放燃料(如氢气),(b)提高能源效率,(c)结构调整(如从长流程到短流程),以及(d)实施碳捕获、利用与封存(CCUS)。${}^{2}$ 由于途径(a)改变炼钢工艺现有支出的成本过高,到目前为止,中国主要依赖途径(b)和(c);但(b)和(c)的边际效应一直在下降。在这种背景下,可以预期,途径(d),即CCUS,在未来几年将变得越来越重要。
Building upon previous discussions on carbon market in Chapter 5, the aim of this chapter is to further explore CCUS in connection with ETS. Specifically, the central question is: as China continues to build a national carbon market based on the experience of 7 regional ETS pilots, how could different design options of ETS incentivize CCUS application in the steel sector, given the fact that the current cost of CCUS has remained high in spite of cost reductions in recent years? To answer this question, we will put Chinese experience in a broader international perspective.
基于第五章对碳市场的讨论,本章旨在进一步探讨与ETS相关的CCUS。具体而言,核心问题是:在中国基于7个区域ETS试点的经验继续建设国家碳市场的情况下,鉴于尽管近年来成本有所降低,但目前CCUS的成本仍然很高,ETS的不同设计选项如何激励CCUS在钢铁行业的应用?为了回答这个问题,我们将把中国的经验置于更广阔的国际背景中。
This chapter is organized into four sections. For international comparisons, Section 1 begins by briefly reviewing the key design elements of international experience. Section 2 then looks at the current designs and operations of ETS pilots in China Drawing heavily on EU experience, Section 3 introduces and analyses three different design options of ETS in connection with financing schemes of CCUS in the iron/steel sector. Conclusions follow in Section 4.
本章分为四个部分。为了进行国际比较,第1节首先简要回顾国际经验的关键设计要素。第2节接着审视中国ETS试点的当前设计与运营情况。第3节大量借鉴欧盟经验,介绍并分析与钢铁行业CCUS融资方案相关的ETS的三种不同设计选项。第4节给出结论。
1 Section 1
1 第1节
1.1 Key Design Elements of ETS in International Perspective
<### 1.1 国际视角下排放交易体系(ETS)的关键设计要素
Essentially, there are two generic approaches to emissions trading system (ETS) (see Fig. 1): cap-and-trade and baseline-and-credit systems. In cap-and-trade, a regulator sets the total amount of emissions that can be emitted during a certain period (the cap) by issuing a limited number of allowances to emit. At the end of each compliance period, covered entities ${}^{3}$ Covered entities are defined as installations in EU-ETS and as enterprises in China’s ETS must surrender allowances equal to their emissions during a certain period. ${}^{4}$ Covered entities could acquire allowances directly from the regulator (primary market) or from other participants by trading in the secondary market. Allowance allocation is the key to a successful carbon market (Xiong et al., 2015). Most ETSs around the world have started with free allocation but gradually transitioned to a higher percentage of allowances being auctioned. ${}^{5}$ Regulators usually apply one of two different allocation methods to allocate free allowance to covered entities: grandfathering and benchmarking.
从本质上讲,排放交易体系(ETS)有两种通用方法(见图1):总量控制与交易以及基准与信用体系。在总量控制与交易体系中,监管机构通过发放有限数量的排放许可来设定特定时期内可排放的总量(上限)。在每个履约期结束时,${}^{3}$ 在欧盟排放交易体系(EU-ETS)中,涵盖实体被定义为设施;在中国排放交易体系中,涵盖实体被定义为企业 必须交出与其在特定时期内排放量相等的许可。${}^{4}$ 涵盖实体可以直接从监管机构(一级市场)获取许可,也可以通过在二级市场交易从其他参与者那里获取。许可分配是成功的碳市场的关键(熊等人,2015年)。全球大多数排放交易体系都始于免费分配,但逐渐过渡到更高比例的许可通过拍卖分配。${}^{5}$ 监管机构通常采用两种不同的分配方法之一向涵盖实体分配免费许可:祖父条款法和基准法。
${}^{2}$ For more on CCUS, see Chapters 3 and 5 of this book.
${}^{2}$ 有关碳捕获、利用与封存(CCUS)的更多信息,请参阅本书第3章和第5章。
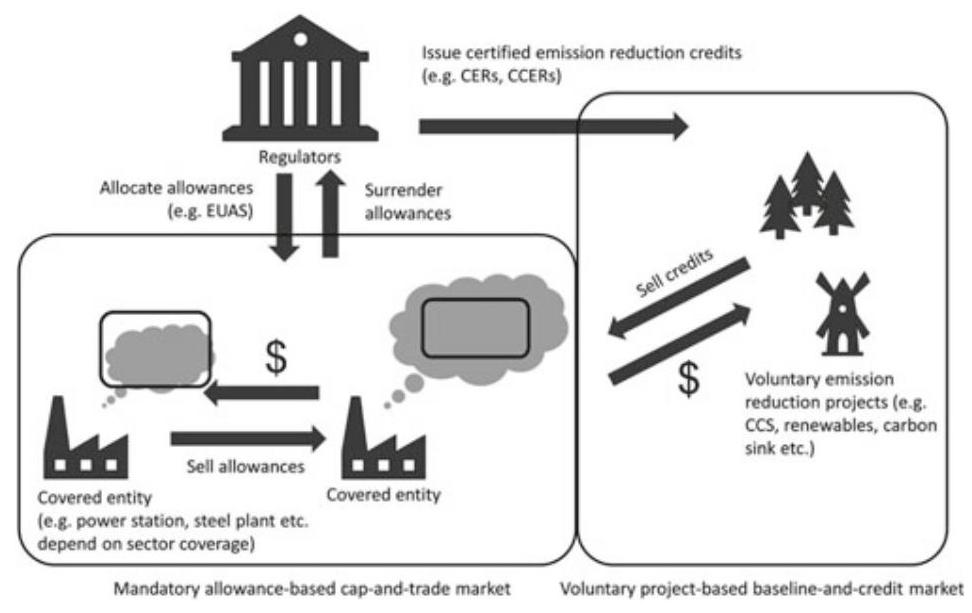
Fig. 1 Operation mechanism of ETS
图1 ETS的运行机制
${}^{3}$ For more on CCUS, see Chapters 3 and 4 of this book.
${}^{3}$ 有关碳捕获、利用与封存(CCUS)的更多信息,请参阅本书第3章和第4章。
${}^{4}$ The total amount of emission allowances could be offset by certified emission reduction if there is a flexible mechanism for compliance.
${}^{4}$ 如果存在灵活的履约机制,排放许可总量可以通过核证减排量来抵消。
${}^{5}$ For example, in EU-ETS, the power sector started off with ${95}\%$ free allocation of emission allowance in 2005 but gradually transitioned to 100% auctioning by 2013 (ICAP, 2019b). In China, the pilot ETS in Guangdong province required the power sector to purchase 3% of its emission allowances when the ETS started in 2013 (ICAP, 2019a).
${}^{5}$ 例如,在欧盟排放交易体系中,电力部门在2005年开始时${95}\%$ 免费分配排放许可,但到2013年逐渐过渡到100%拍卖(国际碳行动伙伴组织,2019b)。在中国广东省的试点排放交易体系中,电力部门在2013年排放交易体系启动时被要求购买其3%的排放许可(国际碳行动伙伴组织,2019a)。
Grandfathering is based on the enterprises’ historical emissions or emission intensities, while benchmarking is based on a benchmark emission intensity at the sector or sub-sector level. A baseline-and-credit approach depends on there being some source of voluntary or regulated demand for offset credits from emission reduction projects. The Kyoto Protocol Clean Development Mechanism (CDM) was an international baseline-and-credit mechanism that allowed emission reduction projects in developing countries, including China, to earn offset credits known as Certified Emission Reductions (CERs) that developed countries could purchase and use to partially fulfil their Kyoto Protocol emission reduction targets.
祖父条款法基于企业的历史排放量或排放强度,而基准法则基于行业或子行业层面的基准排放强度。基准与信用方法取决于是否存在对减排项目产生的抵消信用的自愿或监管需求来源。《京都议定书》清洁发展机制(CDM)是一种国际基准与信用机制,它允许包括中国在内的发展中国家的减排项目获得被称为核证减排量(CERs)的抵消信用,发达国家可以购买这些信用并用于部分履行其《京都议定书》减排目标。
2 Section 2
2 第2节
2.1 Current Designs and Operations of ETS Pilots in China
<### 2.1 中国碳排放权交易试点的当前设计与运行情况
China started pilot emissions trading schemes in 2013, and the first seven pilot schemes (Beijing, Shanghai, Shenzhen, Tianjin, Chongqing, Hubei and Guang-dong) have further developed their ETSs by expanding coverage, refining their allocation mechanisms, and introducing derivative products in the past few years. Many other provinces which were not included in the first seven pilot markets (such as Jiangsu, Xinjiang, Zhejiang provinces) have been interested in establishing their own schemes, and Fujian launched its own ETS in late 2016. By the end of April 2018, 222 MtCO2 equivalents of allowances had been traded in the primary and secondary ETS markets in China, with a value of RMB 5 billion (circa. US$ 725 m) (World Bank Group, 2019).
中国于2013年启动了碳排放权交易试点,在过去几年里,最初的七个试点方案(北京、上海、深圳、天津、重庆、湖北和广东)通过扩大覆盖范围、完善分配机制以及引入衍生品进一步发展了其碳排放权交易体系。许多未被纳入最初七个试点市场的其他省份(如江苏、新疆、浙江省)也有意建立自己的方案,福建于2016年末启动了自己的碳排放权交易体系。截至2018年4月底,中国碳排放权交易一级和二级市场已交易了2.22亿吨二氧化碳当量的配额,价值50亿元人民币(约合7.25亿美元)(世界银行集团,2019年)。
Most ETSs in China only cover ${\mathrm{{CO}}}_{2}$ emissions, apart from Chongqing, which covers six GHGs (see Table 1). All Chinese pilot ETSs cover both direct and indirect emissions. Covered emission sources in these pilots are defined as enterprises, rather than installations or facilities as in the EU-ETS (ICAP, 2019a). As discussed in the previous chapter, China is a country with significant regional diversities. Indeed, each province or city that participates in a pilot ETS has a different industrial structure and economic growth outlook, resulting in each pilot ETS having different sectoral coverage in order to achieve its target without adversely affecting economic growth projections (EYGM, 2014).
中国的大多数碳排放权交易体系仅涵盖${\mathrm{{CO}}}_{2}$排放,重庆除外,重庆涵盖六种温室气体(见表1)。中国所有试点碳排放权交易体系均涵盖直接和间接排放。这些试点中的覆盖排放源被定义为企业,而非欧盟碳排放权交易体系中的装置或设施(国际碳行动伙伴组织,2019a)。如前一章所述,中国是一个区域差异显著的国家。事实上,参与试点碳排放权交易体系的每个省份或城市都有不同的产业结构和经济增长前景,因此每个试点碳排放权交易体系都有不同的行业覆盖范围,以便在不负面影响经济增长预测的情况下实现其目标(安永全球,2014年)。
For example, Beijing, Shanghai and Shenzhen are commercial centers along the coast with relatively high GDP per capita, and carbon emissions from the building sector account for a significant proportion of emissions in these provinces or cities, therefore the sector is included in these pilots (Duan et al., 2014). Conversely, Hubei and Chongqing are located in central China with a relatively lower GDP per capita but higher GDP growth rates. Accordingly, these pilot ETSs are more focused on heavy industrial sectors. Major emitting sectors such as power and heat, petrochemicals and manufacturing are covered in all pilots.
例如,北京、上海和深圳是沿海商业中心,人均GDP相对较高,建筑部门的碳排放占这些省份或城市排放的很大比例,因此该部门被纳入这些试点(段等人,2014年)。相反,湖北和重庆位于中国中部,人均GDP相对较低,但GDP增长率较高。因此,这些试点碳排放权交易体系更侧重于重工业部门。所有试点均涵盖电力和热力、石化和制造业等主要排放部门。
Table 1 Sectoral coverage of pilot ETSs (2018)
<表1 试点碳排放权交易体系的行业覆盖范围(2018年)
| Pilot ETS | Estimated coverage (%) | Sectors | Inclusion threshold | Number of firms | Allocation methods for steel sector |
| Beijing | 45 | Power and heat, petrochemicals, manufacturing (including iron and steel), building, public transportation and service | Total emissions: ${5000}{\mathrm{{tCO}}}_{2}$ /year | 903 (5) | Grandfathering |
| Chongqing | 50 | Power and heat, electrolytic aluminum, ferroalloys, calcium carbide, cement, caustic soda, and iron and steel | Total emissions: 20,000 ${\mathrm{{tCO}}}_{2}$ /year | 230 (n/a) | Grandfathering |
| Fujian | 60 | Power, petrochemical, chemical, building materials, iron and steel, nonferrous metals, paper, aviation, and ceramics | Energy consumption: 10,000 tce/year | 255 (26) | Grandfathering |
| Guangdong | 60 | Power and heat, petrochemicals, manufacturing (including iron and steel), transportation (including aviation) | Total emissions: 20,000 ${\mathrm{{tCO}}}_{2}$ /year | 249 (53) | Primary process: benchmarking; Secondary process and others: grandfathering |
(continued)
(续)
Table 1 (continued)
<表1(续)
| Pilot ETS | Estimated coverage (%) | Sectors | Inclusion threshold | Number of firms | Allocation methods for steel sector |
| Hubei | 45 | Power and heat, petrochemicals, chemicals, manufacturing (including iron and steel, nonferrous metals, cement etc.), food and beverage | Energy consumption: 10,000 tce/year (in any year between 2014 and 2016) 60,000 tce/year (in any year between 2010 and 2011) | 344 (23) | Grandfathering |
| Shanghai | 57 | Power and heat, petrochemicals, chemical, iron and steel, nonferrous metals, building, transportation (including aviation, shipping etc.) and commerce | Total emissions: 10,000 tCO2/year 100,000 | 289 (4) | Grandfathering |
| Shenzhen | 40 | Power and heat, water-supply, manufacturing (including iron and steel), building and public transportation | Total emissions: ${3000}{\mathrm{{tCO}}}_{2}/$ year | 794 (2) | Grandfathering |
| Tianjin | 55 | Power and heat, petrochemicals, chemicals, iron and steel, oil and gas production | Total emissions: 20,000 t ${\mathrm{{CO}}}_{2}$ /year | 107 (29) | Grandfathering |
Source ICAP (2019b)
来源:国际碳行动伙伴组织(2019b)
Table 1 summarizes the sectoral coverage of the eight pilot ETSs in China.
表1总结了中国八个试点碳排放权交易体系的行业覆盖范围。
The iron and steel sector is covered by all pilot ETSs. Allowances are mainly allocated for free to enterprises in the sector, although auctioning may take place where it is considered appropriate by the ETS authorities of Shenzhen, Beijing, Guangdong and Fujian for the purpose of adjusting the market price (Pang & Duan, 2016). All pilots have adopted the historical emissions “grandfathering” method to allocate allowances to covered iron and steel enterprises, except for the Guangdong pilot ETS, which has used a benchmarking method for iron and steel enterprises equipped with primary process steel making. (Primary process (or primary route) refers to basic oxygen steel making process that uses).
钢铁行业被所有试点碳排放权交易体系覆盖。配额主要免费分配给该行业的企业,不过深圳、北京、广东和福建的碳排放权交易主管部门认为适当时,可能会进行拍卖以调整市场价格(庞和段,2016年)。除广东试点碳排放权交易体系外,所有试点均采用历史排放“祖父法”向覆盖的钢铁企业分配配额,广东试点碳排放权交易体系对配备初炼钢工艺的钢铁企业采用了基准法。(初炼钢工艺(或初炼路线)指使用的碱性氧气炼钢工艺)。
Building on the successful experience of regional ETS pilots since 2013, China’s National Development and Reform Commission (NDRC) announced the official launch of a national ETS in December 2017, aiming to contribute to the effective control and gradual reduction of carbon emissions in China and the achievement of low carbon and green development. The national ETS regulates about 1,700 enterprises from the power sector, which emit over 26,000 tons of ${\mathrm{{CO}}}_{2}$ per year or consume over 10,000 tons of standard coal equivalent (tce) per year (ICAP, 2019b). More than 3 GtCO2e are covered in the initial phase, which accounts for approximately 30% of China’s national emissions.
基于2013年以来区域碳排放权交易试点的成功经验,中国国家发展和改革委员会(国家发改委)于2017年12月宣布正式启动全国碳排放权交易体系,旨在助力中国有效控制并逐步减少碳排放,实现低碳绿色发展。全国碳排放权交易体系监管约1700家电力行业企业,这些企业每年排放超过2.6万吨${\mathrm{{CO}}}_{2}$或每年消耗超过1万吨标准煤当量(tce)(国际碳行动伙伴组织,2019b)。初始阶段覆盖超过30亿吨二氧化碳当量,约占中国全国排放量的30%。
China’s national carbon market is planned to start operation in 2020, although there is a delay due to the climate change department being moved from NDRC to the Ministry of Ecology and Environment (MEE) in 2018 (Zaman & Yang, 2019). The provisions for the launch and gradual development of the national ETS are laid out in the Work Plan for Construction of the National Emissions Trading System (Power Sector). The Work Plan was approved by the State Council in late 2017 (NDRC, 2017a). A phased transition in the Chinese ETS pilots is foreseen by the Work Plan. In the short term, the existing regional ETS pilots are expected to operate in parallel with the national carbon market, covering existing power and non-power sectors. Over the medium to long term, however, they are expected to be integrated into the national carbon market, once it is fully operational.
中国全国碳市场计划于2020年开始运行,不过由于气候变化部门于2018年从国家发改委转至生态环境部(生态环境部),出现了延迟(扎曼和杨,2019年)。《全国碳排放权交易体系(电力行业)建设工作方案》中规定了全国碳排放权交易体系启动及逐步发展的相关内容。该工作方案于2017年末获国务院批准(国家发改委,2017a)。该工作方案预计中国碳排放权交易试点将分阶段过渡。短期内,现有区域碳排放权交易试点预计将与全国碳市场并行运行,覆盖现有电力和非电力行业。然而,从中长期来看,一旦全国碳市场全面运行,预计它们将被纳入全国碳市场。
The power sector generally has higher quality of emissions data and it is therefore the first sector to be included in the national ETS. On ${15}^{\text{ th }}$ December 2017, the NDRC issued a notice (NDRC, 2017b) requiring reporting and verification of 2016 and 2017 carbon emissions data, as well as the development plans for future monitoring, reporting and verification (MRV) work in eight industrial sectors. These eight industrial sectors are: petrochemicals, chemicals, building materials, iron/steel, nonferrous metals, papermaking, electricity, and aviation. The coverage of these industrial sectors in the notice signals that the long-run plan is to integrate these sectors into the national ETS or another carbon pricing or regulation scheme.
电力行业的排放数据质量通常较高,因此是首个被纳入全国碳排放交易体系的行业。2017年${15}^{\text{ th }}$12月,国家发展和改革委员会发布通知(国家发展和改革委员会,2017b),要求报告和核查2016年和2017年的碳排放数据,以及八个工业行业未来监测、报告和核查(MRV)工作的发展计划。这八个工业行业分别是:石化、化工、建材、钢铁、有色金属、造纸、电力和航空。通知中对这些工业行业的覆盖表明,长期计划是将这些行业纳入全国碳排放交易体系或其他碳定价或监管计划。
Domestic project-based offset credits are allowed in China’s pilot ETSs, meaning that emissions can be reduced by sources that are not covered by the schemes and that are not located in the jurisdictions. The use of offsets is limited to $1\%$ of annual allowances in the Shanghai ETS pilot, 5% (Beijing and Fujian ETS pilots), 8% (Chongqing ETS pilot) and 10% (Guangdong, Hubei, Shenzhen and Tianjin ETS pilots) (ICAP, 2019b).
中国的试点碳排放交易体系允许使用国内基于项目的抵消信用,这意味着排放可以由未被该计划覆盖且不在相关辖区内的来源减少。抵消信用的使用在上海碳排放交易试点中限制为年度配额的$1\%$,在北京和福建碳排放交易试点中为5%,在重庆碳排放交易试点中为8%,在广东、湖北、深圳和天津碳排放交易试点中为10%(国际碳行动伙伴组织,2019b)。
Table 2 below provides an overview on how the use of offset credits is regulated in the eight regional ETS pilots. None of these regional ETS pilots allows the use of international offsets from outside China. To avoid potential carbon leakage ${}^{6}$ Hubei ETS, with a relatively low abatement cost, requires that all CCERs must be generated from projects within Hubei province, while Guangdong ETS requires at least 70% of own-produced CCERs for the same reason (IETA, 2014, ICAP, 2019b). With concerns about the impact of CCERs on the ETS pilot markets and an upgrade of the current CCER system, the CCER project registration process was suspended since March 2017 (NDRC, 2017a).
下表2概述了八个区域碳排放交易试点中抵消信用的使用是如何受到监管的。这些区域碳排放交易试点均不允许使用来自中国境外的国际抵消信用。为避免潜在的碳泄漏,${}^{6}$减排成本相对较低的湖北碳排放交易体系要求所有中国核证自愿减排量必须来自湖北省内的项目,出于同样的原因,广东碳排放交易体系要求至少70%的自产中国核证自愿减排量(国际排放贸易协会,2014;国际碳行动伙伴组织,2019b)。由于担心中国核证自愿减排量对碳排放交易试点市场的影响以及当前中国核证自愿减排量体系的升级,自2017年3月起中国核证自愿减排量项目注册程序暂停(国家发展和改革委员会,2017a)。
Table 2 Offsets regulations in China’s pilot ETSs
表2中国试点碳排放交易体系中的抵消信用监管规定
| Pilot ETS | Eligible type of offset credits | Offsets limit (% of annual allowances) | Other requirements |
| Shenzhen | CCERs | 10 | Credits from hydro projects not allowed |
| Shanghai | CCERs | 1 | Credits from hydro projects not allowed |
| Beijing | CCERs | 5 | n/a |
| Guangdong | CCERs and Pu Hui Certified emission Reduction (PHCER) | 1.5 million offsets | At least 70% from projects in Guangdong province Credits from hydro projects not allowed |
| Tianjin | CCERs | 10 | Credits from hydro projects not allowed |
| Hubei | CCERs | 10 | Credits have to be generated from rural biogas and forestry projects located in poor areas of Hubei |
| Chongqing | CCERs | 8 | Credits from hydro projects not allowed |
| Fujian | CCERs and Fujian Forestry Certified Emission Reduction (FFCER) | 10 | n/a |
At the 13th National People’s Congress (NPC) in March 2018, the mission of combating climate change and reducing emissions was transferred from the NDRC to the MEE, which is likely to promote synergies between the development of a national carbon market and efforts to reduce air pollution (Slater et al., 2018). The Climate Change Department within the Ministry of Ecology and Environment will operate the national carbon market jointly with provincial governments. In April 2019, MEE started a consultation on the Interim Regulations for the Administration of Carbon Emission Permit Trading (MEE, 2019). The Interim Regulations set the rules for allowance allocation and trading in the regions, and mandate local governments to collect emissions data and regulate the emission trading market.
2018年3月召开的第十三届全国人民代表大会上,应对气候变化和减排的任务从国家发展和改革委员会转至生态环境部,这可能会促进全国碳市场发展与空气污染治理努力之间的协同效应(斯莱特等人,2018)。生态环境部内的气候变化司将与省级政府共同运营全国碳市场。2019年4月,生态环境部启动了关于《碳排放权交易管理暂行条例》的征求意见(生态环境部,2019)。该暂行条例规定了各地区配额分配和交易的规则,并要求地方政府收集排放数据并监管排放交易市场。
3 Section 3
3 第3节
3.1 Options for China’s ETS to Incentivize Steel Sector CCS
3.1 中国碳排放交易体系激励钢铁行业碳捕集与封存的方案
The purpose of an ETS is to put a price on emissions and so incentivize emission reductions in a cost-effective way. It is therefore relevant, albeit tentative, to consider how China’s national ETS could be used to incentivize CCUS in the steel sector. In this section we discuss three tentative approaches to this: (1) allowing ${\mathrm{{CO}}}_{2}$ stored through CCUS to be regarded as “not or low emitted” for the purposes of ETS compliance; (2) allowing offsets from iron/steel CCUS projects to be used for compliance in China’s ETS; and (3) incentivizing CCUS with finance from auctioning of ETS allowances or directly awarding allowances for steel plants with CCUS.
碳排放交易体系的目的是为排放定价,从而以具有成本效益的方式激励减排。因此,考虑如何利用中国的全国碳排放交易体系激励钢铁行业的碳捕集、利用与封存(CCUS)是有意义的,尽管只是初步探讨。在本节中,我们讨论三种初步方法:(1)在碳排放交易体系合规方面,允许将通过碳捕集、利用与封存(CCUS)储存的${\mathrm{{CO}}}_{2}$视为“未排放或低排放”;(2)允许钢铁行业碳捕集、利用与封存(CCUS)项目产生的抵消量用于中国碳排放交易体系的合规;(3)通过拍卖碳排放交易体系配额所得资金激励碳捕集、利用与封存(CCUS),或直接向采用碳捕集、利用与封存(CCUS)技术的钢铁厂发放配额。
6 “Carbon leakage refers to domestic carbon emissions that are displaced by relatively cheaper imported products, mainly from countries or regions without carbon constraints, rather than reduced as anticipated because of the mitigation of unilateral regional climate change” - WANG, X., TENG, F., WANG, G., ZHOU, S. & CAI, B. 2018. Carbon Leakage Scrutiny in ETS and non-ETS Industrial Sectors in China. Resources, Conservation and Recycling, 129, 424-431.
6 “碳泄漏是指国内碳排放被相对便宜的进口产品所取代,这些产品主要来自没有碳约束的国家或地区,而不是因为单方面区域气候变化缓解而如预期那样减少”——王X、滕F、王G、周S、蔡B。2018年。中国碳排放交易体系和非碳排放交易体系工业部门的碳泄漏审查。《资源、保护与回收》,129,424 - 431。
Regarding CO2 Stored via CCS as “Not or Low Emitted”
将通过碳捕获与封存(CCS)储存的二氧化碳视为“低排放或无排放”
One option to incentivize CCUS implementation in the steel sector in China would be to include emissions from the sector within the scope of the national ETS, while simultaneously allowing ${\mathrm{{CO}}}_{2}$ stored through CCUS to be regarded as ’not or low emitted’ for the purposes of ETS compliance. Within the option, regulators would need to consider the amendment of existing legislation, including potential changes in its coverage, allowance allocation method and MRV system, and introduce new rules concerning the capture and geological storage of carbon dioxide.
激励中国钢铁行业实施碳捕获、利用与封存(CCUS)的一种选择是,将该行业的排放纳入国家碳排放交易体系(ETS)的范围,同时允许为符合ETS规定,将通过CCUS储存的${\mathrm{{CO}}}_{2}$视为“低排放或无排放”。在该选项下,监管机构需要考虑修订现行法律,包括其覆盖范围、配额分配方法和监测、报告与核查(MRV)系统的潜在变化,并引入有关二氧化碳捕获和地质封存的新规则。
ETS Coverage
排放交易体系覆盖范围
This option depends on the iron/steel sector being covered by the ETS. As previously discussed, the pilot ETSs in China all include the iron/steel sector, but the national ETS does not. Therefore, new legislation would be required to change the scope of the national ETS. This would need to specify which sources of emissions in iron and steel plants are covered within each entity’s defined scope. In the EU-ETS, sources are defined in terms of activities and thresholds (where the intention is not to include 100% of emissions from an activity).
此选项取决于钢铁行业是否被纳入排放交易体系。如前所述,中国的试点排放交易体系均涵盖钢铁行业,但全国性排放交易体系并未涵盖。因此,需要新的立法来改变全国性排放交易体系的范围。这需要明确每个实体定义范围内钢铁厂的哪些排放源被涵盖。在欧盟排放交易体系中,排放源是根据活动和阈值来定义的(目的并非涵盖一项活动的100%排放)。
For example, all coke making, sintering and palletization plants are included, regardless of capacity; whereas production of pig iron or steel is included where production output is over 2.5t/day, and processing is included where combustion units over 20MWth input capacity are operated (European Commission, 2003). This leads to approximately ${75}\%$ of the sector’s emissions being covered in the EU-ETS (Dechezleprêtre et al., 2018). In terms of covered gases, it is likely that only carbon dioxide emissions from the iron/steel sector would be covered, in accordance with the coverage for the power sector in the national ETS. This would not leave a significant amount of GHG emissions unregulated, as relatively small quantities of other GHGs are emitted from iron/steel production (principally small amounts of methane and nitrous oxide from the combustion of coal) (Beer et al., 2003).
例如,所有的炼焦、烧结和造块厂均被纳入,无论其产能如何;而生铁或钢铁生产,当产量超过2.5吨/天时被纳入,加工环节,当输入容量超过20兆瓦热的燃烧装置运行时被纳入(欧盟委员会,2003年)。这使得欧盟排放交易体系涵盖了该行业约${75}\%$的排放(德谢兹勒普雷特尔等人,2018年)。就涵盖的气体而言,根据全国性排放交易体系中电力行业的覆盖范围,可能仅涵盖钢铁行业的二氧化碳排放。这不会导致大量温室气体排放不受监管,因为钢铁生产排放的其他温室气体相对较少(主要是煤炭燃烧产生的少量甲烷和氧化亚氮)(比尔等人,2003年)。
Iron and Steel GHG Accounting
钢铁行业温室气体核算
GHG emissions from an enterprise are conventionally divided into three scopes. Scope 1 refers to direct emissions from owned or controlled sources while Scope 2 refers to indirect emissions from the generation of purchased energy. Scope 3 includes all other indirect emissions (not included in scope 2) that occur in the supply chain of the reporting enterprise, both upstream and downstream. In the EU-ETS, covered entities are liable only for their Scope 1 emissions. In China, however, the existing Guidelines for Accounting and Reporting Greenhouse Gas Emissions: Iron and Steel ProductionEnterprises in China (NDRC, 2013a) require information on both direct emissions (Scope 1) from combustion of fossil fuel and consumption of solvent flux, carbonaceous materials and electrodes, and indirect emissions (Scope 2) from net purchased power and heat. Further details on the current accounting method for GHG emissions in the iron and steel sector in China can be found in Appendix 1.
企业的温室气体排放通常分为三个范围。范围1是指来自自有或控制源的直接排放,而范围2是指购买能源产生的间接排放。范围3包括报告企业供应链上下游发生的所有其他间接排放(不包括在范围2中)。在欧盟排放交易体系中,纳入的实体仅对其范围1的排放负责。然而,在中国,现有的《中国钢铁生产企业温室气体排放核算方法与报告指南》(国家发展和改革委员会,2013年a)要求提供化石燃料燃烧以及溶剂助熔剂、含碳材料和电极消耗产生的直接排放(范围1),以及净购买电力和热量产生的间接排放(范围2)的信息。中国钢铁行业当前温室气体排放核算方法的更多详细信息见附录1。
Allowance Allocation
配额分配
As previously observed, China’s ETS pilots have allocated free allowances to the iron and steel sector based on a grandfathering (historical data) approach, rather than benchmarking (based on activities) (see Table 1). A generic calculation of the allowances allocated to an iron and steel enterprise in China’s ETS pilots can be given as Formula 1 below:
如前所述,中国碳排放权交易试点基于祖父原则(历史数据)而非基准法(基于活动)向钢铁行业分配免费配额(见表1)。中国碳排放权交易试点中分配给钢铁企业的配额的一般计算方法如下式1所示:
$$ A = B \times {F}_{m} \times Q \tag{1} $$where.
其中:
$A$ Total allocated allowances to covered iron and steel entity.
$A$ 分配给受覆盖钢铁实体的总配额。
$B$ Historical emissions or emissions intensity.
$B$ 历史排放量或排放强度。
${F}_{m}$ Emission reduction factor.
${F}_{m}$ 减排因子。
$Q$ Crude steel production.
$Q$ 粗钢产量。
Although benchmarking is more conducive to encouraging advanced production processes, it is relatively difficult to determine suitable benchmarks for the iron and steel sector, due to its highly diverse product portfolio and complex production processes, as well as the lack of adequate emissions data. Nevertheless, after lessons learned from the initial two phases, the EU-ETS has switched its allocation method for industry and heating sectors in the third phase (2013-2020) from grandfathering to benchmarking (European Commission, 2015a).
尽管基准法更有利于鼓励采用先进生产工艺,但由于钢铁行业产品种类繁多、生产流程复杂,且缺乏足够的排放数据,因此为该行业确定合适的基准相对困难。尽管如此,在吸取前两个阶段的经验教训后,欧盟碳排放交易体系在第三阶段(2013-2020年)将其对工业和供热部门的分配方法从祖父原则改为基准法(欧盟委员会,2015a)。
CCS Recognition
碳捕获与封存的认可
Meanwhile, CCUS needs to be recognized legally so that emissions captured, transported and stored would not be treated as emitted. This occurred in a phased manner in the EU-ETS. From the start of Phase II in 2008, Member States had the option of including CCUS in the EU-ETS, subject to the Commission’s approval. Under the revised EU-ETS Directive 2009/29/EC, CCUS was given fuller recognition within the scheme, which took effect from Phase III in 2013 (European Commission, 2009a). The most outstanding element of the EU regulation on CCUS was a separate Directive for the geological storage of ${\mathrm{{CO}}}_{2}$ , which regulates the risks of ${\mathrm{{CO}}}_{2}$ storage (European Commission,2009b) and allows each Member State to formulate its regulatory approach to comply with the EU requirement (European Commission, 2011). In addition, each Member State could formulate its own policies for incentivizing CCUS demonstration projects, subject to State Aid approval by the European Commission.
与此同时,碳捕获、利用与封存(CCUS)需要获得法律认可,以便捕获、运输和储存的排放不被视为已排放。这在欧盟排放交易体系(EU-ETS)中是分阶段进行的。从2008年第二阶段开始,成员国可以选择将CCUS纳入欧盟排放交易体系,但需经委员会批准。根据修订后的欧盟排放交易体系指令2009/29/EC,CCUS在该计划中得到了更充分的认可,该指令于2013年第三阶段生效(欧盟委员会,2009a)。欧盟关于CCUS的法规中最突出的部分是一项关于${\mathrm{{CO}}}_{2}$地质储存的单独指令,该指令对${\mathrm{{CO}}}_{2}$储存的风险进行监管(欧盟委员会,2009b),并允许每个成员国制定自己的监管方法以符合欧盟要求(欧盟委员会,2011)。此外,每个成员国可以制定自己的政策来激励CCUS示范项目,但需经欧盟委员会的国家援助批准。
In terms of the impact on CCUS financing, the option of allowing ${\mathrm{{CO}}}_{2}$ stored via CCUS to be regarded as ’not or low emitted’ for the purposes of ETS compliance would boost confidence for industries to demonstrate CCUS, but the actual financial support provided would be very limited. Given that average price expectations in the national ETS are RMB 54/ton (US$7.7/ton) in 2020 and RMB 98/ton (US$ 14/ton) in 2025 (Slater et al.,2018), and the cost of ${\mathrm{{CO}}}_{2}$ avoidance for a 0.5 million ton/year capacity ${\mathrm{{CO}}}_{2}$ capture project with pipeline transport and storage in an offshore saline formation is estimated at RMB 443/tCO2 (US$ ${63}/{\mathrm{{tCO}}}_{2}$ ) (Liang et al.,2019), this option would only contribute a small percentage of the required incentives to demonstrate CCUS. This finding is similar to the recommendation of a study by ENGO Network (2013) which suggested that an ETS could only form part of a financing package for CCUS. However, the cost estimate was based on offshore saline formation storage: if CCUS in China was deployed with onshore enhanced oil recovery (EOR) where the abatement cost could be less than US$20 per ton ${\mathrm{{CO}}}_{2}$ avoided (NCEPU,2019), the carbon price in the ETS could provide a more substantial part of the incentives required to enable CCUS, although still not the entire amount.
就对CCUS融资的影响而言,在排放交易体系合规方面,允许通过CCUS储存的${\mathrm{{CO}}}_{2}$被视为“未排放或低排放”的选择将增强行业对示范CCUS的信心,但实际提供的财政支持将非常有限。鉴于2020年国家排放交易体系的平均价格预期为54元/吨(7.7美元/吨),2025年为98元/吨(14美元/吨)(斯莱特等人,2018),以及一个年处理能力为50万吨的${\mathrm{{CO}}}_{2}$捕获项目,采用管道运输并储存在近海盐层中的${\mathrm{{CO}}}_{2}$减排成本估计为443元/tCO2(${63}/{\mathrm{{tCO}}}_{2}$美元)(梁等人,2019),此选项仅能提供所需激励措施的一小部分来示范CCUS。这一发现与ENGO网络(2013年)的一项研究建议相似,该研究表明排放交易体系只能作为CCUS融资方案的一部分。然而,成本估计是基于近海盐层储存:如果中国的CCUS与陆上强化采油(EOR)一起部署,减排成本可能低于每吨${\mathrm{{CO}}}_{2}$避免排放20美元(华北电力大学,2019),排放交易体系中的碳价格可以提供实现CCUS所需激励措施的更大部分,尽管仍不是全部。
3.3 Allowing Offsets from Steel CCUS Projects in China’s ETS
3.3 在中国碳排放交易体系中允许钢铁行业碳捕集利用与封存项目产生抵消信用额
Allowing CCUS to be included in project-based baseline-and-credit emissions trading is a second option for incentivizing iron/steel CCUS development in China. This would involve allowing CCUS projects to generate offsets which could be sold to participants in the ETS, who would be allowed to use them to meet their compliance obligations.
允许碳捕集利用与封存纳入基于项目的基准线与信用额排放交易体系,是激励中国钢铁行业碳捕集利用与封存发展的第二个选项。这将涉及允许碳捕集利用与封存项目产生抵消信用额,这些信用额可出售给碳排放交易体系的参与者,参与者可使用它们来履行合规义务。
So far none of the eight regional ETS pilots have allowed emission reduction offset credits from CCUS to be eligible for compliance. On ${28}^{\text{ th }}$ December 2018, the NDRC, together with eight other government institutions including the MEE, issued the “Action plan on the establishment of a market-oriented and diversified ecological protection compensation mechanism” (NDRC, 2018). The Action Plan mentions the review and improvement of the CCER offset scheme and specifically prioritizes the use of forestry carbon sink projects as offsets for the national ETS, but CCUS is not explicitly discussed in the document.
到目前为止,八个区域碳排放交易体系试点中没有一个允许碳捕集利用与封存项目的减排抵消信用额用于合规。在2018年${28}^{\text{ th }}$月,国家发展和改革委员会与包括生态环境部在内的其他八个政府机构发布了《建立市场化、多元化生态保护补偿机制行动计划》(国家发展和改革委员会,2018年)。该行动计划提到了对国家核证自愿减排量抵消机制的审查和改进,并特别优先考虑将林业碳汇项目用作国家碳排放交易体系的抵消项目,但该文件中未明确讨论碳捕集利用与封存。
In terms of allowing CCUS projects in the iron/steel sector to generate offset credits, two options are available: either domestic legislation to allow such projects to generate credits that would be unique to China’s national ETS, or making use of the international legal framework for recognizing emission reductions in developing countries under the Kyoto Protocol Clean Development Mechanism (CDM). As previously discussed, the CDM allows emission reduction projects in developing countries to generate internationally-recognized credits known as Certified Emission Reductions (CERs) (Dixon et al., 2013). In December 2011, at the meeting of the UNFCCC in Durban, South Africa, CCS was formally included in the list of project activities that may be eligible as CDM project activities (Brander & Ascui, 2018). However, at the present time, no carbon accounting methodologies for CCS have been put forward for approval under the 2011 agreement. Until such a methodology, applicable to CCUS in the iron/steel sector in China, is put forward and approved under the CDM modalities and procedures, it will not be possible to generate internationally recognized CERs from such a project. Therefore, the option of domestic legislation allowing projects to generate a China-specific offset credit is currently considered more feasible.
在允许钢铁行业的碳捕集利用与封存项目产生抵消信用额方面,有两个选项:要么通过国内立法允许此类项目产生仅适用于中国国家碳排放交易体系的信用额,要么利用《京都议定书》清洁发展机制(CDM)下认可发展中国家减排量的国际法律框架。如前所述,清洁发展机制允许发展中国家的减排项目产生国际认可的信用额,即核证减排量(CERs)(Dixon等人,2013年)。2011年12月,在南非德班举行的《联合国气候变化框架公约》会议上,碳捕集与封存正式被列入可能符合清洁发展机制项目活动资格的项目活动清单(Brander & Ascui,2018年)。然而,目前尚未根据2011年协议提出用于碳捕集与封存的碳核算方法以供批准。在适用于中国钢铁行业碳捕集利用与封存的方法根据清洁发展机制的模式和程序提出并获批之前,此类项目将无法产生国际认可的核证减排量。因此,目前认为通过国内立法允许项目产生中国特定抵消信用额的选项更为可行。
Such legislation would need to establish an administrative procedure for approving a GHG accounting methodology for CCUS projects in China. For project-based GHG accounting, emission reductions are quantified by comparing measured project emissions against a forward-looking, counter-factual baseline scenario or reference level (World Resources Institute and World Business Council for Sustainable Development, 2005). In addition, any increase in emissions elsewhere that is measurable and attributable to the project, yet not within the project boundary, is denoted ’leakage’ and also deducted from the calculated emission reductions (Brander & Ascui, 2018). Therefore, a general formula for project-based baseline-and-credit accounting is shown in Formula 2 below:
此类立法需要建立一个行政程序,以批准中国碳捕集利用与封存项目的温室气体核算方法。对于基于项目的温室气体核算,通过将测量的项目排放量与前瞻性的、反事实的基准情景或参考水平进行比较来量化减排量(世界资源研究所和世界可持续发展工商理事会,2005年)。此外,在项目边界之外可测量且可归因于该项目的其他任何排放增加,被称为“泄漏”,也应从计算的减排量中扣除(Brander & Ascui,2018年)。因此,基于项目的基准线与信用额核算的一般公式如下所示:
$$ {ERy} = {BEy} - {PEy} - {LEy} \tag{2} $$where:
其中:
ERy Emission reductions in year $\mathrm{y}\left( {\mathrm{{tCO}}}_{2}\right)$ .
ERy $\mathrm{y}\left( {\mathrm{{tCO}}}_{2}\right)$年的减排量。
${BEy}$ Baseline emissions in year y (tCO2), representing emissions from iron/steel enterprise that would have entered atmosphere if not for CCUS project
${BEy}$ y年的基准排放量(tCO2),代表若没有碳捕集利用与封存项目,钢铁企业本应排入大气的排放量
PEy Project emissions in year $\mathrm{y}\left( {\mathrm{{tCO}}}_{2}\right)$ , representing actual GHG emissions from iron/steel enterprise after implementation of CCUS project, including carbon capture, transport pipelines, and storage sites.
PEy $\mathrm{y}\left( {\mathrm{{tCO}}}_{2}\right)$年的项目排放量,代表实施碳捕集利用与封存项目后钢铁企业的实际温室气体排放量,包括碳捕获、运输管道和储存场地。
LEy Leakage emissions in year y (tCO2).
LEy y年的泄漏排放量(tCO2)。
An important challenge for project-based GHG accounting is identifying and characterizing the baseline scenario and estimating the baseline emissions (BEy in Formula 2). A baseline is a hypothetical situation that represents the conditions most likely to occur in the absence of the CCUS project. The baseline should cover all emissions within the project boundary. For an iron/steel CCUS project, establishing a baseline for each component is suggested (Brander & Ascui, 2018). Existing actual or historical emissions would be a suitable baseline approach for a CCUS project that involves the addition of CCUS to an existing iron/steel plant. The baseline for retrofit CCUS project would involve the continued operation of the existing ${\mathrm{{CO}}}_{2}$ source facility, but without CCUS, such that produced ${\mathrm{{CO}}}_{2}$ is vented to the atmosphere. For a new build CCUS project, the baseline could correspond with the common practice in the area and the most economic option available, or an emissions performance standard that best represents project circumstances (McCormck, 2012).
基于项目的温室气体核算面临的一个重要挑战是识别和描述基准情景并估算基准排放量(公式2中的BEy)。基准是一种假设情况,代表在没有碳捕集利用与封存项目时最可能出现的条件。基准应涵盖项目边界内的所有排放。对于钢铁碳捕集利用与封存项目,建议为每个组件建立基准(Brander & Ascui,2018年)。现有实际或历史排放量将是一个适用于将碳捕集利用与封存添加到现有钢铁厂的碳捕集利用与封存项目的基准方法。改造碳捕集利用与封存项目的基准将涉及现有${\mathrm{{CO}}}_{2}$源设施的持续运行,但不包括碳捕集利用与封存,以使产生的${\mathrm{{CO}}}_{2}$排放到大气中。对于新建碳捕集利用与封存项目,基准可以与该地区的常见做法和最经济的选项相对应,或者与最能代表项目情况的排放绩效标准相对应(McCormck,2012年)。
After a project is implemented, emissions need to be monitored and reported. Emissions from a full chain CCUS project would comprise all sources of emissions within the project boundary, which would include at a minimum: The installation where ${\mathrm{{CO}}}_{2}$ captured;
项目实施后,需要对排放进行监测和报告。全链条CCUS项目的排放将包括项目边界内的所有排放源,至少包括:${\mathrm{{CO}}}_{2}$被捕获的装置;
Any treatment facilities;
任何处理设施;
Transportation equipment;
运输设备;
Injection facilities; and.
注入设施;以及。
Subsurface components, including the storage site and potential sources of seepage, as well as the vertical and lateral limits of the geological storage site that are expected when the ${\mathrm{{CO}}}_{2}$ plume stabilizes over the long term.
地下组件,包括储存场地和潜在的渗漏源,以及${\mathrm{{CO}}}_{2}$羽流长期稳定时地质储存场地预期的垂直和横向范围。
Calculating project emissions involves measuring ${\mathrm{{CO}}}_{2}$ emitted during capture, compression, transportation, injection and storage (and recycling of ${\mathrm{{CO}}}_{2}$ if applicable) and deducting ${\mathrm{{CO}}}_{2}$ permanently stored by the project. Emissions generated from the additional energy required for capture (known as the ’energy penalty’) should be taken into consideration. Any seepage emissions $\left( {\mathrm{{CO}}}_{2}\right.$ that escapes from a geological reservoir into the ocean or atmosphere) should also be include in project emissions.
计算项目排放涉及测量捕获(如有适用,${\mathrm{{CO}}}_{2}$的回收)、压缩、运输、注入和储存过程中排放的${\mathrm{{CO}}}_{2}$,并扣除项目永久储存的${\mathrm{{CO}}}_{2}$。捕获所需额外能源产生的排放(称为“能源惩罚”)应予以考虑。从地质储层泄漏到海洋或大气中的任何渗漏排放$\left( {\mathrm{{CO}}}_{2}\right.$也应计入项目排放。
In terms of the impact on investment, the price of CCERs is generally lower than the price of allowances, so the financial impact of allowing iron and steel
就对投资的影响而言,CCER的价格通常低于配额价格,因此允许钢铁行业
CCUS projects to generate CCERs is less than under approach 1. The cost of monitoring, reporting and verification (MRV) of emission reductions at the project level is also generally higher than the equivalent costs under approach 1. There have not yet been any CCUS projects, anywhere in the world, financed solely through the CDM or similar offset mechanisms. Nevertheless, allowing CCUS projects to generate offset credits that can be used within China’s ETS is an option that could be considered if approach 1 is infeasible (for example, if it is decided that the iron/steel sector will not be covered by the national ETS, even in the next phase). While the revenue from offset credits would not be sufficient on its own to incentivize CCUS projects, it could boost confidence for investors in CCUS and help establish the MRV system for the iron and steel sector.
CCUS项目产生CCER的财务影响小于方法1。项目层面减排监测、报告和核查(MRV)的成本通常也高于方法1的等效成本。世界上任何地方都尚未有仅通过CDM或类似抵消机制融资的CCUS项目。然而,如果方法1不可行(例如,如果决定钢铁行业即使在下一阶段也不纳入国家ETS),允许CCUS项目产生可在中国ETS内使用的抵消信用是一个可以考虑的选项。虽然抵消信用的收入本身不足以激励CCUS项目,但它可以增强CCUS投资者的信心,并有助于建立钢铁行业的MRV系统。
3.4 Auctioning ETS Allowances for Iron/Steel Plants with CCUS
3.4 为采用碳捕集、利用与封存技术的钢铁厂拍卖排放交易体系配额
The third approach involves using the revenue generated by the auctioning of allowances to support CCUS development and demonstration in the iron/steel sector. The government could establish a funding pool to provide dedicated support for financing CCUS demonstration projects. There has been some experience of this already in China’s pilot ETSs. The Guangdong ETS has attempted to use approximately RMB 1 billion (US$140 million) in auctioning revenue to finance innovative low-carbon technologies, but the provincial government finance department has been reluctant to approve the expenditure. An alternative approach could be to directly award allowances (taken from the amount to be auctioned) to companies building CCUS projects. The latter method could be easier to implement as it would not require finance department approval, but it would expose the project developer to price risk as the value of their allowances could change over time. Under a direct funding approach, the government rather than the project developer would be exposed to price risk.
第三种方法是利用拍卖配额产生的收入,来支持钢铁行业的碳捕集、利用与封存技术的开发和示范项目。政府可以设立一个资金池,为碳捕集、利用与封存技术示范项目的融资提供专门支持。中国的碳排放权交易试点已经有了一些这方面的经验。广东碳排放权交易体系曾试图用约10亿元人民币(1.4亿美元)的拍卖收入,为创新型低碳技术融资,但省级政府财政部门一直不愿批准这笔支出。另一种方法可以是直接将配额(从待拍卖的配额数量中抽取)授予建设碳捕集、利用与封存技术项目的公司。后一种方法可能更容易实施,因为它不需要财政部门的批准,但项目开发商会面临价格风险,因为他们的配额价值可能会随时间变化。在直接资助的方法下,面临价格风险的将是政府而非项目开发商。
The closest international reference is the EU-ETS New Entrant Reserve (NER). In 2009, the European Commission (EC), European Investment Bank (EIB) and EU Member States agreed to set aside 300 million allowances for subsidizing CCUS and installations of innovative renewable energy technologies, hence the fund’s name ‘NER 300’ (European Commission, 2017). With carbon prices heading toward EUR 30/ton in 2008, it was hoped that up to EUR 9 billion would be raised. However, prices subsequently crashed, and it was not until late December 2012 that the European Commissioner for Climate Action Connie Hedegaard finally announced the outcome of the first NER300 funding round-but could only award EUR 1.2 billion, due to the drop in allowance price, to 23 innovative renewable energy projects across Europe. Not a single CCUS project was funded, and due to the long selection process, the CCUS projects that had applied for NER300 funding missed their most ideal timing to receive investment under legislation for Phase 4 (2020-2030) of the EU-ETS, which became effective in April 2018, at least 400 million allowances (called NER400) will be reserved from 2021 onwards to create an Innovation Fund for demonstration projects of renewable energy and environmentally-safe CCS/CCUS. In addition, a further 50 million unallocated allowances from the Market Stability Reserve, together with remaining unallocated funds from the existing NER 300 Program, will be made available to support eligible projects.
最接近的国际范例是欧盟排放交易体系的新进入者储备机制(NER)。2009年,欧盟委员会(EC)、欧洲投资银行(EIB)和欧盟成员国同意留出3亿个配额,用于补贴碳捕集、利用与封存技术以及创新型可再生能源技术的装置,因此该基金名为“NER 300”(欧盟委员会,2017年)。鉴于2008年碳价走向每吨30欧元,人们原本希望能筹集到高达90亿欧元。然而,随后价格暴跌,直到2012年12月底,欧盟气候行动专员康妮·赫德egaard才最终宣布第一轮NER300资金分配的结果——但由于配额价格下跌,只能向欧洲各地的23个创新型可再生能源项目授予12亿欧元。没有一个碳捕集、利用与封存技术项目获得资助,而且由于选择过程漫长,申请NER300资金的碳捕集、利用与封存技术项目错过了在欧盟排放交易体系第四阶段(2020 - 2030年)立法下获得投资的最理想时机,该阶段于2018年4月生效,从2021年起至少将预留4亿个配额(称为NER400),以设立一个可再生能源和环境安全的碳捕集、利用与封存技术示范项目创新基金。此外,市场稳定储备中另外5000万个未分配的配额,连同现有NER 300计划中剩余的未分配资金,将用于支持符合条件的项目。
To enable this approach, three key elements need to be considered for regulating ETS funds. First, regulators need to define the financing conditions, including decisions on how much support for projects is available, different ways the funds can be disbursed, i.e. as grants or loans for instance, whether a co-financing rate exists, and any other conditions that should be applied. Second, clear eligibility criteria and a transparent selection process need to be defined. Typically, a selection process involves some kind of ranking of eligible proposals so that they can be selected for funding in rank order, until the available funding limit is reached or there are no further eligible proposals. Third, the responsibilities of different institutions with regards to the implementation of the funding program need to be defined. Such responsibilities include, but are not limited to, issuing calls for proposals, monetizing ETS emission allowances, and assessing the technical and financial viability of projects.
为了实施这种方法,在管理排放交易体系资金时需要考虑三个关键要素。首先,监管机构需要确定融资条件,包括决定对项目的支持力度、资金发放的不同方式(例如作为赠款或贷款)、是否存在共同融资率以及应适用的任何其他条件。其次,需要确定明确的资格标准和透明的选择过程。通常,选择过程涉及对符合条件的提案进行某种排名,以便可以按排名顺序选择它们进行资助,直到达到可用资金限额或没有更多符合条件的提案。第三,需要确定不同机构在实施资助计划方面的职责。这些职责包括但不限于发布提案征集通知、将排放交易体系排放配额货币化以及评估项目的技术和财务可行性。
Auctioning revenue of ETS allowances could be a viable option to finance the first few CCUS demonstration projects in the iron/steel sector in China, assuming that the scale of ETSs in China could generate sufficient revenue to support financing CCUS projects. Auctioning revenue of ETS allowances is also the most flexible option, and this option can also be combined with the other options. For example, the steel sector could be brought into the ETS as per option 1, with revenue from auctioning allowances to the power sector being recycled to offset the impact on the steel sector’s international competitiveness. It could also be combined with project-based crediting, by providing successful projects with additional funding which could be in the form of a fixed amount, or a variable amount, e.g., based on meeting the difference between the current carbon price and the abatement cost, or a multiple of the carbon price.
假设中国碳排放权交易体系的规模能够产生足够的收入来支持碳捕集、利用与封存技术项目的融资,那么拍卖排放交易体系配额的收入可能是为中国钢铁行业的首批几个碳捕集、利用与封存技术示范项目融资的可行选择。拍卖排放交易体系配额的收入也是最灵活的选择,并且这个选择还可以与其他选择相结合。例如,钢铁行业可以按照选项1纳入碳排放权交易体系,向电力行业拍卖配额的收入可以循环利用,以抵消对钢铁行业国际竞争力的影响。它也可以与基于项目的信用机制相结合,为成功的项目提供额外资金,资金形式可以是固定金额,也可以是可变金额,例如基于满足当前碳价与减排成本之间的差额,或者碳价的倍数。
Two potential limitations of this approach are the uncertainty in the carbon price, and the need for agreement by relevant government finance departments to establish and allocate special funds, as discussed earlier. Policymakers in China could consider directly awarding allowances to steel companies building CCUS projects to avoid the financial approval process, but this method should be temporary. Finally, a limitation of this approach is that it could not be scaled to support every possible steel sector CCUS project, but could potentially incentivize early demonstration projects with adequate financial support, which would enable costs of next-generation projects to fall by learning.
这种方法的两个潜在限制是碳价的不确定性,以及如前所述需要相关政府财政部门同意设立和分配专项资金。中国的政策制定者可以考虑直接向建设碳捕集、利用与封存技术项目的钢铁公司授予配额,以避免财务审批过程,但这种方法应该是临时性的。最后,这种方法的一个限制是它无法扩大规模以支持钢铁行业的每一个可能的碳捕集、利用与封存技术项目,但有可能通过充足的财政支持激励早期示范项目,这将使下一代项目的成本通过学习而降低。
The amount and type of MRV required for CCUS projects funded in this way would depend on the nature of the selection process and the objectives of the funding program. For example, if the objective is purely to demonstrate a carbon capture technology, then it may not be necessary to set in place a system for monitoring long-term storage. However, in most circumstances it would still be desirable to have robust measurement and reporting of the actual emission reductions (or potential emission reductions, in the case of capture-only projects) resulting from the funded projects, using a consequential accounting methodology as outlined under option 2, including MRV for geological storage and reversal of storage, liability, insurance and EOR.
以这种方式资助的CCUS项目所需的监测、报告与核证(MRV)的数量和类型,将取决于选择过程的性质和资助计划的目标。例如,如果目标纯粹是为了演示一种碳捕获技术,那么可能没有必要建立一个长期封存监测系统。然而,在大多数情况下,使用选项2中概述的相应核算方法,对资助项目产生的实际减排量(或仅捕获项目的潜在减排量)进行强有力的测量和报告仍然是可取的,包括地质封存和封存逆转、责任、保险和提高采收率的MRV。
In addition, the conditions of the funding allocation may set certain conditions which have to be met, such as meeting a certain timeline, capture rate or total amount of ${\mathrm{{CO}}}_{2}$ stored, and these parameters would need to be monitored.
此外,资金分配的条件可能会设定一些必须满足的条件,例如满足特定的时间表(timeline)、捕获率或${\mathrm{{CO}}}_{2}$封存总量,这些参数需要进行监测。
4 Section 4
4 第4节
4.1 Think Ahead
4.1 提前思考
Carbon emission trading system (ETS) is a market-based mechanism that can help to achieve emission reduction targets in a cost-effective fashion. In this chapter, we have explored different design options of ETS in connection with CCUS. Specifically, to better incentivize CCUS development in China, we have tentatively [emphasis added] discussed three options, and with a focus on the iron/steel sector. These design options are “tentative”, in view of the fact that while China’s regional ETS pilots have covered the iron/steel sector, China’s national carbon market, launched in late 2017, has yet to cover the iron/steel sector. But we believe that the exploration is not futile, because the logic could apply to other sectors (e.g., the power sector).
碳排放交易体系(ETS)是一种基于市场的机制,有助于以具有成本效益的方式实现减排目标。在本章中,我们探讨了与碳捕获、利用与封存(CCUS)相关的ETS不同设计选项。具体而言,为了更好地激励中国的CCUS发展,我们初步[重点补充]讨论了三种选项,并重点关注钢铁行业。鉴于中国的区域ETS试点已涵盖钢铁行业,而2017年末启动的中国全国碳市场尚未涵盖钢铁行业,这些设计选项是“初步的”。但我们认为这种探索并非徒劳,因为其逻辑可能适用于其他行业(如电力行业)。
For the time being, the national carbon market only covers the power sector and the existing regional ETS pilots are expected to operate in parallel with the national carbon market. Over the medium- to long-term, however-along with petrochemicals, chemicals, building materials, nonferrous metals, papermaking, electricity and aviation, the iron/steel sector is expected to be integrated into the national carbon market (NDRC, 2017b, 2017c). So it is relevant to think and plan ahead.
目前,全国碳市场仅涵盖电力行业,现有的区域ETS试点预计将与全国碳市场并行运行。然而,从中长期来看,随着石油化工、化工、建材、有色金属、造纸、电力和航空等行业,钢铁行业预计也将被纳入全国碳市场(国家发展和改革委员会,2017b,2017c)。因此,提前思考和规划是有必要的。
4.2 Concluding Remarks
4.2 结论
To recap, there are three tentative design options, and they are as follows: The first option is to allow ${\mathrm{{CO}}}_{2}$ stored through CCUS to be regarded as “not or low emitted” for the purposes of ETS compliance, such that CCUS-fitted or retrofitted iron/steel plant can realize emission reductions at the time of performance. This option would allow CCUS-fitted plants to generate revenues by selling spare allowances, or not having to purchase additional allowances in the carbon market.
概括而言,有三种暂定的设计方案,具体如下:第一种方案是,为了符合排放交易体系的要求,允许将通过碳捕集、利用与封存(CCUS)技术封存的${\mathrm{{CO}}}_{2}$视为“未排放或低排放”,这样配备或改造了CCUS技术的钢铁厂在运行时就能实现减排。此方案将允许配备CCUS技术的工厂通过出售多余配额或无需在碳市场购买额外配额来创收。
The second option is to adopt a project-based baseline-and-credit approach. In this option, the national ETS covered emitters could purchase offset credits from CCUS-fitted or retrofitted iron/steel plants and use these purchased credits to meet their ETS compliance obligations. The third option is to use revenues generated by auctioning off emission allowances to support development and deployment of CCUS technologies in the iron/steel sector.
第二种方案是采用基于项目的基准线与信用方法。在此方案中,纳入国家排放交易体系的排放源可以从配备或改造了CCUS技术的钢铁厂购买抵消信用额度,并使用这些购买的信用额度来履行其在排放交易体系中的合规义务。第三种方案是利用拍卖排放配额产生的收入来支持钢铁行业CCUS技术的开发和部署。
In comparative perspective, the first option has more straightforward MRV requirements than the second, but requires a change to enlarge the scope of the national carbon market to include the iron/steel sector, whereas the second option could be implemented relatively easily. Yet, for the first two options work effectively, the overall ETS cap has to set at a level ambitious enough to achieve a sufficiently high price, which means, at least theoretically, all cheaper abatement options would have to be exhausted before CCUS in the iron/steel sector become the marginal price-setting option. In other words, CCUS would need to compete with all other abatement options featuring lower costs. In reality, however, the current low prices in China’s ETSs, regional or national, are unlikely to be able to support a CCUS project in the iron/steel sector, in the absence of additional subsidies from other sources.
从比较的角度来看,第一种方案的监测、报告与核查(MRV)要求比第二种方案更直接,但需要扩大国家碳市场的范围以纳入钢铁行业,而第二种方案相对容易实施。然而,要使前两种方案有效运作,排放交易体系的总体上限必须设定在足够高的水平,以实现足够高的价格,这意味着,至少在理论上,在钢铁行业的CCUS成为边际价格设定选项之前,所有成本更低的减排选项都必须用尽。换句话说,CCUS需要与所有其他成本更低的减排选项竞争。然而,实际上,在中国区域或国家的排放交易体系目前的低价情况下,如果没有其他来源的额外补贴,不太可能支持钢铁行业的CCUS项目。
Thus, by comparison, the third option offers a more promising way to support early-stage CCUS projects in the iron/steel sector. But even for this option to work, it must be endorsed by relevant government departments and detailed rules and procedures need to be developed and established. That said, standing alone, the third option is the most flexible options, but it is not mutually exclusive with the first or the second option, and indeed can be combined with either of them. It is therefore recommended if a staged approach is taken. In strategic sequencing, the third option, if rolled out first, could potentially lever much stronger support than the other two options in the short-term. Overtime, when the carbon price becomes sufficiently high and the long-term price signal becomes strong and stable, ${}^{7}$ other two options would become sufficient on their own. In any case, a robust MRV system as well as a sound regulatory framework would be a pre-condition for all three options to work effectively.
因此,相比之下,第三种方案为支持钢铁行业的早期CCUS项目提供了更有前景的途径。但即使要使此方案有效运作,也必须得到相关政府部门的认可,并且需要制定和建立详细的规则和程序。也就是说,单独来看,第三种方案是最灵活的方案,但它与第一种或第二种方案并非相互排斥,实际上可以与其中任何一种结合。因此,如果采取分阶段方法,建议优先考虑第三种方案。在战略顺序上,如果首先推出第三种方案,可能在短期内比其他两种方案获得更有力的支持。随着时间的推移,当碳价格变得足够高且长期价格信号变得强劲和稳定时,${}^{7}$其他两种方案自身也将变得足够。无论如何,强大的MRV系统以及健全的监管框架是所有三种方案有效运作的先决条件。
Table 3 summarizes the opportunities and challenges that each option may bring to CCUS in the iron/steel sector in China.
表3总结了每种方案可能给中国钢铁行业的CCUS带来的机遇和挑战。
Finally, it is worth noting that while the sectoral cut of this study is the iron/steel sector (see Appendix 1), the logic of the three different design options of ETS to better incentivize CCUS applications could also apply to the power sector. The power sector is the first sector covered by China’s national carbon market, which accounts for the lion’s share (about 45-50%) of China’s ${\mathrm{{CO}}}_{2}$ emissions. Note also that, as discussed in Chapters 1 and 2, currently most of China’s CCUS pilots are in the power sector. As a novel and emerging technology on industrial scale to directly reduce carbon emissions, CCUS is currently included in China’s mid- to long- term development plan (MOST, 2013; State Council, 2006). Although the NDRC has provided policy support for CCUS demonstrations (NDRC, 2013b), there is not yet any dedicated regulatory framework in place to ensure the legal and commercial certainty for CCUS projects in China.
最后,值得注意的是,虽然本研究的行业切入点是钢铁行业(见附录1),但排放交易体系更好地激励CCUS应用的三种不同设计方案的逻辑也适用于电力行业。电力行业是中国国家碳市场涵盖的首个行业,占中国${\mathrm{{CO}}}_{2}$排放量的最大份额(约45 - 50%)。还需注意的是,如第1章和第2章所述,目前中国的大多数CCUS试点都在电力行业。作为一种直接减少碳排放的新型工业规模新兴技术,CCUS目前已被纳入中国的中长期发展规划(科学技术部,2013年;国务院,2006年)。尽管国家发展和改革委员会已为CCUS示范项目提供了政策支持(国家发展和改革委员会,2013b),但中国尚未建立任何专门的监管框架来确保CCUS项目的法律和商业确定性。
That notwithstanding and in view of China’s mid- to long-term development plan of green growth, this study has looked ahead in exploring different design options of China’s ETSs in connection with the financing of early-stage CCUS demonstration projects. And so doing, it has brought us back to the nexus of this study, i.e., the synergy between policy, technology, and market to push forward the frontier of inclusive and sustainable growth.
尽管如此,鉴于中国绿色增长中长期发展规划考虑,本研究前瞻性地探索了中国排放交易体系与早期CCUS示范项目融资相关的不同设计方案。这样做使我们回到了本研究的核心,即政策、技术和市场之间的协同作用,以推动包容性和可持续增长的前沿。
${}^{7}$ Price stability is important. Otherwise, the funding required for CCUS is uncertain: more would be required if the allowance price falls, while at the same time, auction revenues would also fall. To counteract this effect, it is proposed that the volume of allowances set aside for the fund could be flexible, thus operating in a similar way to the Market Stability Reserve in the EU-ETS, withdrawing more allowances from the market when the price is low, and less when the price is high. This would have the beneficial effect of creating greater price stability in the ETS as a whole.
${}^{7}$ 价格稳定很重要。否则,碳捕集、利用与封存(CCUS)所需的资金就不确定:如果配额价格下跌,所需资金就会更多,而与此同时,拍卖收入也会下降。为抵消这种影响,建议为该基金预留的配额数量可以灵活调整,从而以类似于欧盟排放交易体系(EU-ETS)中市场稳定储备机制的方式运作,在价格低时从市场中提取更多配额,在价格高时提取较少配额。这将对在整个排放交易体系中创造更大的价格稳定性产生有益影响。
Table 3 Comparison of 3 design options of ETS
表3 排放交易体系三种设计方案的比较
| Options | Opportunities | Challenges |
| (1) Including the iron/steel sector in the national ETS and allowing ${\mathrm{{CO}}}_{2}$ stored through CCUS to be regarded as 'not or low emitted' for the purposes of ETS compliance obligations | - Steel plants with CCUS could realize emission reductions at the time of performance, generating revenue by selling spare allowances or avoiding extra costs or not having to purchase from the carbon market - MRV requirements are relatively straightforward compared with option 2, as all steel plants would already have to monitor and report their emissions, so additional MRV would only apply to CCUS components | - Carbon prices are unlikely to be high enough to incentivize CCUS implementation on their own, as all abatement options in both the power sector and the steel sector that are cheaper than CCUS would be exploited first - A free allocation approach based on historical emissions would tend to have less effect to motivate iron/steel enterprises to adopt advanced carbon abatement technology such as CCUS |
| (2) Allowing offsets from iron/steel CCUS projects in China's ETSs | - The option enables sectors not covered by an ETS to generate revenues from reducing carbon emissions - This option does not require a major change to the scope of the national ETS | - Offsets will only be used for compliance within an ETS when their price is lower than the prevailing price of allowances in the ETS. Therefore, the likely revenue is lower than option 1 - The transaction costs of option 2 are also potentially higher than option 1 |
| (3) Incentivizing CCUS with finance from auctioning of ETS allowances or directly awarding allowances to steel plants fitted with CCUS | - The most flexible option, which can also be combined with the other options | - Market price fluctuations would create uncertainty over the actual budget available for disbursement - Setting up new funds requires government finance department approval - CCUS might need to compete with other demands for such funds |
Appendix 1
附录1
Table A1: GHG accounting guidelines for iron/steel industry in China (NDRC, 2013a)
表A1:中国钢铁行业温室气体核算指南(国家发展和改革委员会,2013年a)
| Calculation formula | Notes | |
| ${\mathrm{{Eco}}}_{2}$ (Total ${\mathrm{{CO}}}_{2}$ emissions in steel-making process) | ${\mathrm{{Eco}}}_{2} = {\mathrm{E}}_{\text{ combustion }} + {\mathrm{E}}_{\text{ power\&heat }} - {\mathrm{E}}_{\text{ sequestration }}$ | ${\mathrm{{Eco}}}_{2}$ presents total ${\mathrm{{CO}}}_{2}$ emissions; Ecombustion refers to ${\mathrm{{CO}}}_{2}$ emissions of all net consumed fossil fuel combustion activities; Eprocess represents ${\mathrm{{CO}}}_{2}$ emissions from industrial production processes; Epower&heat is ${\mathrm{{CO}}}_{2}$ emissions corresponding to net purchased power and heat by enterprise; Esequestration is implicit ${\mathrm{{CO}}}_{2}$ of carbon-sequestered products (e.g., crude steel) |
| Ecombustion ( ${\mathrm{{CO}}}_{2}$ emissions of all net consumed fossil fuel combustion activities) | ${\mathrm{E}}_{\text{ combustion }} = \frac{44}{12}\mathop{\sum }\limits_{{i = 1}}^{n}\left( {A{D}_{i} \times C{C}_{i} \times {OF}}\right)$ | ${ADi}$ refers to activity level of fossil fuel consumed within accounting and reporting period (GJ); ${CCi}$ refers to carbon content per unit of calorific value of fossil fuel (iC/GJ); OFi is the rate of carbon oxidation of fossil fuel (%) |
(continued)
(续)
Table A1: (continued)
表A1:(续)
| Calculation formula | Notes | |
| Eprocess ( ${\mathrm{{CO}}}_{2}$ emissions from industrial production processes) | ${E}_{\text{ process }} = {E}_{\text{ solvent }} + {E}_{\text{ electorde }} + {E}_{\text{ rawmaterials }}$ $= \mathop{\sum }\limits_{{i = 1}}^{n}\left( {{P}_{i} \times D{X}_{i} \times E{F}_{i}}\right) + {P}_{\text{ electrode }} \times E{F}_{\text{ electrode }}$ $+ \mathop{\sum }\limits_{{i = 1}}^{n}{M}_{i} \times E{F}_{i}$ | Esolvent is ${\mathrm{{CO}}}_{2}$ emissions from solvent consumption; Eelectrode is ${\mathrm{{CO}}}_{2}$ emissions from consumption; Eraw materials is ${\mathrm{{CO}}}_{2}$ emissions from consumption of other carbonaceous materials such as pig iron, ferroalloy and direct reduced iron; ${Pi}$ is net consumption of solvent; ${DXi}$ is average purity of solvent (%) EFi is ${\mathrm{{CO}}}_{2}$ emission factor of solvent $\left( {{\mathrm{{tCO}}}_{2}/\mathrm{t}}\right)$ ; Pelectrode is amount of electrode consumed for EAF-based steel making (t); EFelectrode is ${\mathrm{{CO}}}_{2}$ emission factor for electrode consumed; ${Mi}$ is purchased amount of carbonaceous materials; ${EFi}$ is ${\mathrm{{CO}}}_{2}$ emission factor for purchased carbonaceous materials $\left( {{\mathrm{{tCO}}}_{2}/\mathrm{t}}\right)$ |
(continued)
(续)
Table A1: (continued)
表A1:(续)
| Calculation formula | Notes | |
| Epower&heat ( ${\mathrm{{CO}}}_{2}$ emissions corresponding to net purchased power and heat by enterprise) | ${\mathrm{E}}_{\text{ power\&heat }} = {\mathrm{{AD}}}_{\text{ power }} \times {\mathrm{{EF}}}_{\text{ power }} + {\mathrm{{AD}}}_{\text{ heat }} \times {\mathrm{{EF}}}_{\text{ heat }}$ | ADpower and ADheat are net purchased electricity (MWh) and heat (GJ) amount within accounting and reporting period; EFpower and EFheat are ${\mathrm{{CO}}}_{2}$ emission factors for electricity $\left( {{\mathrm{{tCO}}}_{2}/\mathrm{{MWh}}}\right)$ and heat $\left( {{\mathrm{{tCO}}}_{2}/\mathrm{{GJ}}}\right)$ |
| Esequestration (Implicit ${\mathrm{{CO}}}_{2}$ emissions of carbon-sequestering products) | ${\mathrm{E}}_{\text{ sequestration }} = \mathop{\sum }\limits_{{i = 1}}^{n}A{D}_{\text{ sequestration }} \times E{F}_{\text{ sequestriation }}$ | ${\mathrm{{AD}}}_{\text{ sequestration }}$ is output of carbon sequestering product (t); ${\mathrm{{EF}}}_{\text{ sequestration }}$ is emission factor for carbon-sequestering product $\left( {{\mathrm{{tCO}}}_{2}/\mathrm{t}}\right)$ |
Acronym Full spelling
首字母缩写 全称
AAUs Assigned Amount Units
AAUs 分配数量单位
CCER Chinese CER
CCER 中国核证自愿减排量
CCS Carbon capture and storage
CCS 碳捕获与封存
CCUS Carbon capture, utilization and storage
CCUS 碳捕获、利用与封存
CDM Clean Development Mechanism
CDM 清洁发展机制
CERs Certified Emission Reductions
CERs 核证减排量
${\mathrm{{CO}}}_{2}$ Carbon dioxide
${\mathrm{{CO}}}_{2}$ 二氧化碳
${\mathrm{{CO}}}_{2}\mathrm{e}$ Carbon dioxide equivalent
${\mathrm{{CO}}}_{2}\mathrm{e}$ 二氧化碳当量
EC European Commission
EC 欧盟委员会
FFCER Fujian Forestry Certified Emission Reduction
福建林业核证减排量
EIB European Investment Bank
欧洲投资银行
EOR Enhanced oil recovery
强化采油
ETS Emissions trading scheme
排放交易体系
ERUs Emission Reduction Units
减排单位
EU ETS EU Emissions Trading System
欧盟排放交易体系
GDP Gross Domestic Product
国内生产总值
GHG Greenhouse gas
温室气体
IET International Emission Trading
国际排放交易
IPCC Intergovernmental Panel on Climate Change
政府间气候变化专门委员会
JI Joint Implementation
联合履行
MEE Ministry of Ecology and Environment
生态环境部
Mtce Million tons of coal equivalent
百万吨标准煤
NAP National Allocation Plans
国家分配计划
NDC Nationally Determined Contribution
国家自主贡献
NDRC National Development and Reform Commission
国家发展和改革委员会
PHCER Pu Hui Certified Emission Reduction
核证减排量普惠减排量
${\mathrm{{SO}}}_{2}$ Sulphur dioxide
${\mathrm{{SO}}}_{2}$ 二氧化硫
Tce Ton of coal equivalent
吨标准煤
UNEP United Nations Environment Program
联合国环境规划署
References
参考文献
Beer, J. D., Harnisch, J., & Kerssemeeckers, M. (2003). Greenhouse gas emissions from iron and steel production. ECOFYS.
Brander, M. & Ascui, F. (2018). Consequential GHG assessment of carbon capture, utilization and storage for a steel plant in China. BHP Carbon Capture, Utilization and Storage in China’s Iron and Steel Sector Project. University of Edinburgh. COASE, R. H. 1960. The problem of social cost.
Dechezleprêtre, A., Nachtigall, D. & Venmans, F. (2018). The joint impact of the European Union Emissions trading scheme on carbon emissions and economic performance. OECD Working Papers.
Dixon, T., Leamon, G., Zakkour, P., & Warren, L. (2013). CCS projects as Kyoto protocol CDM activities. Energy Procedia, 37, 7596-7604.
Duan, M., Tao, P., & Zhang, X. (2014). Review of carbon emissions trading pilots in China. Energy & Environment, 25, 527-550.
EEA. (2011). Air pollution impacts from carbon capture and storage (CCS). Copenhagen. EU MERCI. (2018). Technical analysis-iron and steel sector (NACE C24.1-24.2-24-5).
European Commission. (2003). Directive 2003/87/EC of the European Parliament and of the Council of 13 October 2003 establishing a scheme for greenhouse gas emission allowance trading within the Community and amending Council Directive 96/61/EC (Text with EEA relevance).
European Commission. (2009a). Directive 2009/29/EC of the European Parliament and of the Council of 23 April 2009. Official Journal of the European Union. Strasbourg.
European Commission. (2009b). Directive 2009/31/EC of the European Parliament and of the Council of 23 April 2009 on the geological storage of carbon dioxide and amending Council Directive 85/337/EEC, European Parliament and Council Directives 2000/60/EC, 2001/80/EC, 2004/35/EC, 2006/12/EC, 2008/1/EC and Regulation (EC) No 1013/2006 (Text with EEA relevance). In UNION, T. E. P. A. T. C. O. T. E. (ed.).
European Commission. (2011). Implementation of Directive 2009/31/EC on the geological storage of Carbon Dioxide, Guidance Document 4, Article 19 Financial Security and Article 20 Financial Mechanism.
European Commission. (2015a). Decision concerning the establishment and operation of a market stability reserve for the Union greenhouse gas emission trading scheme and amending Directive 2003/87/EU.
European Commission. (2015b). eu ets handbook. european commission.
European Commission. (2017). Funding innovative low-carbon technologies: the NER 300 program [Online]. Available: https://ec.europa.eu/clima/sites/clima/files/docs/ner300_fac tsheet_en.pdf. Accessed 12 October 2019.
European Commission. (2018). Directive (EU) 2018/410 of the European Parliament and of the council of 14 March 2018 amending Directive 2003/87/EC to enhance cost-effective emission reductions and low-carbon investments, and Decision (EU)2015/1814 Brussels.
EYGM. (2014). Understanding China’s emissions trading schemes and emissions reporting. EYGM Limited.
Fang, C. C. (2018). Carbon pricing, correcting climate change’s market failure. Sustainability: The Journal of Recording, 11.
ICAP. (2019a). ETS Fact sheets [Online]. International Carbon Action Partnership. Available: https://icapcarbonaction.com/en/ets-map.Accessed 28 July 2019.
ICAP. (2019b). China National ETS.
IETA. (2014). Use of offset credits across emission trading systems and carbon pricing mechanisms. IETA-Climate Challenges, Market Solutions.
International Energy Agency. (2017). Energy Technology Perspectives 2017.
IPCC. (2018). Special report on global warming of 1.5 ${}^{ \circ }\mathrm{C}$ (SR15). Intergovernmental Panel on Climate Change.
Irlam, L. (2017). Global costs of carbon capture and storage: 2017 update. Global CCS Institute.
Liang, X., Lin, Q., Muslemani, H., Lei, M., Liu, Q., Li, J., Wu, A., Liu, M., & Ascui, F. (2019). Assessing the economics of ${\mathrm{{CO}}}_{2}$ capture in China’s iron/steel sector: A case study. Energy Procedia, 158, 3715-3722.
Mccormck, M. (2012). A greenhouse gas accounting framework for carbon capture and storage projects. Center For Climate and Energy Solutions.
MEE. (2019). Interim regulations for the administration of carbon emission permit trading (Consultation Paper). fgs.mee.gov.cn. Ministry of Ecology and Environment.
MOST. (2013). The 12th five-year plan for national development of carbon capture, utilization and storage technology.
Muslemani, H., Jiang, M., Chen, X. & Jia, Z. (2019). Lower carbon technology approaches for steel manufacturing in China. Working Paper 4.7 for the BHP Industrial CCS Project ‘Unlocking the Potential of CCUS for Steel Production in China’. Edinburgh, UK.
Slater, H., Boer, D. D., Shu, W. & Guoqiang, Q. (2018). The 2018 China carbon pricing survey. Beijing.
NCEPU. (2019). Techno-economic analysis of ${\mathrm{{CO}}}_{2}$ capture technologies for the Iron/Steel industry in China. Working Paper 4.11 for the BHP Iron and Steel CCS Project. North China Electric Power University, UK-China (Guangdong) CCUS Centre and The University of Edinburgh.
NDRC. (2013a). Notice on greenhouse gas emission accounting methods and reporting guidelines for 10 sectors (Trial).
NDRC. (2013b). Notice on promoting carbon capture, utilization and storage demonstration.
NDRC. (2017a). NDRC Announcement, 2017 No.2 [Online]. National Development and Reform Commission. Available http://www.ndrc.gov.cn/zcfb/zcfbgg/201703/t20170317_ 841211.html. Accessed 11 October 2019.
NDRC. (2017b). Notice on work plan for carbon emissions reporting, verification and monitoring for 2016 and 2017. National Development and Reform Commission.
NDRC. (2017c). Work plan for construction of the national emissions trading system (Power Sector). National Development and Reform Commission.
NDRC. (2018). Action plan on the establishment of a market-oriented and diversified ecological protection compensation mechanism.
Pang, T., & Duan, M. (2016). Cap setting and allowance allocation in China’s emissions trading pilot programs: Special issues and innovative solutions. Climate Policy, 16, 815-835.
State Council. (2006). National mid- to long-term science and technology development plan (2006-2020).
Stavins, R. N. (2001). Experience with market-based environmental policy instruments. Resources for the Future.
Tunnicliffe, H. (2017). CCS: Why bother? [Online]. The Chemical Engineer. Available: https://www.thechemicalengineer.com/features/ccs-why-bother/.Accessed 15 December 2018.
UNFCCC. (1998). Kyoto protocol to the United Nations framework convention on climate change. United Nations.UNITED NATIONS 2015. The Paris Agreement. Paris: United Nations.
Wang, X., Teng, F., Wang, G., Zhou, S., & Cai, B. (2018). Carbon leakage scrutiny in ETS and non-ETS industrial sectors in China. Resources, Conservation and Recycling, 129, 424-431.
World Bank Group 2018. (2019). State and trends of carbon pricing 2018. World Bank Group. Carbon pricing dashboard [Online].World Bank Group Available: https://carbonpricingda shboard.worldbank.org/map_data [Accessed 28 July 2019].
World Resources Institute & World Business Council for Sustainable Development. (2005). The GHG protocol for project accounting. USA.
World Steel Association. (2019). Global crude steel output increases by 4.6% in 2018[Online]. World Steel Association. Available https://www.worldsteel.org/media-centre/press-rel eases/2019/Global-crude-steel-output-increases-by-4.6–in-2018.html. Accessed 28 July 2019.
Xiong, L., Shen, B., Qi, S., & Price, L. (2015). Assessment of allowance mechanism in China’s carbon trading pilots. Energy Procedia, 75, 2510-2515.
Xu, W., Wan, B., Zhu, T., & Shao, M. (2016). CO2 emissions from China’s iron and steel industry. Journal of Cleaner Production, 139, 1504-1511.
Zaman, P., & Yang, K. 2019. Update on the Chinese National Emissions Trading Scheme-some progress but more questions than answers [Online]. Reed Smith Client Alerts. Accessed October 2019.
Part IV Projection
第四部分 预测
Achieving Carbon Neutrality by 2060: What (More) Has to Be Done?
2060年前实现碳中和:还需做什么?
Jun Fu, Jintao Xu, Yu Liu, Lunyu Xie, and Shilei Liu
傅军、徐晋涛、刘彧、谢伦裕、刘世磊
On September 22, 2020, at the General Debate of the 75th Session of the UN General Assembly, Chinese President Xi Jinping delivered a speech and promised that China would peak carbon emissions prior to 2030 and try to achieve carbon neutrality by ${2060.}^{1}$ That will be a very daunting task for China. In the wake of President Xi’s speech, a workshop was held at the National School of Development at Peking University. The purpose was to look ahead and scope up what has to be done for China years down the road to achieve that daunting task. The authors of the present chapter all attended the workshop, and we agreed that there were essentially four approaches to the challenge, i.e., public policy approach (PPA), market-based approach (MBA), carbon capture and storage (CCS), and nature-based solutions (NBS). As the theme of climate change has much to do
2020年9月22日,在第75届联合国大会一般性辩论上,中国国家主席习近平发表讲话,承诺中国将在2030年前实现碳排放达峰,并力争在${2060.}^{1}$前实现碳中和。这对中国来说将是一项艰巨的任务。习近平主席发表讲话后,北京大学国家发展研究院举办了一次研讨会。目的是展望未来,全面规划中国在未来数年为实现这一艰巨任务必须采取的行动。本章的作者都参加了这次研讨会,我们一致认为应对这一挑战主要有四种途径,即公共政策途径(PPA)、市场机制途径(MBA)、碳捕获与封存(CCS)和基于自然的解决方案(NBS)。由于气候变化主题与全球范围内所谓的“公地悲剧”(哈丁,1968年)密切相关,${2060.}^{1}$必须提升PPA在国际合作与协调方面的作用。
${}^{1}$ Subsequently the Chinese government redefied the goal of “achieving carbon neutrality by 2060” as including not just ${\mathrm{{CO}}}_{2}$ but all GHGs.
${}^{1}$随后,中国政府重新界定了“2060年前实现碳中和”的目标,不仅包括${\mathrm{{CO}}}_{2}$,还包括所有温室气体。
The original version of this chapter was revised: A new sentence has been added on pages 254 and 272, respectively, in Sects. 2.1 and 4.4, and the symbol in the Table 2 note has been changed from “$” to “$” in Sect. 4.1. The correction to this chapter can be found at https://doi.org/10.1007/978-981-16-4310-1_8.
本章的原始版本已修订:第2.1节和第4.4节的第254页和第272页分别新增了一句话,第4.1节表2注释中的符号已从“$”更改为“$”。本章的勘误可在https://doi.org/10.1007/978-981-16-4310-1_8上找到。
J. Fu $\left( \varnothing \right) \cdot$ J. Xu $\cdot$ S. Liu
傅军$\left( \varnothing \right) \cdot$徐晋涛$\cdot$刘世磊
National School of Development, Peking University, Beijing, China
中国北京 北京大学国家发展研究院
Y. Liu
刘彧
Institutes of Science and Development, Chinese Academy of Sciences, Beijing, China
中国北京 中国科学院科技战略咨询研究院
L. Xie
谢伦裕
Renmin University of China, Beijing, China
中国北京 中国人民大学
with the so-called “tragedy of the commons” (Hardin, 1968) on a global scale, ${}^{2}$ the role of PPA in connection with international cooperation and coordination has to be elevated.
鉴于全球范围内所谓的“公地悲剧”(哈丁,1968年),${}^{2}$必须提升PPA在国际合作与协调方面的作用。
Now armed with the conceptual framework of PPA + MBA + CCS + NBS (or PMCN model for short), our job was to build the model, get the data, and project forward with different scenarios such that we could help policy makers understand likely future outcomes as well as the implications of alternative policies. Intellectually, the dynamical PMCN modelling was both a deductive and inductive exercise within three sets of interrelated parameters, i.e., climate change, energy structure, and economic growth—along similar lines of the DICE model (dynamic integrated model of climate and the economy) developed by Nobel Laureate in economics William Nordhaus (Nordhaus and Boyer, 2000).
现在,凭借PPA + MBA + CCS + NBS的概念框架(简称为PMCN模型),我们的工作是构建模型获取数据,并推进不同情景的分析,以便帮助政策制定者了解未来可能的结果以及替代政策的影响。从学术角度看,动态PMCN建模是在三组相互关联的参数(即气候变化、能源结构和经济增长)范围内进行的演绎和归纳练习,类似于诺贝尔经济学奖得主威廉·诺德豪斯(诺德豪斯和博耶,2000年)开发的DICE模型(气候与经济动态综合模型)。
This chapter represents the results of that exercise. The chapter is organized into 4 sections. Section 1 puts China’s climate mitigation and adaption efforts in global perspective. Section 2 elaborates on the framework of PPA + MBA + CCS + NBA in the Chinese context. Section 3 explains the mechanics of our model construction and scenarios planning. Projection results and key takeaways are presented in Section 4.
本章展示了这一工作的成果。本章分为4节。第1节从全球视角阐述中国的气候缓解和适应努力。第2节详细说明中国背景下PPA + MBA + CCS + NBA的框架。第3节解释我们的模型构建和情景规划机制。第4节展示预测结果和关键要点。
1 Section 1
1 第1节
1.1 Climate Change Mitigation and Adaption in Global Perspective
1.1 全球视角下的气候变化缓解与适应
Climate change has posed a grave threat to mankind. Reduction of carbon emissions has increasingly become a global consensus. According to the IPCC (2018), in order to avert the worst impact of climate change on the eco-system on Earth, it is critical to limit global warming to ${1.5}^{ \circ }\mathrm{C}$ . This, in turn, requires a ${45}\%$ reduction in global ${\mathrm{{CO}}}_{2}$ emissions from 2010 level by 2030, and net zero ${\mathrm{{CO}}}_{2}$ emissions world-wide by the middle of this century. Under the principle “common but differentiated responsibilities” of UNFCCC, while the contracting states to the Paris Agreement have been trying hard to reduce greenhouse gas emissions (GHG), ${}^{3}$ much more must be done. That is, more ambitious nationally determined contributions (NDC) must be adopted to make sure that the goal of staying within ${1.5}^{ \circ }\mathrm{C}$ will be achieved. NDCs are at the heart of the Paris Agreement to reduce ${\mathrm{{CO}}}_{2}$ missions. They embody voluntary efforts by each contracting state to reduce ${\mathrm{{CO}}}_{2}$ emissions and adapt to the impact of climate change.
气候变化对人类构成了严重威胁。减少碳排放日益成为全球共识。根据政府间气候变化专门委员会(IPCC,2018年)的报告,为避免气候变化对地球生态系统造成最严重影响,将全球变暖限制在${1.5}^{ \circ }\mathrm{C}$至关重要。这反过来要求到2030年全球${\mathrm{{CO}}}_{2}$排放量比2010年水平减少${45}\%$,并在本世纪中叶实现全球${\mathrm{{CO}}}_{2}$净零排放。根据《联合国气候变化框架公约》“共同但有区别的责任”原则,虽然《巴黎协定》缔约国一直在努力减少温室气体排放(GHG),但${}^{3}$仍有更多工作要做。也就是说,必须采取更具雄心的国家自主贡献(NDC),以确保实现将升温控制在${1.5}^{ \circ }\mathrm{C}$以内的目标。国家自主贡献是《巴黎协定》减少${\mathrm{{CO}}}_{2}$排放的核心。它们体现了每个缔约国为减少${\mathrm{{CO}}}_{2}$排放和适应气候变化影响所做的自愿努力。
${}^{2}$ Globally, the total amount of ${\mathrm{{CO}}}_{2}$ emissions reached 40.1 billion tons in 2019, about 86% of which was from fossil-fuels and ${14}\%$ from land use. Of the total, ${31}\%$ was sequestered by the land, 23% by the ocean, and the rest (or 46%) went up into the atmosphere.
${}^{2}$在全球范围内,2019年${\mathrm{{CO}}}_{2}$排放总量达到401亿吨,其中约86%来自化石燃料,${14}\%$来自土地利用。其中,${31}\%$被陆地吸收,23%被海洋吸收,其余(即46%)进入大气。
${}^{3}$ In the composition of GHG defined Kyoto Protocol, Carbon Dioxide $\left( {\mathrm{{CO}}}_{2}\right)$ takes about 81%, Methane $\left( {\mathrm{{CH}}}_{4}\right) {10}\%$ , Nitrous Oxide $\left( {{\mathrm{N}}_{2}\mathrm{O}}\right) 7\%$ , and the rest are Fluorinated Gases (e.g.,
${}^{3}$在《京都议定书》定义的温室气体构成中,二氧化碳$\left( {\mathrm{{CO}}}_{2}\right)$约占81%,甲烷$\left( {\mathrm{{CH}}}_{4}\right) {10}\%$,氧化亚氮$\left( {{\mathrm{N}}_{2}\mathrm{O}}\right) 7\%$,其余为含氟气体(如
In November 2018, the UN released a special report—i.e., the IPCC’s ${1.5}{}^{ \circ }\mathrm{C}$ Special Report—urging the contracting states to the Paris Agreement to do more. In light of this, many jurisdictions across the world—including China, the European Union (EU), the United Kingdom (UK), Canada, South Korea, New Zealand, New York, Hawaii and California-renew efforts and set climate targets to carbon neutrality. Carbon neutrality refers to the target to remove as much carbon dioxides from the atmosphere as they are put into it. The overall goal of carbon neutrality is to achieve a zero carbon footprint. In December 2019, the UN announced that 73 countries, 14 regions and 398 cities around the world had started to work towards carbon neutrality by 2050 (UNFCCC, 2019).
2018年11月,联合国发布了一份特别报告——即IPCC的${1.5}{}^{ \circ }\mathrm{C}$特别报告,敦促《巴黎协定》缔约国采取更多行动。有鉴于此,世界上许多司法管辖区——包括中国、欧盟(EU)、英国(UK)、加拿大、韩国、新西兰、纽约、夏威夷和加利福尼亚——重新做出努力并设定了碳中和气候目标。碳中和是指从大气中清除的二氧化碳量与排放到大气中的二氧化碳量相等的目标。碳中和的总体目标是实现零碳足迹。2019年12月,联合国宣布全球73个国家、14个地区和398个城市已开始努力在2050年前实现碳中和(《联合国气候变化框架公约》,2019年)。
Based on the Paris Agreement in 2015, the European Union (EU) had committed itself to the binding target of at least a 40% reduction in GHG emissions from the 1990 level. Having cut a so-called “European Green Deal”, the EU has aimed higher-to achieve a carbon neutral goal by 2050. Specifically, the green deal has raised the EU targets to at least 50% reduction and has started to move towards 55% GHG emissions reduction by 2030. And in line with the EU goal of reaching carbon neutrality by 2050, many European countries have adopted NDCs toward zero net GHG emissions. Austria, Denmark, France, Germany, and Sweden have all put climate policies in place, aiming at carbon neutrality by 2040 (Austria), by 2045 (Sweden), and by 2050 (the rest) respectively.
基于2015年的《巴黎协定》,欧盟(EU)承诺了具有约束力的目标,即至少将温室气体排放量在1990年水平上减少40%。在制定了所谓的“欧洲绿色协议”后,欧盟设定了更高目标——到2050年实现碳中和目标。具体而言,绿色协议将欧盟的目标提高到至少减少50%,并开始朝着到2030年将温室气体排放量减少55%的目标迈进。为符合欧盟到2050年实现碳中和的目标,许多欧洲国家都制定了国家自主贡献,以实现温室气体净零排放。奥地利、丹麦、法国、德国和瑞典都已出台气候政策,分别旨在在2040年(奥地利)、2045年(瑞典)和2050年(其他国家)实现碳中和。
In the United Kingdom (UK), UK Climate-change Act entered into force in June 2019. The Act has confirmed that the UK will achieve zero net carbon emissions by 2050. Under the UK Climate-change Act, Scotland aims to achieve carbon neutrality in 2045, and Welsh will reduce ${\mathrm{{CO}}}_{2}$ emission by ${90}\%$ from 2010 levels by 2030. Similarly, New Zealand amended its Climate Change Response Act in 2019. The Amended (Zero Carbon) Act aims at net zero GHG emissions by 2050. As the agricultural sector accounts for a large part of New Zealand’s GHG emissions, the Zero Carbon Act also aims to reduce biogenic methane emissions by 24-47% from 2017 levels by 2050.
在英国,《英国气候变化法案》于2019年6月生效。该法案已确认英国将在2050年实现净零碳排放。根据《英国气候变化法案》,苏格兰的目标是在2045年实现碳中和,威尔士将在2030年将${\mathrm{{CO}}}_{2}$排放量从2010年的水平降低${90}\%$。同样,新西兰在2019年修订了其《气候变化应对法案》。修订后的(《零碳》)法案旨在到2050年实现温室气体净零排放。由于农业部门占新西兰温室气体排放的很大一部分,《零碳法案》还旨在到2050年将生物源甲烷排放量从2017年的水平减少24%-47%。
As a developing country in the midst of rapid industrialization and urbanization, China has been working hard to catch up in terms of decarbonization. In 2009, China had announced the goal of a 40%-45% reduction in carbon emissions per GDP by 2020, as compared to the 2005 level. In 2015, China set its NDCs to cap ${\mathrm{{CO}}}_{2}$ emissions no later than 2030. According to China’s Climate Change Policy and Action 2019 Annual Report, ${}^{4}$ carbon emissions per GDP had dropped by 45.6% from 2005 level by 2018, exceeding the original reduction target.
作为一个正处于快速工业化和城市化进程中的发展中国家,中国一直在努力追赶脱碳进程。2009年,中国宣布了到2020年单位国内生产总值碳排放比2005年水平降低40%-45%的目标。2015年,中国设定了国家自主贡献目标,最迟在2030年控制${\mathrm{{CO}}}_{2}$排放。根据《中国气候变化政策与行动2019年度报告》,到2018年单位国内生产总值${}^{4}$碳排放比2005年水平下降了45.6%,超过了原定减排目标。
hydrofluorocarbon (HFCs), perfluorocarbon (PFCs), and sulfur hexafluoride (SF6)), about 3%.
氢氟碳化物(HFCs)、全氟化碳(PFCs)和六氟化硫(SF6)),约占3%。
As the world’s biggest developing country and ${\mathrm{{CO}}}_{2}$ emitter, China’s new voluntary pledge-i.e., to achieve carbon neutrality in 2060-would contribute the lion’s share of the reductions of ${\mathrm{{CO}}}_{2}$ emissions world-wide. In comparative perspective, the deadline that China sets for itself to achieve carbon neutrality is very tight. Whereas the EU has planned to spend 70 years from carbon emissions peak to carbon neutrality, and the United States 45 years, China only gives itself a 30- year transition period. The task is daunting. To illustrate, in 2019, fossil fuels still accounted for about 85% of China’s energy structure, of which coal was 58%, the country’s carbon emission per capital remained 46% higher than the world average; and total ${\mathrm{{CO}}}_{2}$ emissions about ${29}\%$ of the world’s total. For China to peak carbon emissions prior to 2030 and achieve carbon neutrality in 2060, it must move aggressively to de-carbonize ${}^{5}$ its economy in the year ahead—indeed much more aggressively than the developed countries.
作为世界上最大的发展中国家和${\mathrm{{CO}}}_{2}$排放国,中国新的自愿承诺——即在2060年实现碳中和——将在全球${\mathrm{{CO}}}_{2}$减排中占据最大份额。相比之下,中国设定的实现碳中和的期限非常紧迫。欧盟计划从碳排放峰值到碳中和需要70年,美国需要45年,而中国给自己的过渡期只有30年。任务艰巨。举例来说,2019年,化石燃料在中国能源结构中仍占约85%,其中煤炭占58%,中国的人均碳排放量仍比世界平均水平高46%;${\mathrm{{CO}}}_{2}$排放总量约占世界总量的${29}\%$。中国要在2030年前实现碳排放达峰并在2060年实现碳中和,就必须在未来大力推动经济${}^{5}$脱碳,而且力度要远超发达国家。
(a) What are the available strategies of carbon emission reduction in China to achieve carbon neutrality by 2060?
(a) 中国为在2060年实现碳中和可采用的碳排放减少策略有哪些?
(b) What are the effects of different mitigation strategies on carbon emission, energy demand and macro economy?
(b) 不同减排策略对碳排放、能源需求和宏观经济有哪些影响?
(c) Whether can China achieve carbon neutrality by 2060 through the current available strategies and at what cost?
(c) 中国能否通过当前可用策略在2060年实现碳中和,成本是多少?
To try to answer the above questions systematically, we have developed a conceptual framework of PPA + MBA + CCS + NBS, so as to delineate the parameters of our model building.
为了尝试系统地回答上述问题,我们构建了一个“PPA + MBA + CCS + NBS”的概念框架,以勾勒我们模型构建的参数。
4 The Ministry of Environmental Protection from 2009 publishes the China’s Climate Change Policy and Action Annual Report annually.
4 环境保护部自2009年起每年发布《中国气候变化政策与行动年度报告》。
${}^{5}$ Carbon removal or decarbonization is a term that includes many forms of carbon removal from the atmosphere, whether through land sequestration or through negative emissions technologies that actively pull ${\mathrm{{CO}}}_{2}$ out of the atmosphere, such as direct air capture or biomass energy with carbon capture and storage.
${}^{5}$ 碳去除或脱碳是一个术语,包括从大气中去除碳的多种形式,无论是通过陆地封存还是通过积极从大气中提取${\mathrm{{CO}}}_{2}$的负排放技术,如直接空气捕获或碳捕获与封存的生物质能源。
2 Section 2
2 第2节
2.1 A Conceptual Framework: PPA + MBA + CCS + NBS
2.1 一个概念框架:电力购买协议(PPA)+基于市场的方法(MBA)+碳捕获与封存(CCS)+基于自然的解决方案(NBS)
Concept is critical in generating knowledge from experience. Or the world would remain too chaotic for us to understand. The fewer fundamental concepts that lies at the base of a science, the higher the level knowledge to which it raises us. Add actual context, we practice in the real world. Call it theoria cum praxi philosophically. There are essentially four approaches regarding mitigation and adaptation to the impact of climate change. They are: public policy approach (PPA), market-based approach (MBA), carbon capture and storage (CCS), and nature-based solutions (NBS). Let us elaborate a bit more on each of them, starting backwards from NBS.
概念对于从经验中产生知识至关重要。否则,世界将仍然过于混乱,让我们无法理解。一门科学所基于的基本概念越少,它将我们提升到的知识水平就越高。加上实际背景,我们在现实世界中实践。从哲学角度称其为理论与实践相结合。关于缓解和适应气候变化影响,本质上有四种方法。它们是:公共政策方法(PPA)、基于市场的方法(MBA)、碳捕获与封存(CCS)以及基于自然的解决方案(NBS)。让我们从基于自然的解决方案(NBS)开始,对它们逐一进行更详细的阐述。
Nature-Based Solution (NBS)
基于自然的解决方案(NBS)
The International Union for the Conservation of Nature (IUCN) defines nature-based solution (NBS) as actions to protect, sustainably manage, and restore natural or modified ecosystems that support the achievement of society’s development goals and address major societal challenges, such as climate change, food security, water security, human health, disaster risk, etc. ${}^{6}$
国际自然保护联盟(IUCN)将基于自然的解决方案(NBS)定义为保护、可持续管理和恢复自然或经改造的生态系统的行动,这些行动有助于实现社会发展目标并应对重大社会挑战,如气候变化、粮食安全、水安全、人类健康、灾害风险等。${}^{6}$
In climate change, NBS has been recognized as an important measure to help and protect human beings from the impact of climate change while slowing down further warming (Cohen-Shacham et al., 2016; Nature, 2017). Forests, as the main resource of NBS, sequester ${\mathrm{{CO}}}_{2}$ as trees grow and have potential to mitigate the impact of climate change (Bellassen & Luyssaert, 2014). Xu et al. (2020) provides the estimate of China’s forest carbon sequestration potential. Based on their estimation, by the end of 2050, the carbon sinks of the existing forest in 2050 will be 1.54 billion tons/year. He et al. (2020)’s prediction is much lower than Xu et al. (2020)’s estimation. According to their research, China’s forest carbon sequestration will be 700 million tons/year by 2050. The reason for the difference is the emission reduction effect of wood products does not enter into He et al. (2020)’s prediction.
在气候变化方面,NBS已被视为帮助和保护人类免受气候变化影响同时减缓进一步变暖的一项重要措施(科恩 - 沙查姆等人,2016年;《自然》,2017年)。森林作为NBS的主要资源,随着树木生长固存${\mathrm{{CO}}}_{2}$,并具有减轻气候变化影响的潜力(贝拉萨恩和吕萨尔,2014年)。徐等人(2020年)提供了中国森林碳固存潜力的估计。根据他们的估计,到2050年底,2050年现有森林的碳汇将达到每年15.4亿吨。何等人(2020年)的预测远低于徐等人(2020年)的估计。根据他们的研究,到2050年中国的森林碳固存将为每年7亿吨。差异的原因是木制品的减排效应未纳入何等人(2020年)的预测。
${\mathrm{{CO}}}_{2}$ Capture and Storage (CCS)
${\mathrm{{CO}}}_{2}$ 捕集与封存(CCS)
${\mathrm{{CO}}}_{2}$ capture and storage (CCS), as our previous chapters have explained, refers to the process that carbon dioxide is separated from industrial or related emission sources, transported to storage sites, and isolated from the atmosphere. In recent years, China has ramped up the R&D of CCUS (carbon capture, utilization and storage) through the National Basic Research Program of China (aka., 972 Program), the National Hi-Tech Research and Development Program of China (aka., 863 Program), and National Science and Technology Support Program. One illustration of the “U” part ( ${\mathrm{{CO}}}_{2}$ utilization) is ${\mathrm{{CO}}}_{2}$ -EOR (enhanced oil recovery) technology, which, if successful, could result in negative ${\mathrm{{CO}}}_{2}$ emissions. It injects ${\mathrm{{CO}}}_{2}$ into an underground geologic zone that contains hydrocarbons to produce more oil. So far there are about 30 CCS/CCUS pilot or demonstration projects either already in operation or under construction in China, and mostly in oil fields and coal-fired power plants.
${\mathrm{{CO}}}_{2}$ 捕集与封存(CCS),正如我们之前章节所解释的,是指将二氧化碳从工业或相关排放源中分离出来,运输到储存地点,并与大气隔离的过程。近年来,中国通过国家重点基础研究发展计划(即973计划)、国家高技术研究发展计划(即863计划)和国家科技支撑计划,加大了对CCUS(碳捕集、利用与封存)的研发力度。“U”部分(${\mathrm{{CO}}}_{2}$ 利用)的一个例子是${\mathrm{{CO}}}_{2}$ -EOR(强化采油)技术,如果成功,可能会实现负${\mathrm{{CO}}}_{2}$ 排放。它将${\mathrm{{CO}}}_{2}$ 注入含有碳氢化合物的地下地质区域以生产更多石油。到目前为止,中国大约有30个CCS/CCUS试点或示范项目已在运行或正在建设中,且大多位于油田和燃煤电厂。
${}^{6}$ https://www.iucn.org/commissions/commission-ecosystem-management/our-work/nature-based-solutions.
${}^{6}$ https://www.iucn.org/commissions/commission-ecosystem-management/our-work/nature-based-solutions.
CCS is not only a large-scale ${\mathrm{{CO}}}_{2}$ emission reduction technology with great potentials, but also the only technology available that can deliver large-scale direct emission reductions for energy-intensive industries, and with minimal restructuring costs on existing energy structure. Bioenergy with ${\mathrm{{CO}}}_{2}$ capture and storage (BECCS) is the installation of CCS technology in the biological processing industry or biofuel power plants. Both CCS and BECCS create negative carbon emissions. As He et al. (2020) estimate that the carbon sink of CCS and BECCS technology in China would be 510 million tons and 880 million tons in 2050 under ${1.5}^{ \circ }\mathrm{C}$ and ${2}^{ \circ }\mathrm{C}$ scenarios, respectively. At present, however, the biggest hurdle is the prohibitively high cost for CCS, estimated at $200-300 tCO2. As 1 ton of coal would produce roughly 2 tons of ${\mathrm{{CO}}}_{2}$ , it means that it would cost well over $\$ {400}$ to sequester ${\mathrm{{CO}}}_{2}$ emissions from the burning of 1 ton of coal.
CCS不仅是一种具有巨大潜力的大规模${\mathrm{{CO}}}_{2}$ 减排技术,也是唯一能够为能源密集型行业实现大规模直接减排且对现有能源结构进行最小化重组成本的技术。带有${\mathrm{{CO}}}_{2}$ 捕集与封存的生物能源(BECCS)是在生物加工行业或生物燃料发电厂安装CCS技术。CCS和BECCS都能产生负碳排放。正如He等人(2020年)估计,在${1.5}^{ \circ }\mathrm{C}$ 和${2}^{ \circ }\mathrm{C}$ 情景下,中国CCS和BECCS技术的碳汇在2050年将分别达到5.1亿吨和8.8亿吨。然而,目前最大的障碍是CCS成本高得令人望而却步,估计为每吨二氧化碳200 - 300美元。由于1吨煤大约会产生2吨${\mathrm{{CO}}}_{2}$ ,这意味着封存1吨煤燃烧产生的${\mathrm{{CO}}}_{2}$ 排放成本将超过$\$ {400}$ 。
Market-Based Approach (MBA)
基于市场的方法(MBA)
On way to understand how market-based approach (MBA) works to drive decarbonization is carbon markets, or known in Europe as emission trading systems (ETS). Broadly speaking, ETS can be understood as a financial way to internalize environmental benefits when investing in sustainable energy systems. ETS contributes to economic efficiency by facilitating ${\mathrm{{CO}}}_{2}$ emission reductions where it is cheapest to achieve them. Polluters or emitters who would find it costly to reduce their emissions are allowed to buy emission allowances from polluters or emitters who can abate at lower costs. In a “perfectly” market, the costs associated with reducing an additional unit of emissions would be equalized, and total costs of reaching a given environmental or climate target would be minimized. As discussed in the previous chapters, China started 7 regional ETS pilots in 2011 (in Beijing, Chongqing, Guangdong, Shanghai, Shenzhen, Tianjin, and Hubei), and a national ETS in 2017, although the national ETS covers only the power sector so far but is expected to expand its coverage years down the road.
理解基于市场的方法(MBA)如何推动脱碳的一个途径是碳市场,在欧洲被称为排放交易体系(ETS)。广义而言,ETS可以被理解为一种在投资可持续能源系统时将环境效益内部化的金融方式。ETS通过在减排成本最低的地方促进${\mathrm{{CO}}}_{2}$减排来提高经济效率。那些发现减排成本高昂的污染者或排放者被允许从能够以较低成本减排的污染者或排放者那里购买排放配额。在一个“完美”的市场中,与减少额外一单位排放相关的成本将趋于均衡,实现给定环境或气候目标的总成本将降至最低。如前几章所述,中国在2011年启动了7个区域ETS试点(在北京、重庆、广东、上海、深圳、天津和湖北),并于2017年启动了全国性ETS,尽管目前全国性ETS仅覆盖电力部门,但预计未来几年其覆盖范围将扩大。
Another example of MBA is green bonds. Green bonds can enable fund-raising and investment for both existing and new projects with environmental benefits, e.g., CCS technology presumably in the years ahead. Market principles of information disclosure and transparency are critical in developing green bond markets. They help potential investors by ensuring availability of information necessary to evaluate the environmental impact of their investments; and they also assist underwriters by moving the market towards standard disclosures which can facilitate transactions. In December 2015, China’s green bond market was launched, when the People’s Bank of China (PBOC) first came out with a catalogue of green projects and introduced green bonds in the interbank bond market. Subsequently, a total of 9 market pilots were rolled out for China to test the ground and learn from experience of green finance, including green loans, green bonds, and green insurance. At represent, PBOC is considering upgrading the green bond catalogue by removing fossil fuel projects and working with international counterparts to align green taxonomies.
MBA的另一个例子是绿色债券。绿色债券可以为具有环境效益的现有和新项目筹集资金并进行投资,例如,可能在未来几年的碳捕集与封存技术。信息披露和透明度的市场原则在发展绿色债券市场中至关重要。它们通过确保提供评估投资环境影响所需的信息来帮助潜在投资者;它们还通过推动市场采用标准化披露来协助承销商,这有助于促进交易。2015年12月,中国绿色债券市场启动,当时中国人民银行(PBOC)首次发布了绿色项目目录,并在银行间债券市场引入了绿色债券。随后,中国共推出了9个市场试点,以进行探索并借鉴绿色金融的经验,包括绿色贷款、绿色债券和绿色保险。目前,中国人民银行正在考虑升级绿色债券目录,剔除化石燃料项目,并与国际同行合作协调绿色分类标准。
Public Policy Approach (PPA)
公共政策方法(PPA)
An extensive literature exists, both theoretical and empirical, that supports the argument that when externalities exist, public policy becomes powerful instruments to correct market failures. Combating externalities-of which ${\mathrm{{CO}}}_{2}$ emissions, water pollutions and environmental degradations are textbook examples is a legitimate arena for government intervention using what we call public policy approach (PPA). The argument is all more compelling when the ecosystem on Earth is at stake. To deal with externalities or market failures, PPA instruments essentially include (a) a Tax, (b) a Subsidy, (c) a Restriction, Standard, Target or Quota.
存在大量的理论和实证文献,支持这样一种观点,即当存在外部性时,公共政策成为纠正市场失灵的有力工具。应对外部性——${\mathrm{{CO}}}_{2}$排放、水污染和环境退化是典型例子——是政府使用我们所称的公共政策方法(PPA)进行干预的合理领域。当地球的生态系统受到威胁时,这种观点更具说服力。为了应对外部性或市场失灵,PPA工具主要包括:(a) 税收,(b) 补贴,(c) 限制、标准、目标或配额。
Experts have identified a number of policy instruments that are efficacious in restricting or reducing carbon emission (Gallagher et al., 2019). In addition to national emission-trading system (ETS) and green bonds, which we have discussed under market-based approach (MBA), ${}^{7}$ the policy instruments include:
专家们已经确定了一些在限制或减少碳排放方面有效的政策工具(加拉格尔等人,2019年)。除了我们在基于市场的方法(MBA)下讨论过的国家排放交易体系(ETS)和绿色债券外,${}^{7}$这些政策工具还包括:
Subsidies for renewable energy (feed-in tariffs).
对可再生能源的补贴(上网电价)。
Energy efficiency policies for power plants.
发电厂的能源效率政策。
Non-fossil targets
非化石目标
Coal cap policies
煤炭总量控制政策
${}^{7}$ Note that at the fundamental level this categorization is debatable. For example, in the scheme of “cap and trade” of ${\mathrm{{CO}}}_{2}$ emissions in ETS, the “cap” is ultimately set by the government and then the firm get to “trade”. And arguably, to the extent that ETSs in China are still in the piloting stage and carbon pricing is still subject to government guidance, they can be discussed generally under PPA as well. More pointedly, in a transitional economy like China’s, whether or not to set up these markets can be understood as a public policy choice.
${}^{7}$请注意,从根本层面上讲,这种分类是有争议的。例如,在ETS中${\mathrm{{CO}}}_{2}$排放的“总量控制与交易”计划中,“总量控制”最终是由政府设定的,然后企业进行“交易”。可以说,鉴于中国的ETS仍处于试点阶段,碳定价仍受政府指导,它们也可以在PPA下进行总体讨论。更确切地说,在像中国这样的转型经济体中,是否建立这些市场可以被理解为一种公共政策选择。
Energy efficiency standards for buildings and equipment.
建筑和设备的能源效率标准。
Key enterprise programs.
重点企业计划。
Economic structural reforms.
经济结构改革。
Removing fossil fuel subsidies.
取消化石燃料补贴。
Energy intensity targets
能源强度目标
Air pollution standards
空气污染标准
Differentiated electricity tariffs.
差别电价。
Phasing out old and inefficient power plants.
淘汰老旧低效发电厂。
Electricity sector reform.
电力部门改革。
Innovation policies
创新政策
Environmental resource tax
环境资源税
Note that when we reviewed China’s evolving regulatory framework for a low-carbon economy in Chapters 1 and 2 of this study, we found that the variants of these public policy tools listed above have all existed in China. For the purposes of the current study, we put these policy instruments under PPA, and sum them up into three major categories of strategies, i.e., energy efficiency enhancement, cost reduction in energy renewables, and market inclusion and carbon pricing. Below, we elaborate a bit more on them one by one.
请注意,在本研究的第1章和第2章中,当我们审视中国不断演变的低碳经济监管框架时,我们发现上述这些公共政策工具的变体在中国均已存在。就本研究而言,我们将这些政策工具归入公共政策方法(PPA),并将它们归纳为三大类战略,即提高能源效率、降低能源可再生成本以及市场纳入和碳定价。下面,我们将逐一详细阐述。
Energy Efficiency Enhancement
提高能源效率
Generally, carbon emission reduction is a low-carbon strategy, and can be achieved through improving efficient use of fossil energy and reducing the energy consumption of industrial sectors. This appears to be the predominant strategy China has deployed to achieve ${\mathrm{{CO}}}_{2}$ peak before 2030, and there is good reason. According to the statistics from World Bank, the energy intensity of primary energy in China is almost twice as much as German by 2015 (Fig. 1), which indicates China has huge potential to lower the energy intensity and increase utilization efficiency. Ding et al. (2019) calculate the energy intensity of China from 2000 to 2100 based on the change trend of energy intensity from 1980 to 2006. They predict that the annual energy intensity in China would decrease by 3.92% per year. Zhang et al. (2019) forecast the energy intensity for 41 industries of China from 2020 to 2030. They find that the energy intensity falls by 16.1% under scenario of no policy guidance and by 31.9% under scenario with policy guidance. Song et al. (2018) and Niu et al. (2016) make predictions about the energy intensity in China, too. According to above predictions, China’s future energy intensity change located in the range of $1\%$ to $4\%$ . The improvement in energy efficiency has played and will continue to play an important role in helping China peak ${\mathrm{{CO}}}_{2}$ emissions prior to 2030 and achieve carbon neutral in 2060.
一般来说,减少碳排放是一种低碳战略,可以通过提高化石能源的有效利用和降低工业部门的能源消耗来实现。这似乎是中国为在2030年前实现${\mathrm{{CO}}}_{2}$峰值而部署的主要战略,这是有充分理由的。根据世界银行的统计,到2015年,中国一次能源的能源强度几乎是德国的两倍(图1),这表明中国在降低能源强度和提高利用效率方面有巨大潜力。丁等人(2019年)根据1980年至2006年能源强度的变化趋势,计算了2000年至2]00年中国的能源强度。他们预测,中国的年能源强度将以每年3.92%的速度下降。张等人(2019年)预测了2020年至2030年中国41个行业的能源强度。他们发现,在没有政策指导的情况下,能源强度下降16.1%,在有政策指导的情况下,能源强度下降31.9%。宋等人(2018年)和牛等人(2016年)也对中国的能源强度进行了预测。根据上述预测,中国未来的能源强度变化在$1\%$到$4\%$的范围内。能源效率的提高在帮助中国在2030年前实现${\mathrm{{CO}}}_{2}$排放峰值和在2060年实现碳中和方面已经并将继续发挥重要作用。
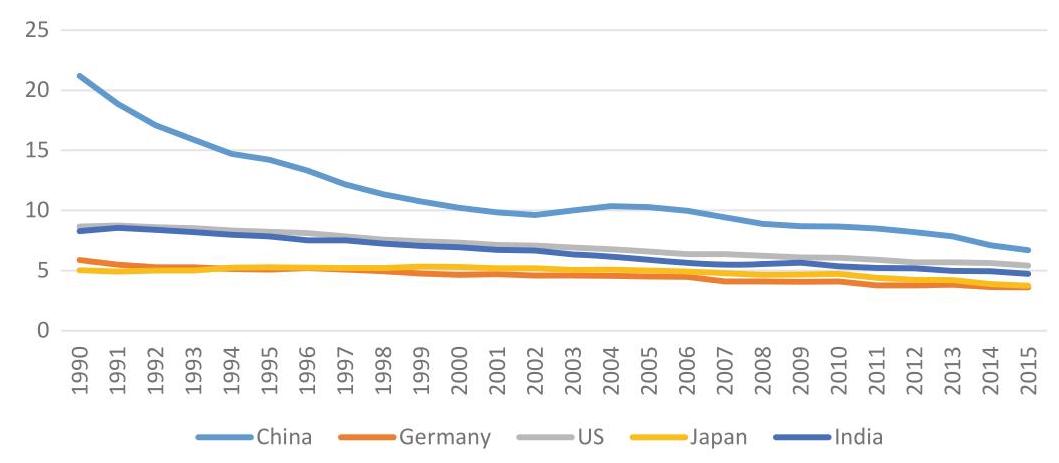
Fig. 1 Energy intensity: China, Germany, US, Japan and India (1990-2015). Source World Bank. Unit: MJ/$2011 PPP GDP
图1能源强度:中国、德国、美国、日本和印度(1990 - 2015年)。来源:世界银行。单位:兆焦/2011年购买力平价美元GDP
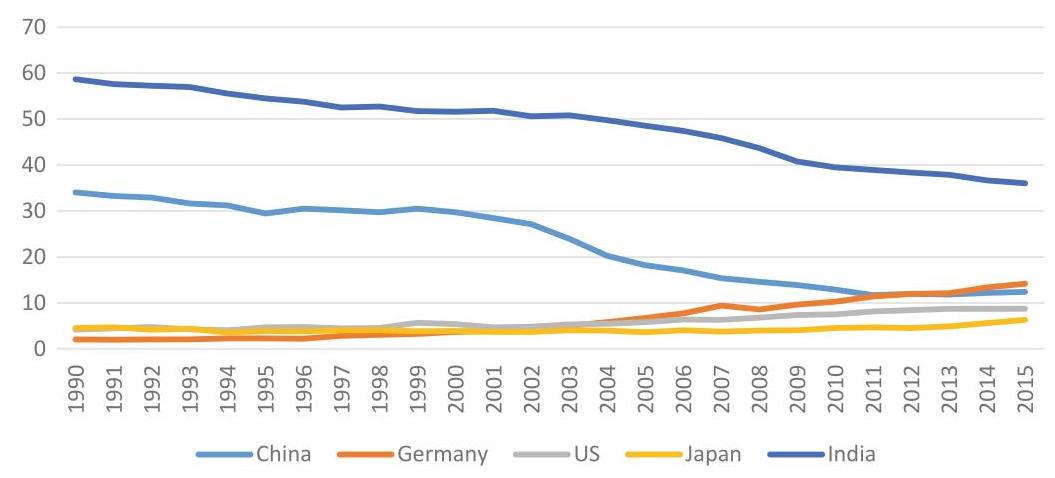
Fig. 2 Share of Renewable Energy: China, Germany, US, Japan and India (1990-2015). Source World Bank Unit: %
图2可再生能源占比:中国、德国、美国、日本和印度(1990 - 2015年)。来源:世界银行。单位:%
Cost Reduction in Renewable Energy
可再生能源成本降低
Ultimately, renewable energy is a technological path toward zero-carbon emissions. If a good strategy is a sequence of interconnected foci, then the strategic focus of zero-carbon emissions will have to be in place after China peaks ${\mathrm{{CO}}}_{2}$ emissions by 2030. In the meantime, the decline in the cost of renewable energy such as wind and solar energy as well as biomass energy will promote the transformation toward clean energy and achieve carbon emission reduction. China is experiencing a transition period from a firewood-dominated old era of renewable energies toward a wind energy-, solar energy- and biomass energy- dominated new era of renewable energies (Fig. 2). ${}^{8}$ Based on the estimation of He et al. (2020), the average cost for centralized photovoltaic solar panels, onshore wind energy and battery storage dropped by ${77}\% ,{35}\%$ and ${85}\%$ respectively from 2010-2018. Li et al (2020) finds that the cost of photovoltaic power generation has decreased from 100$/kwh in 1990 to 0.05$/kwh in 2020 and the annual decrease is as high as ${22.38}\%$ . Although China has strived to increase investment in R&D of renewables, the share of renewable energy in China is still below 20%. The aim of carbon neutral by 2060 will require a much lower renewable energy cost and a much higher the proportion of the use of renewable energy.
归根结底,可再生能源是实现零碳排放的技术路径。如果说一个好的战略是一系列相互关联的重点,那么在中国于 2030 年实现 ${\mathrm{{CO}}}_{2}$ 排放达峰后,就必须确定零碳排放的战略重点。与此同时,风能、太阳能以及生物质能等可再生能源成本的下降将推动向清洁能源转型,实现碳减排。中国正处于从以木柴为主的传统可再生能源时代向以风能、太阳能和生物质能为主的新时代的过渡期(图 2)。 ${}^{8}$ 根据何等人(2020 年)的估算,2010 - 2018 年期间,集中式光伏太阳能板、陆上风电和电池储能的平均成本分别下降了 ${77}\% ,{35}\%$ 和 ${85}\%$。李等人(2020 年)发现,光伏发电成本从 1990 年的 100 美元/千瓦时降至 2020 年的 0.05 美元/千瓦时,年降幅高达 ${22.38}\%$。尽管中国一直在努力增加对可再生能源研发的投入,但可再生能源在中国能源结构中的占比仍低于 20%。要实现 2060 年碳中和的目标,就需要大幅降低可再生能源成本,并大幅提高可再生能源的使用比例。
Market Inclusion and Carbon Pricing
市场纳入与碳定价
It is being widely adopted to promote carbon emission reduction by pricing carbon emission, such as imposing carbon taxes on industrial sectors and residents, establishing carbon markets (e.g. California’ cap and trade, EU’s emission-trading schemes or ETS). In 2011, China announced to launch seven regional ETS pilots in two provinces (Hubei and Guangdong) and five cities (Beijing, Shanghai, Shen-zhen, Tianjin and Chongqing). These regional ETS pilots are intended to gain experience associated with running carbon markets and to identify problems that should be resolved before moving to a nationwide carbon market. There have been many researches predicting the future carbon price in China.
通过对碳排放进行定价来促进减排的做法正在被广泛采用,例如对工业部门和居民征收碳税、建立碳市场(如加利福尼亚州的总量控制与交易制度、欧盟的排放交易计划或ETS)。2011年,中国宣布在两个省份(湖北和广东)和五个城市(北京、上海、深圳、天津和重庆)启动七个区域碳排放交易体系试点。这些区域碳排放交易体系试点旨在积累运营碳市场的经验,并找出在建立全国性碳市场之前需要解决的问题。已经有许多研究对中国未来的碳价格进行了预测。
In 2017, China rolled out a national carbon market but it only included the power sector. It is expected that over time the national market will also include other industrial sectors such as steel and cement, each contributing about 15% to the total industrial ${\mathrm{{CO}}}_{2}$ emissions in China, respectively. Yuan et al. (2020) estimates that the carbon price will reach the highest $\left( {{106.5}\$ /{\mathrm{{tCO}}}{2}}\right)$ by 2090 with reference to the future carbon price calculation formula of Wilkerson et al. (2015). The scenario given by Dong et al. (2017) show that the highest carbon price will reach ${120}$ /{\mathrm{{tCO}}}{2}$ . Above predictions are based on climate goal that China’s carbon emission would peak no later than 2030. The aim of carbon neutral by 2060 urges for higher carbon price levels. This is especially the case, if China eventually connects its domestic ETSs with global ETSs.
2017年,中国推出了全国性碳市场,但只涵盖了电力部门。预计随着时间的推移,全国市场还将纳入其他工业部门,如钢铁和水泥,它们在中国工业${\mathrm{{CO}}}_{2}$排放总量中所占比例分别约为15%。袁等人(2020年)根据威尔克森等人(2015年)的未来碳价格计算公式估计,如果参照该公式,到2090年碳价格将达到最高$\left( {{106.5}\$ /{\mathrm{{tCO}}}{2}}\right)$。董等人(2017年)给出的情景显示,最高碳价格将达到${120}$ /{\mathrm{{tCO}}}{2}$。上述预测是基于中国碳排放不晚于2030年达峰的气候目标。2060年实现碳中和的目标促使碳价格达到更高水平。如果中国最终将其国内排放交易体系与全球排放交易体系连接起来,情况尤其如此。
${}^{8}$ India is the highest in the proportion of renewable energy among the five countries in Fig. 2 as India is still dominated by firewood.
${}^{8}$ 在图2中的五个国家中,印度可再生能源的占比最高,因为印度仍以柴火为主。
3 Section 3
3 第3节
3.1 Model Construction and Scenarios Planning
3.1 模型构建与情景规划
To operationalize our PMCN (PPA + MBA + CCS + NBS) model, we draw upon the tool of recursive dynamic CGE model representing the Chinese economy, named CHINAGEM, ${}^{9}$ and fuse it with the parameters of the PMCN model. Before we proceed further, a word of CHINAGEM is in order. CHINAGEM has been widely used in the evaluations of economic and environmental policies in China. This model is capable of predicting the effect of macro policies on key aggregate indexes, such as GDP, price index, trade and other macroeconomic indicators, as well as industry-level outputs and prices. It contains 159 economic sectors, six economic subjects (manufacturers, investment, households, government, exports, and inventories), and nine distribution sectors (wholesale & retail, warehousing, insurance, rail transport, road transport, water transport, air transport, pipeline transport, transport services).
为了运行我们的PMCN(PPA + MBA + CCS + NBS)模型,我们采用了代表中国经济的递归动态CGE模型工具,即CHINAGEM,${}^{9}$ 并将其与PMCN模型的参数融合。在我们进一步展开之前,有必要先介绍一下CHINAGEM。CHINAGEM已在中国经济和环境政策评估中得到广泛应用。该模型能够预测宏观政策对关键总量指标的影响,如GDP、价格指数、贸易和其他宏观经济指标,以及行业层面的产出和价格。它包含159个经济部门、六个经济主体(制造商、投资、家庭、政府、出口和库存)以及九个分配部门(批发与零售、仓储、保险、铁路运输、公路运输、水路运输、航空运输、管道运输、运输服务)。
Carbon emissions from fossil fuel combustion and industrial production processes (excluding energy combustion) are modelled in CHINAGEM. The coefficients of carbon emissions used to calculate the carbon emission from fossil energy combustion are from IPCC AR5 (2014). China’s fossil energy emission from 2017 to 2020 is calibrated according to the IEA World Energy Outlook (2020). In the calculation of carbon dioxide emissions in the industrial production process, we mainly consider the emissions in the cement production, because it accounts for over 70% of the emissions from all the industrial production processes (excluding energy combustion). According to Shan et al. (2019), carbon emissions from cement production in China in 2017 were 7004.4 million tons.
CHINAGEM对化石燃料燃烧和工业生产过程(不包括能源燃烧)的碳排放进行了建模。用于计算化石能源燃烧碳排放的系数来自IPCC AR5(2014)。中国2017年至2020年的化石能源排放根据国际能源署《世界能源展望》(2020)进行了校准。在工业生产过程中二氧化碳排放的计算中,我们主要考虑水泥生产中的排放,因为它占所有工业生产过程(不包括能源燃烧)排放的70%以上。根据单等人(2019)的研究,2017年中国水泥生产的碳排放量为7.0044亿吨。
Carbon emission and production input are considered as the two main inputs of cement industry. In the CHINAGEM model, the emission reduction is described as the partial substitution relationship between carbon emission and production input. When the carbon price increases, the cement sector will reduce carbon emission and use more production inputs. In economic sense, cement producers will adopt more carbon reduction technologies when facing higher carbon price, but they will also face higher emission reduction cost. According to Hyman et al. (2002), the substitution elasticity of carbon emission and production input is set as 0.11 .
碳排放和生产投入被视为水泥行业的两个主要投入。在CHINAGEM模型中,减排被描述为碳排放与生产投入之间的部分替代关系。当碳价格上涨时,水泥行业将减少碳排放并使用更多生产投入。从经济意义上讲,水泥生产商在面临更高碳价格时将采用更多的碳减排技术,但他们也将面临更高的减排成本。根据海曼等人(2002)的研究,碳排放与生产投入的替代弹性设定为0.11。
Carbon emission accounts in the CHINAGEM model are based on fossil energy combustion and industrial production within the whole economic system. The carbon emission accounts are used to predict future carbon emissions in China through 2060.
CHINAGEM模型中的碳排放账户基于整个经济系统内的化石能源燃烧和工业生产。这些碳排放账户用于预测到2060年中国未来的碳排放。
${}^{9}$ CHINAGEM is developed by the policy research center of Victoria University, Australia.
${}^{9}$ CHINAGEM由澳大利亚维多利亚大学政策研究中心开发。
3.2 Set-Up of Model Parameters
3.2 模型参数设置
Based on the combination of the PMCN and CHINAGEM models, we analyze the strategic paths leading to net zero carbon emissions by 2060 in China, under several PPA scenarios, including carbon pricing. In setting up key parameters, we first construct the baseline scenario, covering China’s GDP, population, labor force and industrial macroeconomic structure from 2020 to 2060, based on the forecasts of the World Bank, CEPII and other international institutions. Second, drawing upon best estimates by the current studies, we take NBS (e.g., carbon sinks such as forests) and CCS as predetermined, and focus on PPA for decarbonization of industrial processes, either directly (e.g., deployment of (CCS) or indirectly (e.g., energy efficiency enhancement). According to the literature discussion in the previous section, we choose two carbon neutral targets for NBS and CCS-one conservative and one optimistic:
基于PMCN模型和CHINAGEM模型的结合,我们分析了在中国几种政策组合情景下(包括碳定价),到2060年实现净零碳排放的战略路径。在设置关键参数时,我们首先构建基线情景,该情景基于世界银行、CEPII等国际机构的预测,涵盖了2020年至2060年中国的国内生产总值、人口、劳动力和工业宏观经济结构。其次,根据当前研究的最佳估计,我们将国家自主贡献(如森林等碳汇)和碳捕获与封存视为既定条件,并将重点放在工业过程脱碳的政策组合上,这可以直接(如部署碳捕获与封存)或间接(如提高能源效率)实现。根据上一节的文献讨论,我们为国家自主贡献和碳捕获与封存选择了两个碳中和目标——一个保守目标和一个乐观目标:
(1) Conservative target: by 2060, NBS and CCS reaches 1.55 billion tons/year (i.e., 700 million tons (NBS) + 750 million tons (CCS)), implying China’s ${\mathrm{{CO}}}_{2}$ emissions need to be reduced to 1.55 billion tons by NBS and CCS in 2060, so that the carbon emissions and carbon sinks can be basically offset, reaching net zero carbon emission;
(1) 保守目标:到2060年,国家自主贡献和碳捕获与封存达到15.5亿吨/年(即7亿吨(国家自主贡献)+7.5亿吨(碳捕获与封存)),这意味着到2060年中国的${\mathrm{{CO}}}_{2}$排放量需要通过国家自主贡献和碳捕获与封存降至15.5亿吨,从而使碳排放和碳汇基本抵消,实现净零碳排放;
(2) Optimistic target: by 2060, NBS and CCS reaches 2.8 billion tons/year (i.e., 1.6 billion tons (NBS) + 1.2 billion tons (CCS)), implying that China’s ${\mathrm{{CO}}}_{2}$ emissions need to be reduced to be 2.8 billion tons by NBS and CCS in 2060, so that the carbon emissions and carbon sinks can be basically offset, reaching net zero carbon emissions.
(2) 乐观目标:到2060年,国家自主贡献和碳捕获与封存达到28亿吨/年(即16亿吨(国家自主贡献)+12亿吨(碳捕获与封存)),这意味着到2060年中国通过国家自主贡献和碳捕获与封存需要将${\mathrm{{CO}}}_{2}$排放量降至28亿吨,从而使碳排放和碳汇基本抵消,实现净零碳排放。
We subsume MBA (e.g., ETSs and green bonds) under PPA, because the future of these market-oriented pilots in China continues to be guided if not totally controlled by the government, although their expansions are expected to be sped up. Under PPA, the policy portfolios include three major categories, i.e., improvement in energy efficiency, cost reduction in renewable energy, and carbon pricing. In analyzing PPA efficacy, we consider the scenarios of single PPA and composite or comprehensive PPA.
我们将基于市场机制的政策工具(如排放交易体系和绿色债券)纳入政策组合,因为在中国,这些市场化试点的未来即使不完全受政府控制,也仍将受到政府引导,尽管预计它们的扩张速度会加快。在政策组合下,政策方案包括三大类,即提高能源效率、降低可再生能源成本和碳定价。在分析政策组合的效果时,我们考虑单一政策组合和复合或综合政策组合的情景。
3.3 Single PPA Scenarios
3.3 单一购电协议情景
(1) Improvement in energy efficiency
(1) 能源效率的提高
As the existing studies forecast that China’s improvement in energy efficiency will be concentrated in the range of $1\% - 4\%$ , we assume the overall energy intensity of industrial sectors decline by the average rate of ${0.5}\% ,1\% ,{1.5}\% ,2\% ,{2.5}\%$ and $3{\% }^{10}$ respectively and we simulate the corresponding policy scenarios.
由于现有研究预测中国能源效率的提高将集中在$1\% - 4\%$范围内,我们假设工业部门的总体能源强度分别以${0.5}\% ,1\% ,{1.5}\% ,2\% ,{2.5}\%$和$3{\% }^{10}$的平均速率下降,并模拟相应的政策情景。
(2) Cost reduction in renewable energy in China
(2) 中国可再生能源成本降低
For the cost reduction in renewable energy, we rely on the forecast of the International Energy Agency (IEA) on the future cost of photovoltaic and wind power generation. Considering that the power generation cost of renewable energy such as photovoltaic has been at a low level and the decline rate will gradually narrow in the future, we set two scenarios of cost reduction in renewable energy in China: one with high rate and the other with low rate. In the high rate of cost reduction scenario, it is assumed that the costs of solar photovoltaic, onshore wind power and offshore wind power decrease by ${3.25}\% ,{1.06}\%$ and ${4.27}\%$ respectively each year in 2020-2060. In the low rate of cost reduction scenario, the costs decrease by 1.62%, 0.53% and 2.13% respectively. At the same time, in the CHINAGEM model it is assumed that the government surcharges on fossil energy to promote the reduction of renewable energy cost.
对于可再生能源成本降低,我们依赖国际能源署(IEA)对未来光伏发电和风力发电成本的预测。考虑到光伏发电等可再生能源的发电成本已处于较低水平且未来下降速率将逐渐收窄,我们设定了中国可再生能源成本降低的两种情景:一种是高降低速率情景,另一种是低降低速率情景。在高降低速率情景下,假设2020 - 2060年期间太阳能光伏、陆上风电和海上风电成本每年分别下降${3.25}\% ,{1.06}\%$和${4.27}\%$。在低降低速率情景下,成本分别下降1.62%、0.53%和2.13%。同时,在CHINAGEM模型中假设政府对化石能源征收附加费以促进可再生能源成本降低。
Referring to the method of Dong et al. (2017), this study sets six scenarios of carbon pricing in which the carbon price in 2060 are 100, 200, 300, 400, 500 and ${600}\$ /{\mathrm{{tCO}}}_{2}$ respectively and assumes that the carbon price increases exponentially. At the same time, it is assumed that the carbon market will have included all major industrial sectors such as power, cement and steel, and that government will transfer all carbon emission tax revenue of carbon pricing policy to residents. The various single PPA scenarios are summarized in Table 1.
参照Dong等人(2017年)的方法,本研究设定了六种碳定价情景,其中2060年的碳价格分别为100、200、300、400、500和${600}\$ /{\mathrm{{tCO}}}_{2}$,并假设碳价格呈指数增长。同时,假设碳市场将涵盖电力、水泥和钢铁等所有主要工业部门,且政府将碳定价政策的所有碳排放税收入转移给居民。各种单一购电协议情景总结于表1。
3.4 Composite PPA Scenarios
3.4 综合电力购买协议方案
Scholars have proposed that composite or complex PPA portfolios give better results than single PPA for emission reduction. It is believed under composite or complex PPA portfolios the negative impact on the economy will be significantly reduced. For example, Song et al. (2018) find the policy combination can accelerate the peak time of carbon emission, so that China can reach the peak in 2026 when the annual GDP growth rate is not less than 5%. Lin and Jia (2019) also proposed that the simultaneous implementation of carbon trading, energy efficiency improvement, carbon sink and other emission reduction measures would help China reach the peak by 2030. Here, in a way that ranges from the optimistic approach of William Nordhaus (2007) to the pessimistic approach of Nicholas Sterns (2006) regarding global warming, ${}^{11}$ we test 72 PPA combinations of improvement in energy efficiency, cost reduction in renewable energy and carbon pricing, as shown in Table 2.
学者们提出,综合或复杂的电力购买协议组合在减排方面比单一电力购买协议能取得更好的效果。人们认为,在综合或复杂的电力购买协议组合下,对经济的负面影响将显著降低。例如,宋等人(2018年)发现,政策组合可以加速碳排放峰值时间的到来,从而使中国在2026年实现峰值,届时年国内生产总值增长率不低于5%。林和贾(2019年)也提出,同时实施碳交易、提高能源效率、碳汇等减排措施将有助于中国在2030年前达到峰值。在此,我们以从威廉·诺德豪斯(2007年)对全球变暖的乐观态度到尼古拉斯·斯特恩斯(2006年)的悲观态度的方式,${}^{11}$测试了72种提高能源效率、降低可再生能源成本和碳定价的电力购买协议组合,如表2所示。
${}^{10}$ To be conservative, we do not select 3.5% and 4% as the decline rate.
${}^{10}$ 为了保守起见,我们不选择3.5%和4%作为下降率。
Table 1 Single PPA scenarios
表1单一购电协议情景
| Strategy | Abbr | Shock | Literature | |
| Improvement in energy efficiency | E | E1 | 0.5% | Ding et al. (2019) |
| E2 | 1% | Zhang et al. (2019) | ||
| E3 | 1.5% | Yuan et al. (2014) Song et al. (2018) | ||
| E4 | 2% | Niu et al. (2016) | ||
| R | E5 | 2.5% | ||
| E6 | 3% | |||
| Cost reduction in renewable energy | R1 | high rate | He et al. (2020) | |
| R2 | low rate | Li (2020) IEA (2020) | ||
| Carbon pricing | T | T1 | 100\$/t ${\mathrm{{CO}}}_{2}$ | Duan et al. (2018) Yuan et al. (2020) Wilkerson et al. (2015) Dong et al. (2017) |
| T2 | 200\$/t ${\mathrm{{CO}}}_{2}$ | |||
| T3 | 300\$/t ${\mathrm{{CO}}}_{2}$ | |||
| T4 | 400\$/t ${\mathrm{{CO}}}_{2}$ | |||
| T5 | 500\$/t ${\mathrm{{CO}}}_{2}$ | |||
| T6 | 600\$/t ${\mathrm{{CO}}}_{2}$ | |||
${}^{11}$ Generally, Nordhaus assumes a high discount rate between the present and the future and therefore proposes a more gradual carbon tax than Stern, who assumes a lower discount rate and advocates stronger and immediate action.
${}^{11}$ 一般来说,诺德豪斯假定当前与未来之间的贴现率较高,因此他提议的碳税比斯特恩更为渐进,后者假定的贴现率较低,主张采取更强有力且即时的行动。
Table 2 Composite PPA Scenarios
表2 综合电力购买协议情景
| Scenarios | R | A | T | Scenarios | R | A | T |
| 1 | R1 | A6 | T6 | 37 | R2 | A6 | T6 |
| 2 | R1 | A6 | T5 | 38 | R2 | A6 | T5 |
| 3 | R1 | A6 | T4 | 39 | R2 | A6 | T4 |
| 4 | R1 | A6 | T3 | 40 | R2 | A6 | T3 |
| 5 | R1 | A6 | T2 | 41 | R2 | A6 | T2 |
| 6 | R1 | A6 | T1 | 42 | R2 | A6 | T1 |
| 7 | R1 | A5 | T6 | 43 | R2 | A5 | T6 |
| 8 | R1 | A5 | T5 | 44 | R2 | A5 | T5 |
| 9 | R1 | A5 | T4 | 45 | R2 | A5 | T4 |
| 10 | R1 | A5 | T3 | 46 | R2 | A5 | T3 |
| 11 | R1 | A5 | T2 | 47 | R2 | A5 | T2 |
| 12 | R1 | A5 | T1 | 48 | R2 | A5 | T1 |
| 13 | R1 | A4 | T6 | 49 | R2 | A4 | T6 |
| 14 | R1 | A4 | T5 | 50 | R2 | A4 | T5 |
| 15 | R1 | A4 | T4 | 51 | R2 | A4 | T4 |
| 16 | R1 | A4 | T3 | 52 | R2 | A4 | T3 |
| 17 | R1 | A4 | T2 | 53 | R2 | A4 | T2 |
| 18 | R1 | A4 | T1 | 54 | R2 | A4 | T1 |
| 19 | R1 | A3 | T6 | 55 | R2 | A3 | T6 |
| 20 | R1 | A3 | T5 | 56 | R2 | A3 | T5 |
| 21 | R1 | A3 | T4 | 57 | R2 | A3 | T4 |
| 22 | R1 | A3 | T3 | 58 | R2 | A3 | T3 |
| 23 | R1 | A3 | T2 | 59 | R2 | A3 | T2 |
| 24 | R1 | A3 | T1 | 60 | R2 | A3 | T1 |
| 25 | R1 | A2 | T6 | 61 | R2 | A2 | T6 |
| 26 | R1 | A2 | T5 | 62 | R2 | A2 | T5 |
| 27 | R1 | A2 | T4 | 63 | R2 | A2 | T4 |
| 28 | R1 | A2 | T3 | 64 | R2 | A2 | T3 |
| 29 | R1 | A2 | T2 | 65 | R2 | A2 | T2 |
| 30 | R1 | A2 | T1 | 66 | R2 | A2 | T1 |
(continued)
(续)
Table 2 (continued)
表2(续)
| Scenarios | R | A | T | Scenarios | R | A | T |
| 31 | R1 | A1 | T6 | 67 | R2 | A1 | T6 |
| 32 | R1 | A1 | T5 | 68 | R2 | A1 | T5 |
| 33 | R1 | A1 | T4 | 69 | R2 | A1 | T4 |
| 34 | R1 | A1 | T3 | 70 | R2 | A1 | T3 |
| 35 | R1 | A1 | T2 | 71 | R2 | A1 | T2 |
| 36 | R1 | A1 | T1 | 72 | R2 | A1 | T1 |
Note Renewable energy policy: R1 cost of renewable energy decreases rapidly, R2 cost of renewable energy decreases slowly; energy efficiency policy: A1 energy efficiency increases by ${0.5}\% /$ year, A2 energy efficiency increases by $1\% /$ year, A3 energy efficiency increases by 1.5%/year, A4 energy efficiency increases by 2%/year, A5 energy efficiency increases by 2.5%/year, A6 energy efficiency increases by 3%/year; carbon price policy: T1 ¥100/tCO2 in 2060, T2 ¥200/tCO2 in 2060, T3 ¥300/tCO2 in 2060, T4 ¥400/tCO2 in 2060, T5 ¥500/tCO2 in 2060, and T6 ¥600/tCO2 in 2060
注意,可再生能源政策:R1表示可再生能源成本迅速下降,R2表示可再生能源成本缓慢下降;能源效率政策:A1表示能源效率每年提高${0.5}\% /$,A2表示能源效率每年提高$1\% /$,A3表示能源效率每年提高1.5%,A4表示能源效率每年提高2%,A5表示能源效率每年提高2.5%,A6表示能源效率每年提高3%;碳价格政策:T1表示2060年碳价格为100元/吨二氧化碳,T2表示2060年碳价格为200元/吨二氧化碳,T3表示2060年碳价格为300元/吨二氧化碳,T4表示2060年碳价格为400元/吨二氧化碳,T5表示2060年碳价格为500元/吨二氧化碳,T6表示2060年碳价格为600元/吨二氧化碳
4 Section 4
4 第4节
4.1 Projection Results Under Different Scenarios
4.1不同情景下的预测结果
Under the baseline scenario, China’s total carbon emissions in 2060 are 8.812 billion tons, including 7.746 billion tons from fossil energy combustion.
在基准情景下,中国2060年的碳排放总量为88.12亿吨,其中化石能源燃烧排放77.46亿吨。
(1) Improvement in energy efficiency
(1) 能源效率的提高
Under single PPA scenarios—energy efficiency improvement, the energy use efficiency of the industry and the residential sector has been improved, which eventually reduces the demand for all energy products. The output of fossil energy sector drops significantly, which leads to a significant reduction of carbon emissions compared to the baseline scenario.
在单一购电协议情景下(即能源效率提高),工业和居民部门的能源使用效率得到提高,最终降低了对所有能源产品的需求。化石能源部门的产出大幅下降,与基准情景相比,碳排放显著减少。
The total carbon emissions are significantly reduced compared to the baseline scenario. By 2060, the total carbon emissions of the A1-A6 scenarios drop to 7.83 billion tons, 7.0 billion tons, 6.30 billion tons, 5.69 billion tons, 5.17 billion tons and 4.72 billion tons respectively (Fig. 3), which are reductions of 11.2-46.4%, as compared with the baseline scenario.
与基准情景相比,碳排放总量大幅减少。到2060年,A1 - A6情景下的碳排放总量分别降至78.3亿吨、70亿吨、63亿吨、56.9亿吨、51.7亿吨和47.2亿吨(图3),与基准情景相比减少了11.2% - 46.4%。
Carbon emissions may peak earlier than 2028, but they are still far from achieving the carbon neutral target in 2060 (Fig. 4).
碳排放可能在2028年之前达到峰值,但仍远未实现2060年的碳中和目标(图4)。
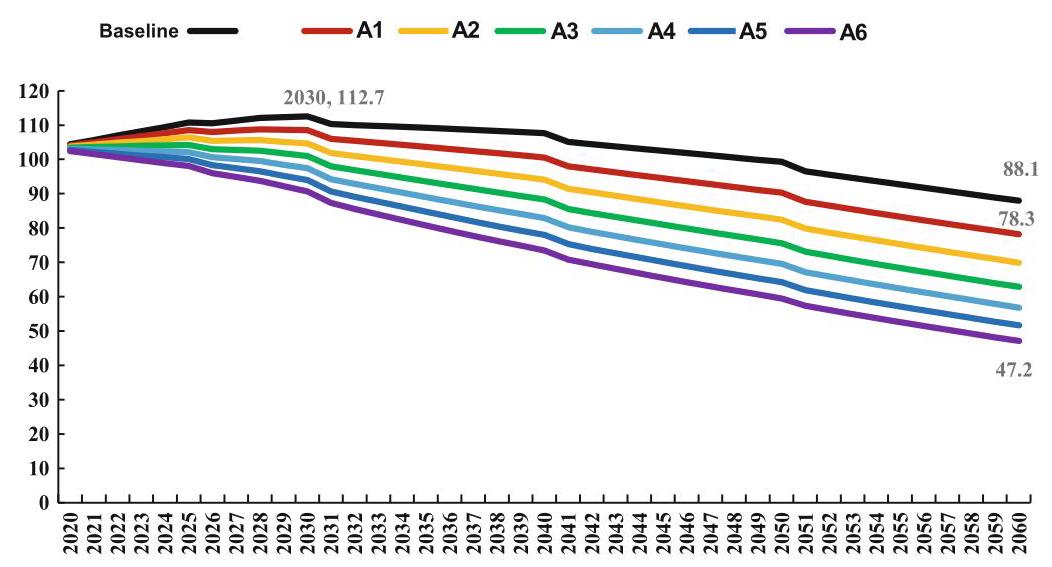
Fig. $3{\mathrm{{CO}}}_{2}$ emissions in China (2020-2060) by various scenarios of energy efficiency improvement (Unit: 0.1 billion tons) Note: A1 energy efficiency increase by 0.5%/year, A2 energy efficiency increase by 1%/year, A3 energy efficiency increase by 1.5%/year, A4 energy efficiency increase by $2\% /$ year, A5 energy efficiency increase by ${2.5}\% /$ year, A6 energy efficiency increase by $3\% /$ year
图$3{\mathrm{{CO}}}_{2}$ 中国在不同能源效率提高情景下的碳排放(2020 - 2060年)(单位:10亿吨) 注:A1能源效率每年提高0.5%,A2能源效率每年提高1%,A3能源效率每年提高1.5%,A4能源效率每年提高$2\% /$,A5能源效率每年提高${2.5}\% /$,A6能源效率每年提高$3\% /$
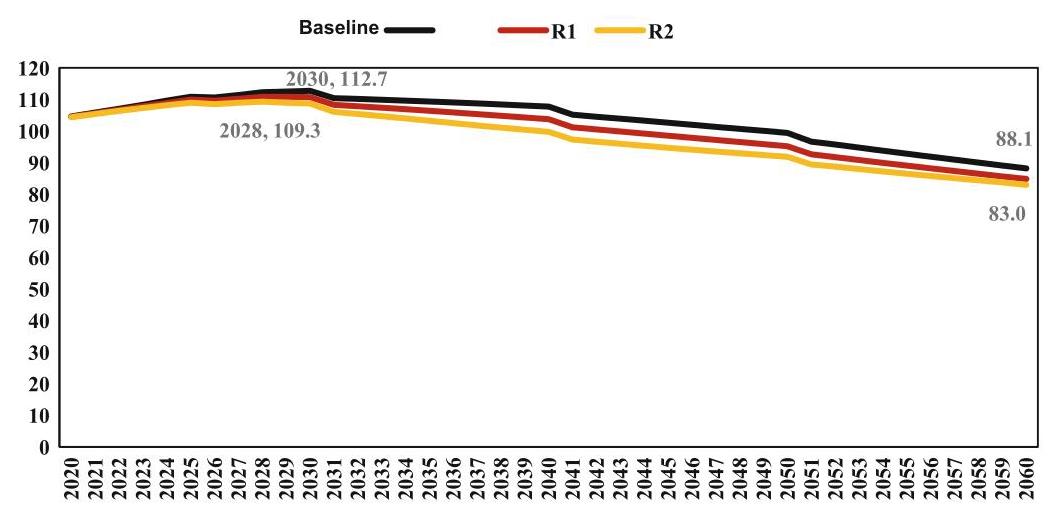
Fig. $4{\mathrm{{CO}}}_{2}$ Emissions in China (2020-2060) by various scenarios of renewable energy cost reduction (Unit: 0.1 billion tons) Note: R1 Cost of renewable energy decreases rapidly, R2 Cost of renewable energy decreases slowly
图$4{\mathrm{{CO}}}_{2}$ 中国在不同可再生能源成本降低情景下的碳排放(2020 - 2060年)(单位:10亿吨) 注:R1可再生能源成本迅速下降,R2可再生能源成本缓慢下降
(2) Cost reduction in renewable energy
(2) 可再生能源成本降低
In renewable energy cost reduction scenarios, the cost reduction of wind power, solar power and biomass power will reduce the average price of power, leading to the substitution of coal power and gas power and the reduction of fossil energy consumption. As shown in Fig. 4, by 2060, the emissions of low rate cost reduction (R1) and high rate cost reduction (R2) scenarios are 8.48 billion tons and 8.3 billion tons, respectively, which are reductions of 3.8% and 5.8% compared with the baseline. The emission reduction effect is weaker than that of the energy efficiency-improving scenarios, which is far from the carbon neutral target.
在可再生能源成本降低情景下,风电、太阳能发电和生物质发电的成本降低将降低电力平均价格,导致煤电和燃气发电被替代,化石能源消耗减少。如图4所示,到2060年,低速率成本降低(R1)和高速率成本降低(R2)情景的排放量分别为84.8亿吨和83亿吨,与基线相比分别减少3.8%和5.8%。减排效果弱于能源效率提高情景,远未达到碳中和目标。
(3) Market inclusion and carbon pricing
(3) 市场纳入与碳定价
In the scenario of increasing carbon tax, carbon emissions decrease to 7.93 billion tons, 7.51 billion tons, 7.19 billion tons, 6.94 billion tons, 6.73 billion tons and 6.55 billion tons in 2060, respectively (Fig. 5). Compared with the baseline in 2060, the emission reduction ranges from 880 million tons to 2.26 billion tons, which are reductions of 10.0-25.7%. The total emission differences among different carbon tax scenarios showed an increasing trend over time, possibly because that we set carbon tax to increase exponentially.
在碳税增加的情景下,2060年碳排放量分别降至79.3亿吨、75.1亿吨、71.9亿吨、69.4亿吨、67.3亿吨和65.5亿吨(图5)。与2060年的基线相比,减排量在8.8亿吨至22.6亿吨之间,降幅为10.0 - 25.7%。不同碳税情景下的总排放差异随时间呈上升趋势,可能是因为我们将碳税设定为指数增长。
(4) Composite PPA scenarios
(4) 综合电力采购协议情景
As shown in Fig. 6, the composite PPA effectively reduces China’s total carbon emissions from 2020 to 2060, but there is still a certain gap with the carbon neutral target in 2060. As previously mentioned, in 2060, China’s negative emissions from forest carbon sinks and CCS technologies will not exceed 3 billion tons. Therefore, the carbon neutral requires that the total carbon emissions in 2060 should be controlled within 3 billion tons. Under the most active combination of PPA instruments for emission reduction (R1T6A6), the total carbon emission in 2060 is 3.235 billion tons, which is 235 million tons higher than the 3 billion tons’ target (Fig. 6). As a conclusion, only relying on carbon price, energy efficiency and renewable energy policy instruments cannot meet the requirements of the 2060 carbon neutral target.
如图6所示,综合电力采购协议有效地减少了中国2020年至2060年的碳排放总量,但与2060年的碳中和目标仍有一定差距。如前所述,2060年中国森林碳汇和碳捕集与封存技术的负排放不会超过30亿吨。因此,碳中和要求2060年的碳排放总量应控制在30亿吨以内。在最积极的电力采购协议减排工具组合(R1T6A6)下,2060年的碳排放总量为32.35亿吨,比30亿吨的目标高出2.35亿吨(图6)。结论是,仅依靠碳价、能源效率和可再生能源政策工具无法满足2060年碳中和目标的要求。
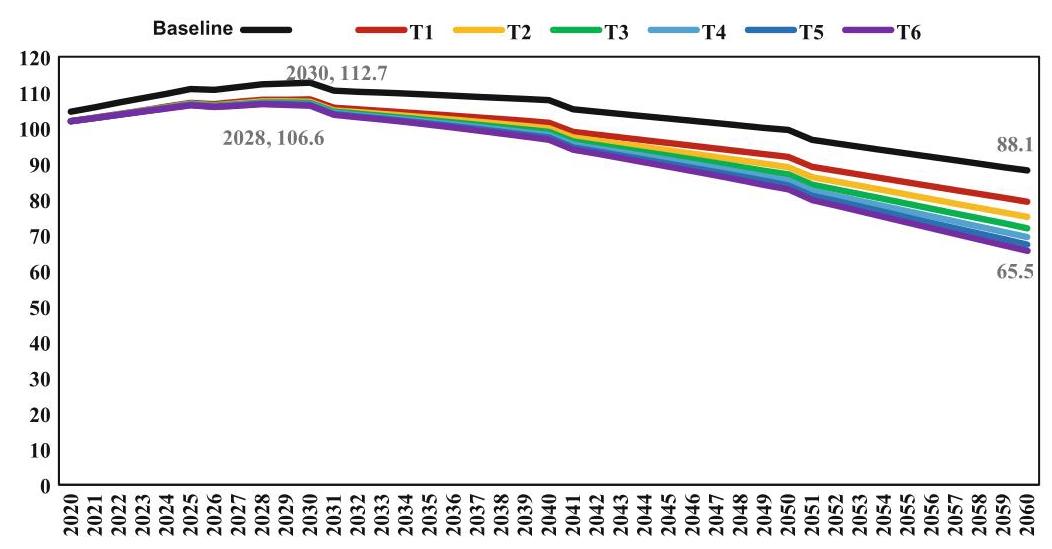
Fig. 5 ${\mathrm{{CO}}}_{2}$ Emissions in China (2020-2060) by various scenarios of carbon pricing (Unit: 0.1 billion tons). Note T1 $100/tCO2 in 2060, T2 $200/tCO2 in 2060, T3 $300/tCO2 in 2060, T4 $400/tCO2 in 2060, T5 $500/tCO2 in 2060, and T6 $600/tCO2 in 2060
图5 ${\mathrm{{CO}}}_{2}$ 不同碳定价情景下中国的排放量(2020 - 2060年)(单位:10亿吨)。注:T1为2060年100美元/吨二氧化碳,T2为2060年200美元/吨二氧化碳,T3为2060年300美元/吨二氧化碳,T4为2060年400美元/吨二氧化碳,T5为2060年500美元/吨二氧化碳,T6为2060年600美元/吨二氧化碳
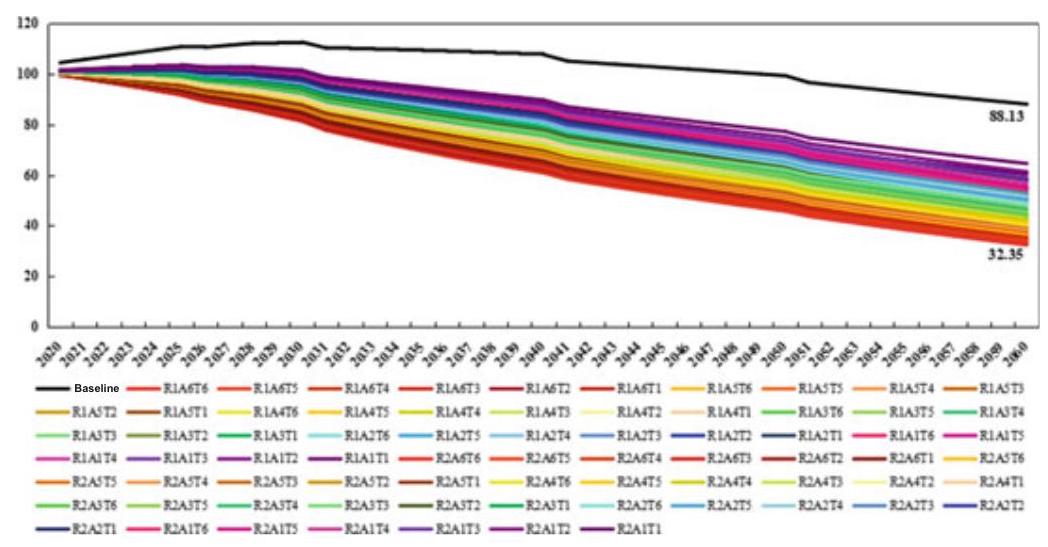
Fig. 6 ${\mathrm{{CO}}}_{2}$ Emissions in China (2020-2060) by various scenarios of policy portfolios (Unit: 0.1 billion tons). Note As an example, R1A6T6 indicates a combination of policy R1, A6 and T6
图6 ${\mathrm{{CO}}}_{2}$ 不同政策组合情景下中国的排放量(2020 - 2060年)(单位:10亿吨)。注:例如,R1A6T6表示政策R1、A6和T6的组合
4.2 Impact on Energy Structure
4.2 对能源结构的影响
Composite PPA rather than single PPA for emission reduction reshapes the future structure of energy demand more powerfully. In the baseline scenario, the energy demand in 2060 is 6.239 billion tons of standard coal, with coal accounted for 31.5%, renewable energy accounted for 35.9%, and oil, natural gas and nuclear energy accounted for 12.2%, 14.9% and 5.4% respectively (Fig. 7). Under composite PPA scenarios, the total energy demand in 2060 will decrease to 2.22-5.49 billion tons of standard coal. Renewable energy accounts for 27.3-77.5% of the total energy demand, while coal accounts for 8.1-41.6%, oil accounts for 11.4- 13.9%, natural gas accounts for 2.0-17.7%, and nuclear energy accounts for less than $4\%$ .
用于减排的复合电力购买协议(Composite PPA)而非单一电力购买协议(single PPA),对未来能源需求结构的重塑作用更为显著。在基准情景下,2060年的能源需求为62.39亿吨标准煤,其中煤炭占31.5%,可再生能源占35.9%,石油、天然气和核能分别占12.2%、14.9%和5.4%(图7)。在复合电力购买协议情景下,2060年的能源总需求将降至22.2 - 54.9亿吨标准煤。可再生能源占能源总需求的27.3% - 77.5%,而煤炭占8.1% - 41.6%,石油占11.4% - 13.9%,天然气占2.0% - 17.7%,核能占比小于$4\%$。
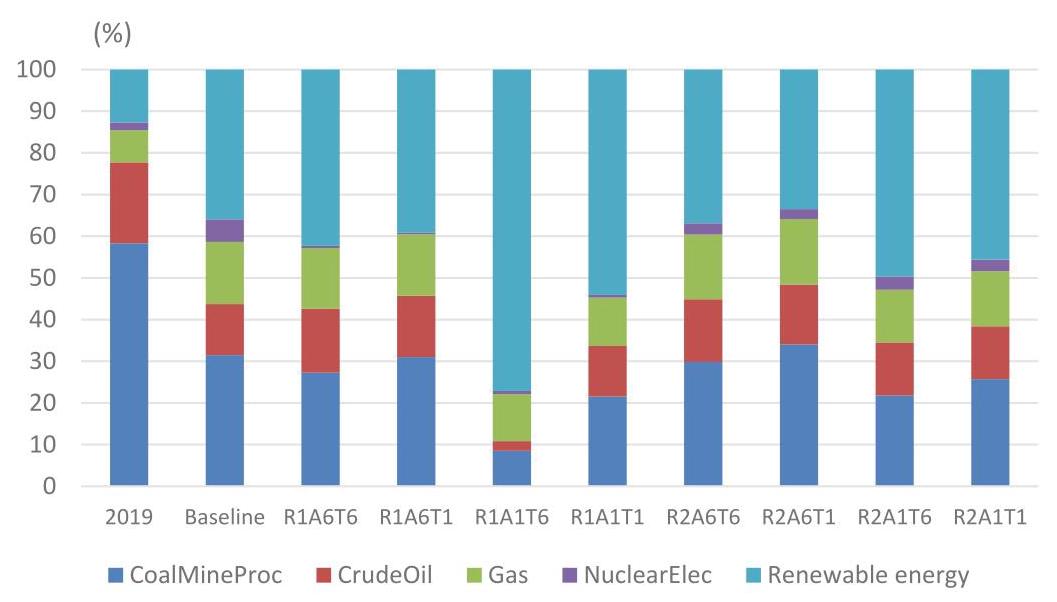
Fig. 7 Energy Structure in China in 2060 by various scenarios of policy portfolios (Unit: %)
图7 不同政策组合情景下2060年中国的能源结构(单位:%)
4.3 Impact on Economy
4.3 对经济的影响
Climate mitigation and adaptation comes at the cost of economic loss. We find that (1) GDP loss and emission reduction show an obvious positive correlation (Fig. 8). That is, to obtain greater carbon emission reduction, we need to bear greater GDP loss; (2) Compared with energy efficiency improvement and carbon price policies, the rapid cost reduction of renewable energy has higher emission reduction potential and smaller economic loss cost; (3) Based on the tradeoff between emission reduction benefits and economic loss, the policy combination of low energy efficiency improvement and high carbon price is better than that of high-energy efficiency improvement and low carbon price.
气候缓解和适应是以经济损失为代价的。我们发现:(1)国内生产总值损失与减排呈现明显的正相关关系(图8)。也就是说,要实现更大幅度的碳排放减少,我们需要承受更大的国内生产总值损失;(2)与提高能源效率和碳价格政策相比,可再生能源成本的快速下降具有更高的减排潜力和更小的经济损失成本;(3)基于减排效益与经济损失之间的权衡,低能源效率提升和高碳价格的政策组合优于高能源效率提升和低碳价格的政策组合。
Fig. 8 Tradeoff between ${\mathrm{{CO}}}_{2}$ Emission and GDP Loss in China in 2060, by various scenarios of policy portfolios Note Blue dot represents some one policy portfolio
图8 2060年中国在不同政策组合情景下${\mathrm{{CO}}}_{2}$排放与国内生产总值损失之间的权衡 注:蓝点代表某一种政策组合
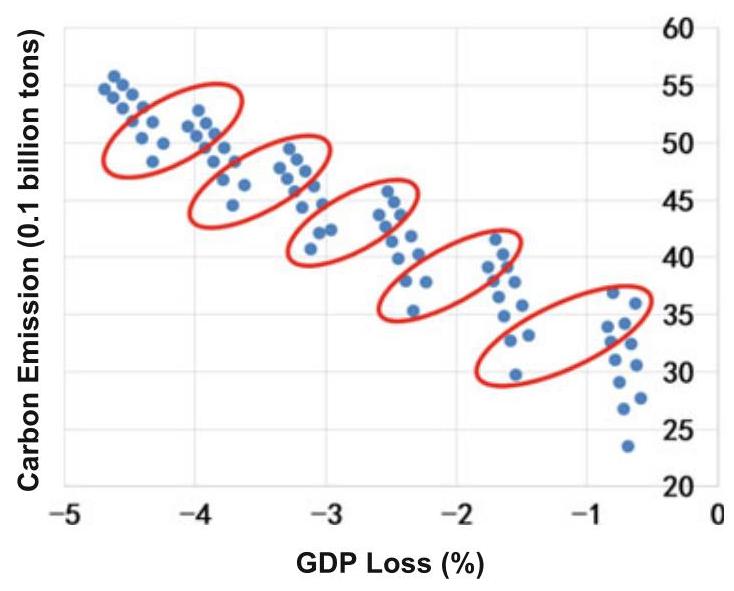
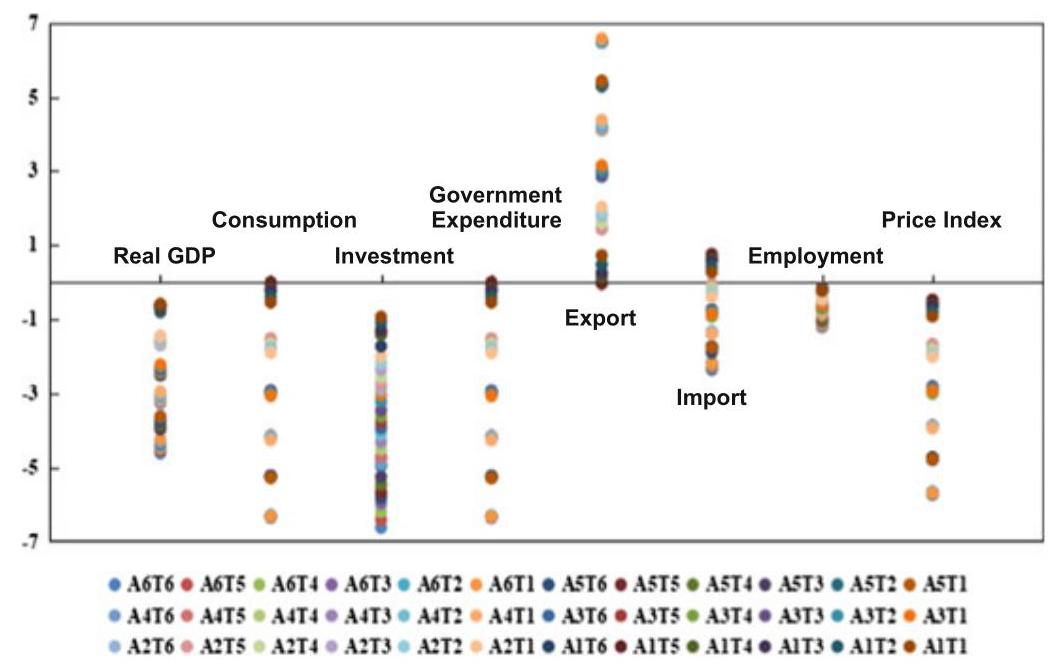
Fig. 9 Impact of policy portfolios on macroeconomic variables in China in 2060
图9 政策组合对2060年中国宏观经济变量的影响
For other macroeconomic variables (Fig. 9), we find that: (1) A complex PPA strategy for emission reduction significantly decreases the output of fossil energy sector; (2) Energy efficiency policy not only improves energy efficiency, but also reduces labor demand of industrial sector, and therefore leads to a decrease in total employment by a magnitude of 0.13-1.22%; (3) A complex PPA strategy increases the use cost of fossil energy and reduces the demand for fossil energy products, and thus reduces the investment in the fossil energy sector; (4) The loss of economy causes the decline of national income, which makes the consumption of residents and government expenditure decrease in different degrees; (5) The decline of energy demand reduces the price of energy products; (6) The export demand increases in almost all complex PPA scenarios but the import demand is the opposite. The lower price level has a pulling effect on export. Meanwhile, the rise of energy cost weakens the competitiveness of non-energy products, making the import of products increase.
对于其他宏观经济变量(图9),我们发现:(1)复杂的减排电力购买协议(PPA)策略显著降低了化石能源部门的产出;(2)能源效率政策不仅提高了能源效率,还减少了工业部门的劳动力需求,因此导致总就业量下降0.13 - 1.22%;(3)复杂的PPA策略增加了化石能源的使用成本,减少了对化石能源产品的需求,从而降低了对化石能源部门的投资;(4)经济损失导致国民收入下降,使得居民消费和政府支出不同程度减少;(5)能源需求下降降低了能源产品价格;(6)在几乎所有复杂的PPA情景中,出口需求增加,但进口需求则相反。较低的价格水平对出口有拉动作用。同时,能源成本上升削弱了非能源产品的竞争力,使得产品进口增加。
4.4 Concluding Remarks
4.4 结束语
Key Takeaways
关键要点
To achieve carbon neutral goal by 2060, improvement in energy efficiency, cost reduction in renewable energy and carbon pricing are all necessary, but not enough even in a combination of all above strategies. New policy instruments, especially for a more powerful shift from fossil to no-fossil fuels, are needed to achieve the carbon neutral goal in time.
为实现2060年碳中和目标,提高能源效率、降低可再生能源成本以及碳定价都是必要的,但即便将上述所有策略结合起来也仍显不足。需要新的政策工具,特别是要实现从化石燃料到非化石燃料的更有力转变,才能及时实现碳中和目标。
All the strategies of carbon emission reduction come at the cost of GDP loss, with modest declines in employment, investment, and consumption. Having said that, however, a better calibrated mix of policy instruments will take smaller costs of economic loss. In this study, we recommend the combinations of low energy efficiency improvement and high carbon price, including carbon taxation rather than campaign-style, across-the-board prohibition. ${}^{12}$ In other words, on balance, MBA is the preferred approach.
所有碳排放减少策略都会以GDP损失为代价,就业、投资和消费也会有适度下降。话虽如此,但经过更好校准的政策工具组合将使经济损失成本更小。在本研究中,我们建议采用低能源效率提升和高碳价的组合,包括碳税而非运动式的全面禁令。${}^{12}$ 换句话说,总体而言,边际减排成本是首选方法。
Combined PPA aiming at de-carbonization will reshape the future structure of energy demand dramatically. Renewable demand will increase and the fossil energy demand, especially coal demand, will decrease. Yet a caveat is in order here. Even in the most comprehensive of all PPA scenarios available today, by 2060, renewable energy will only accounts for less than 80% of the total energy consumption, ${}^{13}$ while fossil energy still accounts for more than ${20}\%$ . Promoting electric vehicle sector development and other forms of electrification would become especially important for further reductions in fossil energy demand. In this context, as a matter of rational strategic sequencing, priorities should be given for the electricity sector to achieve zero carbon ahead of end users, and it makes sense to include the electricity sector first in the country’s national carbon market.
旨在脱碳的联合电力采购协议(PPA)将极大地重塑未来能源需求结构。可再生能源需求将增加,化石能源需求,尤其是煤炭需求将减少。然而这里有一个需要注意的地方。即使在当今所有可用的最全面的PPA情景中,到2060年,可再生能源在总能源消费中的占比仍将不到80%,${}^{13}$ 而化石能源仍将占比超过${20}\%$ 。促进电动汽车行业发展和其他形式的电气化对于进一步减少化石能源需求将变得尤为重要。在这种情况下,作为合理的战略顺序,应优先让电力部门在终端用户之前实现零碳,将电力部门首先纳入国家碳市场是有意义的。
And hopefully, other variables so far exogenous to the current parameters of our model-e.g., technology breakthroughs, including additional PPA instruments—may come along the way.
并且有望在这一过程中出现目前模型参数之外的其他变量,例如技术突破,包括额外的PPA工具。
12 As a policy recommendation, one way to consider imposing carbon taxation would be: (a) to figure out the sector-specific average level of carbon intensity, say, in every 3-5 years; and (b) to impose progressive taxes on those that are above the average level of carbon intensity and subsidize those below the average level for technology innovations toward further decarbonization.
12作为一项政策建议,考虑征收碳税的一种方式是:(a) 每3至5年确定特定行业的平均碳强度水平;(b) 对高于平均碳强度水平的行业征收累进税,并对低于平均水平的行业进行补贴,以推动其进行进一步脱碳的技术创新。
${}^{13}$ In terms of wind power, in light of the great heterogeneity of wind source across the vast territories of China, enhanced regional coordination in stable power supply would be critical.
${}^{13}$ 在风力发电方面,鉴于中国幅员辽阔,风源差异巨大,加强稳定供电方面的区域协调至关重要。
Challenges and Opportunities
挑战与机遇
China’s goal of achieving carbon neutrality by 2060 means profound transformation of the world’s second-largest economy and the biggest emitter. Indeed, just as Chinese President Xi Jinping said at the U.N. General Assembly in September 2020, China must undergo a “green revolution”. To achieve carbon neutrality by 2060 is a very tall order, as China currently relies heavily on coal–one of the most carbon-intensive fossil fuels. The other challenge is the relatively short time. The EU plans to spend 50-70 years from carbon emission peak to carbon neutral, but China only has a thirty-year schedule. There are numerous challenges in the nexus of policy, technology, and economy. The time constraint makes the challenges even larger.
中国到2060年实现碳中和的目标意味着世界第二大经济体和最大排放国要进行深刻变革。事实上,正如中国国家主席习近平在2020年9月联合国大会上所说,中国必须经历一场“绿色革命”。鉴于中国目前严重依赖煤炭(最具碳密集型的化石燃料之一),到2060年实现碳中和是一项非常艰巨的任务。另一个挑战是时间相对较短。欧盟计划从碳排放峰值到碳中和需花费50 - 70年,但中国只有三十年的时间表。在政策、技术和经济的关联中存在众多挑战。时间限制使得这些挑战更加巨大。
But there is also a bright side. Looking ahead, China still enjoys the advantage of backwardness. Its urbanization was about ${18}\% {40}$ or so years ago, and it has now reached about 60%. By comparison, it is 92% for Japan and 82% for the United States (United Nations, 2018). Moving forward, there is huge room for building smart-cities. Smart-cities integrate real-time data from diverse data sources into a single data hub, where huge amounts of data are analyzed and used to inform management and planning decisions. Instead of retrofitting old cities, smart-city projects can involve building brand-new cities that are eco-friendly and energy efficient from the ground up by deploying low-carbon, zero-carbon and negative-carbon technologies simultaneously. As a top priority for designing and building smart cities in the future, energy efficiency towards carbon neutrality can be optimized through a combination of sensor technology, big data, and data science.
但也有光明的一面。展望未来,中国仍享有后发优势。其城市化大约在${18}\% {40}$年前开始,目前已达到约60%。相比之下,日本为92%,美国为82%(联合国,2018年)。未来,建设智慧城市有巨大空间。智慧城市将来自不同数据源的实时数据整合到一个单一的数据中心,在那里大量数据被分析并用于为管理和规划决策提供信息。智慧城市项目无需改造旧城市,而是可以通过同时部署低碳、零碳和负碳技术,从头开始建设生态友好且能源高效的全新城市。作为未来设计和建设智慧城市的首要任务,可通过传感器技术、大数据和数据科学的结合来优化实现碳中和的能源效率。
And within our PPA + MBA + CCS + NBS framework, PPA aside, CCS, MBA, and NBS may have higher potential on carbon removal than we had predicted. As we have seen in previous chapters (esp. Chapters 1, 3, 4, 5, and 6), in recent years China has made remarkable progress in CCUS/CCS pilots and has learnt a great deal from its own experience of ETSs as well. As a negative ${\mathrm{{CO}}}_{2}$ emission technology, CCUS, especially CCS + EOR, will be more attractive when the carbon price is sufficiently high and when the technology becomes more mature or advanced.
在我们的PPA + MBA + CCS + NBS框架内,除了PPA,CCS、MBA和NBS在碳去除方面可能具有比我们预测更高的潜力。正如我们在前面几章(特别是第1、3、4、5和6章)中所看到的,近年来中国在CCUS/CCS试点方面取得了显著进展,并且也从自身的碳排放交易体系经验中学到了很多。作为一种负${\mathrm{{CO}}}_{2}$排放技术,当碳价格足够高且技术变得更加成熟或先进时,CCUS,特别是CCS + EOR,将更具吸引力。
Expansion of green financing—a typical example of MBA—also helps in terms of financing CCS or CCUS, and we can expect more applications of CCUS years down the road. Generally, green loans, green bonds and green insurance can be powerful tools–via price signaling, risk management and resource allocation–to facilitate industrial transformation, including energy structure from fossil to non-fossil fuels. We recommend that much more work be done on that front for China to achieve carbon neutrality by 2060. Indeed, to phase out coal more aggressively with renewables will be particularly important for China, as our simulation model indicates. There, the good news is that since 2016 when China held the presidency of G20 summit meeting and included the topic of “green finance” into the G20 agenda, the country has made impressive progress in green finance. According to the latest statistics by the Research Bureau of PBOC, by the end of 2020, green loans in China totaled 12 trillion RMB or about 1.8 trillion US dollars (largest in the world), and the stock of green bond reached 813.2 billion RMB or about 125 billion US dollars (second largest in the world, next to the US). Their estimation was that so far the yearly average of green financing in China was equivalent to a reduction of ${100}{\mathrm{{MtCO}}}_{2}$ emissions, more than $1\%$ of the national total $(9,{800} \; {\mathrm{{MtCO}}}_{2}$ in 2017), and the number is expected to rise years ahead.
绿色金融的扩张——MBA的一个典型例子——在为CCS或CCUS融资方面也有帮助,我们预计未来几年CCUS会有更多应用。一般来说,绿色贷款、绿色债券和绿色保险可以成为强大的工具——通过价格信号、风险管理和资源配置——来促进产业转型,包括从化石燃料到非化石燃料的能源结构转型。我们建议中国在这方面做更多工作以在2060年实现碳中和。事实上,正如我们的模拟模型所示,更积极地用可再生能源淘汰煤炭对中国尤为重要。好消息是,自2016年中国担任二十国集团峰会主席并将“绿色金融”议题纳入二十国集团议程以来,中国在绿色金融方面取得了令人瞩目的进展。根据中国人民银行研究局的最新统计,截至2020年底,中国绿色贷款总额达12万亿元人民币,约合1.8万亿美元(世界最大),绿色债券存量达8132亿元人民币,约合125亿美元(世界第二,仅次于美国)。他们估计,到目前为止中国绿色融资的年平均值相当于减少${100}{\mathrm{{MtCO}}}_{2}$排放量,超过了2017年全国总$(9,{800} \; {\mathrm{{MtCO}}}_{2}$排放量的$1\%$,预计未来几年这一数字还会上升。
There is also good news on NBS, Wang et al. (2020) have recently published a pioneer research in Nature. They reevaluate the carbon absorption capacity of terrestrial ecosystem in China and find terrestrial ecosystems, including forests, absorb about 1.11 billion tons of carbon annually from 2010 to 2016, which is 45% of anthropogenic carbon emissions in the same period. While their calculation, i.e. 45%, may have been overestimated and our own estimation is about 10%, their research does suggest that the role of forest carbon sink should be examined more closely. The wood products in China also have great potential (Xu et al., 2020), and the potential for increasing carbon sinks in wood products is estimated at 1.15 billion tons per year around 2060.
NBS方面也有好消息,Wang等人(2020年)最近在《自然》杂志上发表了一项开创性研究。他们重新评估了中国陆地生态系统的碳吸收能力,发现包括森林在内的陆地生态系统在2010年至2016年期间每年吸收约11.1亿吨碳,占同期人为碳排放量的45%。虽然他们的计算结果,即45%,可能被高估了,我们自己的估计约为10%,但他们的研究确实表明应更密切地审视森林碳汇的作用。中国的木制品也有很大潜力(Xu等人,2020年),预计到2060年左右木制品增加碳汇的潜力为每年11.5亿吨。
Uncertainties
不确定性
As indicated above, many uncertainties remain around achieving carbon neutral in China by 2060. R&D for de-carbonization strategies seems a least-regret option. Indeed, looking at the endless frontier of science and technology, scientists and engineers around the world have been working on nuclear fusion of hydrogen, and if one day that becomes successful both scientifically and commercially, it will be a game changer in energy transformation. It means almost boundless supplies of zero- ${\mathrm{{CO}}}_{2}$ , clean, and safe energy on Earth. But as history shows, technology only evolves and comes with many contingencies. Alternative strategies are necessary when progress of technologies is not on schedule. In transition period, the conflict of interests is unavoidable, particularly in the energy complex. ${}^{14}$ Our model is incapable for the simulation of conflict of interests, the politics of which, especially geopolitics, in fact carries high social and economic costs. There are also uncertainties in the deployment of renewable energy in sectors that are more difficult to be electrified in the near future. These sectors are those with high temperature industrial processes, city transportations, trains, shipping, and aviation, etc. In any case, for electrification to work as a tool for decarbonization, the precondition is that the source of power has to be made clean first, that is, in forms of non-fossil rather than fossil such as coal, which dominates China’s energy structure today. ${}^{15}$ Otherwise, as a net outcome in the energy complex, one may end up emitting more ${\mathrm{{CO}}}_{2}$ than reducing it in electrification.
如上所述,到2060年中国实现碳中和仍存在许多不确定性。脱碳战略的研发似乎是最无悔的选择。确实,纵观无尽的科技前沿,世界各地的科学家和工程师一直在研究氢核聚变,如果有一天在科学和商业上都取得成功,那将是能源转型的游戏规则改变者。这意味着地球上几乎有无尽的零${\mathrm{{CO}}}_{2}$、清洁和安全能源供应。但正如历史所示,技术只会不断发展且伴随着许多偶然因素。当技术进步未按计划进行时,替代战略是必要的。在转型期,利益冲突不可避免,尤其是在能源综合体中。${}^{14}$我们的模型无法模拟利益冲突,而其政治因素,尤其是地缘政治,实际上会带来高昂的社会和经济成本。在近期内更难实现电气化的行业中,可再生能源的部署也存在不确定性。这些行业包括高温工业流程、城市交通、火车、航运和航空等。无论如何,要使电气化成为脱碳工具,前提是电力来源必须首先清洁化,即采用非化石能源而非像煤炭这样目前在中国能源结构中占主导地位的化石能源。${}^{15}$否则,作为能源综合体的最终结果,电气化可能最终导致排放的${\mathrm{{CO}}}_{2}$比减少的更多。
14 The current dual-track system of ETSs in China—seven regional markets and one national market-is an illustration of the latent issue of conflict of interest unique to the political economy of the vast country. Given different industrial structures across different regions
14中国目前的碳排放交易体系双轨制——七个区域市场和一个全国市场——体现了这个大国政治经济中独特的潜在利益冲突问题。鉴于不同地区的产业结构不同
A final note: Globally, in the European Union, for instance, of late there has been talks or proposals about transborder carbon taxes. How that will figure in the prospect of Chinese exports (e.g., crude steel or steel products) is an area that needs to be further studied. ${}^{16}$
最后一点:在全球范围内,例如在欧盟,最近有关于跨境碳税的讨论或提议。这将如何影响中国出口(如粗钢或钢铁产品)的前景是一个需要进一步研究的领域。${}^{16}$
in China, arguably one national ETS covering all industrial sectors and all at once without transition period runs the risk of widening rather than narrowing the already palpable regional imbalances in terms of both economic development and wealth distribution. Unlike regional ETSs which cover different industrial sectors, China’s national ETS, as currently designed, only covers the power sector, and electricity is more or less homogenous across the whole country.
在中国,可以说一个覆盖所有工业部门且没有过渡期的全国性碳排放交易体系有扩大而非缩小经济发展和财富分配方面已经明显的区域不平衡的风险。与覆盖不同工业部门的区域碳排放交易体系不同,中国目前设计的全国性碳排放交易体系仅覆盖电力部门,而电力在全国或多或少是同质的。
${}^{15}$ For instance, presently about ${60}\%$ of power or 1.08 billion kw of electricity in China is coal-fired, and much of it was installed in the past 15 years, and normally won’t retire until 20-30 years later. Early retirement will incur additional costs ceteris paribus-a daunting task especially for economically poor regions of China.
${}^{15}$例如,目前中国约${60}\%$的电力或10.8亿千瓦的电量是燃煤发电,其中大部分是在过去15年安装的,通常要到20 - 30年后才会退役。在其他条件相同的情况下,提前退役将产生额外成本——这对中国经济贫困地区来说是一项艰巨的任务。
${}^{16}$ If the US and EU decide to impose transborder carbon tax, that would have significant impact on Chinese exports, as well as on exports from other developing countries. A critical variable to consider here is to what extent would the transborder carbon tax be earmarked for green technology transfers from the developed to the developing countries.
${}^{16}$如果美国和欧盟决定征收跨境碳税,这将对中国出口以及其他发展中国家的出口产生重大影响。这里要考虑的一个关键变量是跨境碳税将在多大程度上用于从发达国家向发展中国家的绿色技术转让。
J. Fu et al.
J. 傅等人
Acronym Full spelling
首字母缩略词 全拼
BECCS Bioenergy with carbon capture and storage
BECCS 碳捕获与封存的生物能源
CCS Carbon capture and storage
CCS 碳捕获与封存
CCUS Carbon capture, utilization and storage
CCUS 碳捕获、利用与封存
DICE Dynamic integrated model of climate and the economy
DICE 气候与经济动态综合模型
EU European Union
EU 欧盟
GHG Greenhouse gas
GHG 温室气体
IUCN The International Union for the Conservation of Nature
IUCN 国际自然保护联盟
MBA Market-based approach
基于市场的方法
NBS Nature-based solutions
基于自然的解决方案
NDC Nationally determined contributions
国家自主贡献
PPA Public policy approach
公共政策方法
References
参考文献
Bellassen, V., & Luyssaert, S. (2014). Carbon sequestration: Managing forests in uncertain times. Nature, 506(7487), 153-155. https://doi.org/10.1038/506153a
China Ministry of Environmental Protection. (2019). China’s climate change policy and action 2019 annual report. Retrieved from http://www.mee.gov.cn/ywgz/ydqhbh/qhbhlf/ 201911/P020200121308824288893.pdf
Cohen-Shacham, E., Walters, G., Janzen, C., & Maginnis, S. (2016). Nature-based solutions to address global societal challenges, xiii+97. IUCN.
Ding, S., Zhang, M., & Song, Y. (2019). Exploring China’s carbon emissions peak for different carbon tax scenarios. Energy Policy, 129, 1245-1252.
Duan, H., Mo, J., Fan, Y., et al. (2018) Achieving China’s energy and climate policy targets in 2030 under multiple uncertainties. Energy Economics, 70, 45-60.
Dong, H., Dai, H., Geng, Y., et al. (2017). Exploring impact of carbon tax on China’s CO2 reductions and provincial disparities. Renewable and Sustainable Energy Reviews, 77, 596-603.
Gallagher, K. S., Zhang, F., Orvis, R., Rissman, J., & Liu, Q. (2019). Assessing the policy gaps for achieving China’s climate targets in the Paris Agreement. Nature Communications, 10(1), 1-10.
Hardin, G. (1968, December 13). The tragedy of the commons. Science, 162(3859), 1243- 1248.
He, G., Lin, J., et al. (2020). Author correction: rapid cost decrease of renewables and storage accelerates the decarbonization of China’s power system. Nature Communications, 11, 2486.
He, J., Gou Di, Z., Zhan, T. F., Zhuan, Y., Lu, X., & Jiu, J. Y. (2020) [EB/OL]. http://iccsd.tsi nghua.edu.cn/wap/news-301.html
He, J., Zhong, G., Di, T., Fa, Z., Yu, Z., Xing, L., & Jing, Y. J., [EB/OL]. (2020). http://iccsd.tsinghua.edu.cn/wap/news-301.html.
Hyman, R. C., Reilly, J. M., Babiker, M. H., & De Masin, A. (2002). Modeling non- ${\mathrm{{CO}}}_{2}$ greenhouse gases. MIT, US.
IEA, 2020. World Energy Outlook 2020. Available from: http://www.worldenergyoutlook.org/.
IPCC. (2018). Global warming of 1.5°C. An IPCC Special Report on the impacts of global warming of ${1.5}^{ \circ }\mathrm{C}$ above pre-industrial levels and related global greenhouse gas emission pathways, in the context of strengthening the global response to the threat of climate change.
Jin, L., Yi, Y., & Xu, J. Forest carbon sequestration and China’s potential: The rise of a nature-based solution for climate change mitigation. China Economic Journal, 200-222. https:// doi.org/10.1080/17538963.2020.1754606.
Li, C., Zhou, C., Peng, W., Lv, Y., & Luo, X. (2020). Accurate prediction of short-term photovoltaic power generation via a noval double-input-rule-modules stacked deep fuzzy method. Energy, 212, 1-13.
Lin, B., & Jia, Z. (2019). Energy, economic and environmental impact of government fines in China’s carbon trading scheme. Science of the Total Environment, 667, 658-670.
Nature. (2017). Nature-based solutions’ is the latest green Jargon that means more than you might think. Nature, 541(7636), 133-134. https://doi.org/10.1038/541133b
Niu, S., Liu, Y., Ding, Y., et al. (2016). China’s energy systems transformation and emissions peak. Renewable and Sustainable Energy Reviews, 58, 782-795.
Nordhaus, W. D. (2007). A review of the Stern review on the economics of climate change. Journal of Economic Literature, 45(3), 686-702.
Nordhaus, W. D., & Boyer, J. (2000). Warming the world: Economic models of global warming. The MIT Press.
Shan, Y., Zhou, Y., Meng, J., Mi, Z., Liu, J., & Guan, D. (2019). Peak cement-related ${\mathrm{{CO}}}_{2}$ emissions and the changes in drivers in China. Journal of Industrial Ecology, 23(4), 959- 971.
Song, J., Yang, W., & Wang, S. (2018). Exploring potential pathways towards fossil energy-related GHG emission peak prior to 2030 for China: An integrated input-output simulation model. Journal of Cleaner Production, 178, 688-702.
Stern, N. (2006). The economics of climate change: The stern review. Cambridge: Cambridge University Press.
UNFCCC. (2019). Climate ambition alliance: Nations renew their push to upscale action by 2020 and achieve net zero ${\mathrm{{CO}}}_{2}$ emissions by 2050.
United Nations. (2018). Department of Economic and Social Affairs, Population Division (2018). World Urbanization Prospects: The 2018 Revision, Online Edition.
Wilkerson, J. T., Leibowicz, B. D., & Turner, D. D. (2015). Comparison of integrated assessment models: Carbon price impacts on U.S. energy. Energy Policy, 76, 18-31.
Yuan, J., Xu, Y., Hu, Z., Zhao, C., Xiong, M., & Guo, J. (2014). Peak energy consumption and ${\mathrm{{CO}}}_{2}$ emissions in China. Energy Policy, 68, 508-523
Yuan, Y., Duan, H., Tsvetanov, T. G. (2020). Synergizing China’s energy and carbon mitigation goals: General equilibrium modeling and policy assessment. Energy Economics, 104787.
Xu, J., Da, G., Cheng, N., Yu, Z., Guo, N., Xing, Z. (2020). [EB/OL]. https://mp.weixin.qq.com/s/-dlRSV1b5WyKfn-nEcGfdA
Zhang, P., Shi, X., Sun, Y., Cui, J., & Shao, S. (2019). Have China’s provinces achieved their targets of energy intensity reduction? Reassessment based on nighttime lighting data. Energy Policy, 128, 276-283.
Correction to: Climate Mitigation and Adaptation in China
《中国的气候缓解与适应》的更正
Jun Fu, Dongxiao Zhang, and Ming Lei
傅军、张东晓、雷明
Correction to:
对……的更正
J. Fu et al. (eds.), Climate Mitigation and Adaptation in China,
傅军等人(编),《中国的气候缓解与适应》
https://doi.org/10.1007/978-981-16-4310-1
In the original version of the book, Sect. 4.2 in Chap. 1 was revised. A new sentence has been added on page 29. The chapter and the book have been updated with the change.
在本书的原始版本中,第1章的第4.2节进行了修订。第29页新增了一句话。该章及本书已根据此更改进行更新。
In the original version of the book, Chap. 4 was revised. A new sentence has been added on page 109. The chapter and the book have been updated with the change.
在本书的原始版本中,第4章进行了修订。第109页新增了一句话。该章及本书已根据此更改进行更新。
The original version of Chap. 5 was updated with few word corrections on page 198. The chapter has been updated with the changes.
第5章的原始版本在第198页进行了少量文字更正。该章已根据这些更改进行更新。
In the original version of the book, the following belated corrections were updated: In Chap. 7, a new sentence has been added on pages 254 and 272, respectively, in Sects. 2.1 and 4.4, and the symbol in the Table 2 note has been changed from “$” to “$” in Sect. 4.1. The chapter and the book have been updated with the changes.
在本书的原始版本中,以下延迟更正已更新:在第7章中,第2.1节和第4.4节的第254页和第272页分别新增了一句话,并且第4.1节中表2注释中的符号已从“$”更改为“$”。该章及本书已根据这些更改进行更新。
https://doi.org/10.1007/978-981-16-4310-1_8
The updated versions of these chapters can be found at
这些章节的更新版本可在
https://doi.org/10.1007/978-981-16-4310-1_1,
https://doi.org/10.1007/978-981-16-4310-1_4,
https://doi.org/10.1007/978-981-16-4310-1_5,
https://doi.org/10.1007/978-981-16-4310-1_7.
Index
索引
A
Adaptation, 4, 9, 16, 25, 29, 36, 253, 268
适应,4, 9, 16, 25, 29, 36, 253, 268
Advantage of backwardness, 271
后发优势,271
Air pollutant emission, 39
空气污染物排放,39
Air pollution, 227
空气污染,227
Air pollution standards, 256
空气污染标准,256
Allowance allocation, 221, 227-229
配额分配,221, 227 - 229
American Clean Energy Leadership Act, The, 16
《美国清洁能源领导力法案》,16
American Reinvestment and Recovery, 17
美国再投资与复苏,17
Anthropogenic ${\mathrm{{CO}}}_{2}$ emission, 61,220
人为${\mathrm{{CO}}}_{2}$排放,61, 220
Anthropogenic greenhouse gas, 3
人为温室气体,3
AOD process, 77
AOD流程(大气光学厚度流程),77
Arthur Pigou, 185
亚瑟·庇古,185
Asian Development Bank, 28
亚洲开发银行,28
Asia Pacific, 22
亚太地区,22
Assigned Amount Units (AAUs), 243
分配数量单位(AAUs),243
Australia, 22, 23, 25, 125, 259
澳大利亚,22, 23, 25, 125, 259
Automobiles, 5
汽车,5
Auxiliary system, 49, 63
辅助系统,49, 63
Aviation, 185, 223, 224, 226, 236, 273
航空,185, 223, 224, 226, 236, 273
B
Baseline and credit approach, 222, 236
基准线与信用方法,222, 236
Baseline scenario, 48, 49, 231, 232, 260, 264, 267
基准情景,48, 49, 231, 232, 260, 264, 267
Basic Oxygen Furnace (BOF), 76, 110
碱性氧气转炉(BOF),76, 110
Battery storage, 258
电池储能,258
Beijing, 11, 183, 186-188, 192-196, 198, 200, 202, 203, 205, 207, 209, 211, 222, 223, 225, 226, 254, 258
北京,11, 183, 186 - 188, 192 - 196, 198, 200, 202, 203, 205, 207, 209, 211, 222, 223, 225, 226, 254, 258
Benchmarking, 221, 223, 225, 229
对标,221, 223, 225, 229
Best Available Technologies (BATs), 3, 16, 29, 41
最佳可得技术(BATs),3, 16, 29, 41
Big bang approach, 213
大爆炸方法,213
Big data, 271
大数据,271
Bioenergy with ${\mathrm{{CO}}}_{2}$ Capture and Storage (BECCS), 20, 61, 254
带有${\mathrm{{CO}}}_{2}$捕集与封存的生物能源(BECCS),20, 61, 254
Biofuels, 81, 254
生物燃料,81, 254
Biomass energy, 81, 252, 257
生物质能,81, 252, 257
Blast Furnace Gas (BFG), 114, 115, 118, 119, 121-123, 125, 130-138, 144, 146, 148, 149, 152, 157, 158, 161, 171, 173-175
高炉煤气(BFG),114, 115, 118, 119, 121 - 123, 125, 130 - 138, 144, 146, 148, 149, 152, 157, 158, 161, 171, 173 - 175
Blast Furnaces (BFs), 14, 36, 40, 63, 64, 74, 110-112, 114, 115, 117-119, 121, 126, 157, 158, 173-175
高炉(BFs),14, 36, 40, 63, 64, 74, 110 - 112, 114, 115, 117 - 119, 121, 126, 157, 158, 173 - 175
Brown assets, xiii
棕色资产,xiii
Building material, 13, 15, 223, 225, 235
建筑材料,13, 15, 223, 225, 235
Business model, 20, 109
商业模式,20, 109
C
California, 17, 195, 198, 251, 258
加利福尼亚州,17, 195, 198, 251, 258
Canada, 16-18, 27, 98, 99, 171, 251
加拿大,16 - 18, 27, 98, 99, 171, 251
Cap and trade, 255, 258
总量管制与交易制度,255, 258
Capillary trapping, 91
毛细管捕集,91
Capture technology, 17, 66-71, 120, 122, 123, 132
捕集技术,17, 66 - 71, 120, 122, 123, 132
Carbon Capture and Storage (CCS), 16-18, 20-22, 26, 29, 50, 52, 61, 72, 73, 83-85, 87, 89, 90, 96-99,
碳捕集与封存(CCS),16 - 18, 20 - 2, 26, 29, 50, 52, 61, 72, 73, 83 - 85, 87, 89, 90, 96 - 99
111, 112, 227, 229, 231, 249, 252-255, 260, 267, 271
Carbon capture technology, 66, 113, 120, 126, 174, 235
碳捕集技术,66, 113, 120, 126, 174, 235
Carbon Capture, Utilization and Storage (CCUS), 4, 9, 11, 12, 16-30, 36, 41, 44, 45, 47-54, 61, 109, 176, 196, 220, 227-237, 253
碳捕集、利用与封存(CCUS),4, 9, 11, 12, 16 - 30, 36, 41, 44, 45, 47 - 54, 61, 109, 176, 196, 220, 227 - 237, 253
Carbon dioxide, 3, 24, 25, 61, 74, 81, 84, 95, 96, 163, 228, 250, 251, 253, 259
二氧化碳,3, 24, 25, 61, 74, 81, 84, 95, 96, 163, 228, 250, 251, 253, 259
Carbon emissions, 3, 4, 7, 10, 12, 14, 16, 20, 22, 23, 39, 40, 48-51, 54, 61, 81, 110, 174, 185-187, 200, 204, 205, 208, 209, 212, 222, 225, 235, 237, 238, 249-252, 255, 256, 258-261, 264, 266-268, 270-272
碳排放,3, 4, 7, 10, S, 14, 16, 20, 22, S, 39, 40, 48 - 51, 54, 61, 81, 110, 174, 185 - 187, 200, 204, 205, 208, 209, 212, 222, 225, 235, 237, 238, 249 - 252, 255, 256, 258 - 261, 264, 266 - 268, 270 - S72
Carbon emissions trading, 11, 15, 27
碳排放交易,11, 15, 27
Carbon intensity, 4, 10, 13, 14, 25, 26, 41, 49,50,186,187
碳强度,4, 10, 13, 14, 25, 26, 41, 49,50,186,187
Carbon market, 11, 14, 15, 35, 41, 183, 184, 186, 187, 193, 195-197, 207, 210-213, 219-221, 225, 227, 235-238, 254, 258, 261, 270
碳市场,11, 14, 15, 35, 41, 183, 184, 186, 187, 193, 195 - 197, 207, 210 - 213, 219 - 221, 225, 227, 235 - 238, 254, 258, 261, 270
Carbon neutrality, 17, 19, 26, 29, 36, 45, 51, 249, 251, 252, 271
碳中和,17, 19, 26, 29, 36, 45, 51, 249, 251, 252, 271
Carbon peak, 25
碳峰值,25
Carbon price, 196, 197, 210, 219, 230, 233, 234, 237, 238, 258, 259, 261, 267-271
碳价格,196, 197, 210, 219, 230, 233, 234, 237, 238, 258, 259, 261, 267 - 271
Carbon pricing, 18, 226, 255, 256, 258, 260-262, 266, 270
碳定价,18, 226, 255, 256, 258, 260 - 262, 266, 270
Carbon sequestration, 17, 24, 253
碳封存,17, 24, 253
Carbon Sequestration Leadership Forum (CSLF), 253
碳封存领导论坛(CSLF),253
Carbon sinks, 231, 253, 254, 260, 262, 267, 272
碳汇,231, 253, 254, 260, 262, 267, 272
Carbon tax, 17, 213, 258, 266, 273
碳税,17, 213, 258, 266, 273
Carbon transport, 28
碳运输,28
Carbon utilization technology, 72
碳利用技术,72
Carrots, 9, 10, 12, 15
胡萝卜,9, 10, 12, 15
Casting process, 79
铸造工艺,79
CCUS project, 16, 18, 19, 21-24, 26, 28, 30, 45, 51-53, 109, 227, 230-238
碳捕集、利用与封存项目,16, 18, 19, 21 - 24, 26, 28, 30, 45, 51 - 53, 109, 227, 230 - 238
Cement, 7, 12, 22, 23, 28, 30, 35, 61, 64, 89, 92, 188, 220, 223, 224, 258, 259, 261
水泥,7, 12, 22, 23, 28, 30, 35, 61, 64, 89, 92, 188, 220, 223, 224, 258, 259, 261
Central Asia, 21
中亚,21
Certified Emission Reductions (CERs), 222, 231
核证减排量(CERs),222,231
${\mathrm{{CH}}}_{4},3,{113},{115},{117},{188},{250}$
Chemical absorption, 67, 120, 121, 126, 130-140, 142-144, 146-162, 164-175
化学吸收,67,120,121,126,130 - 140,142 - 144,146 - 162,164 - 175
Chemicals, 13, 15, 26, 28, 63, 66, 67, 69, 70, 92, 95, 97, 111, 120, 121, 126, 127, 130, 131, 133-136, 150, 151, 153, 154, 159, 160, 165-169, 185, 188, 204, 224, 225, 235
化学品,13,15,26,28,63,66,67,69,70,92,95,97,111,120,121,126,127,130,131,133 - 136,150,151,153,154,159,160,165 - 169,185,188,204,224,225,235
Chicago Climate Exchange (CCX), 185
芝加哥气候交易所(CCX),185
China Association of Metalscrap Utilization (CAMU), 43
中国金属再生资源协会(CAMU),43
CHINAGEM, 259-261
中国地质科学院,第259 - 261页
China National Petroleum Corporation (CNPC), 97
中国石油天然气集团公司(CNPC),97
China United Coalbed Methane, 97
中联煤层气,97
China-US Joint Presidential Statement on Climate Change, 15
《中美气候变化联合声明》,第15页
Chinese Academy of Sciences, 80
中国科学院,80
Chinese Certified Emission Reduction (CCER), 53, 188, 189, 191, 194, 226, 227, 230, 232, 233
中国核证自愿减排量(CCER),53,188,189,191,194,226,227,230,232,233
Chongqing, 11, 183, 186-189, 193-196, 198, 200, 205, 208, 209, 212, 215, 222, 223, 226, 254, 258
重庆,11,183,186 - 189,193 - 196,198,200,205,208,209,212,215,222,223,226,254,258
Clean Development Mechanism (CDM), 222, 231, 233
清洁发展机制(CDM),222, 231, 233
Clean growth, 19
清洁增长,19
Climate change, 3, 4, 9-11, 16, 18, 19, 25, 29, 36, 41, 43, 61, 183, 207, 214, 216, 225, 227, 249-253
气候变化,3,4,9 - 11,16,18,19,25,29,36,41,43,61,183,207,214,216,225,227,249 - 253
Climate change law, 10, 11
气候变化法,10,11
Climate change levy, 19
气候变化税,19
CNPC Jilin Oilfield, 28
中国石油吉林油田,28
${\mathrm{{CO}}}_{2},3,4,7 - {10},{12} - {23},{25} - {30},{35},{36}$ , 40, 41, 44, 45, 47-53, 55, 61, 66-84, 86-98, 164, 171-176, 183-185, 188, 194, 196-200, 204-208, 211, 215, 219, 220,
222, 225, 227, 228, 230, 232, 235-238, 240-242, 250-258, 260, 265-268, 271
${\mathrm{{CO}}}_{2}$ -EOR, 17, 18, 28, 61, 73, 85, 97-99, 254
${\mathrm{{CO}}}_{2}$ -提高采收率,17,18,28,61,73,85,97 - 99,254
${\mathrm{{CO}}}_{2}$ leakage,88,91
${\mathrm{{CO}}}_{2}$泄漏,88,91
${\mathrm{{CO}}}_{2}$ pipeline transport,84
${\mathrm{{CO}}}_{2}$管道运输,84
Coal, 7, 14, 15, 18, 21-23, 27, 30, 48, 63, 64, 74, 80, 89, 93, 95, 96, 110, 112-114, 143, 152, 171, 228, 252, 255, 266, 267, 270, 271
煤炭,7,14,15,18,21 - 23,27,30,48,63,64,74,80,89,93,95,96,110,112 - 114,143,152,171,228,252,255,266,267,270,271
Coal cap policies, 255
煤炭总量控制政策,255
Coal-fired power plant, 18, 21, 26, 27, 30, 51, 119, 149, 152, 164, 185, 254
燃煤发电厂,18,21,26,27,30,51,119,149,152,164,185,254
Coal seams, 95
煤层,95
Coking, 43, 47, 63, 110, 112, 113, 204
炼焦,43,47,63,110,112,113,204
Common and differentiated responsibilities, vi
共同但有区别的责任,vi
Compliance, 188, 189, 191-194, 207, 210, 221, 227, 228, 230, 236, 238
合规,188,189,191 - 194,207,210,221,227,228,230,236,238
Conceptual framework, 250, 252, 253
概念框架,250,252,253
Construction, 17, 22, 25, 26, 28, 45, 51, 53, 64, 71, 84, 86, 94, 185, 186, 210, 211, 225, 250, 254, 259
建设,17,22,25,26,28,45,51,53,64,71,84,86,94,185,186,210,211,225,250,254,259
Consumption, 23, 36, 39, 75, 77, 82, 157, 229, 241, 269, 270
消费,23,36,39,75,77,82,157,229,241,269,270
Continuous casting process, 65, 79
连铸工艺,65,79
Converter process, 75, 77, 80, 110
转炉工艺,75,77,80,110
Converter steelmaking, The, 64
转炉炼钢,64
Copenhagen Climate Change, 4
哥本哈根气候变化,4
Cost reduction, 220, 256, 260-262, 265, 266, 268, 270
成本降低,220,256,260 - 262,265,266,268,270
COVID-19 pandemic, 38
新冠疫情,38
Cross-disciplinary, v
跨学科,v
Crude steel, 6, 7, 14, 36-40, 42, 43, 49, 51, 110, 220, 229, 240, 273
粗钢,6,7,14,36 - 40,42,43,49,51,110,220,229,240,273
Cryogenics capture technology, 69
低温捕集技术,69
D
Data science, 271
数据科学,271
Debt rate, 14
负债率,14
De-carbonization, 9, 260, 270, 272
脱碳,9,260,270,272
Deep-sea sediments, 95
深海沉积物,95
Demonstration, 11, 17, 19, 23, 24, 27-29, 44, 45, 50, 51, 53, 71, 83, 85,
示范,11,17,19,23,24,27 - 29,44,45,50,51,53,71,83,85
97, 99, 121, 125-127, 130, 131, 135, 136, 143, 150, 152-154, 158-160, 165, 166, 168, 169, 171, 172, 188, 230, 233-235, 237, 254
Denmark, 251
丹麦,251
Dephosphorization, 65, 76, 77
脱磷,65,76,77
Depleted oil and gas reservoirs, 93
枯竭的油气藏,93
Design options, 219, 220, 235-238
设计方案,219, 220, 235 - 238
Developmental path, 25
发展路径,25
DICE, 213, 214, 250
动态综合气候经济模型,213, 214, 250
Direct Air Capture (DAC), 72
直接空气捕获(DAC),72
Domestic agenda, 4
国内议程,4
Direct Reduce Ion (DRI), 110
直接还原铁(DRI),110
Dunhua Methanol Plant, 28
敦化甲醇厂,28
Dust reduction, 75, 77
降尘,75, 77
E
EAF process, 78
电弧炉工艺,78
Eco-civilization, 25, 41
生态文明,25, 41
Economic incentives, 9, 12, 13
经济激励措施,9, 12, 13
Ecosystem, 15, 25, 253, 255
生态系统,15, 25, 253, 255
Electric Arc Furnaces (EAF), 6, 40, 41, 43, 49, 50, 62, 78, 82, 110
电弧炉(EAF),6, 40, 41, 43, 49, 50, 62, 78, 82, 110
Electricity, 15, 21, 45, 48, 115, 119, 123, 188, 204, 226, 236, 242, 256, 270, 273
电力,15, 21, 45, 48, 115, 119, 123, 188, 204, 226, 236, 242, 256, 270, 273
Electriciy Swing Absorption (ESA), 123
电力变压吸附(ESA),123
Electric vehicle, 270
电动汽车,270
Electrification, 49, 270
电气化,49,270
Electrolytic aluminum, 12, 185, 223
电解铝,12,185,223
Emerging carbon capture technology, 71
新兴碳捕获技术,71
Emerging technology, 4, 11, 16, 237
新兴技术,4,11,16,237
Emissions Trading Group (ETG), 185
排放交易集团(ETG),185
Emission-Trading System (ETS), 10-12, 14, 15, 18, 19, 35, 41, 183-200, 204, 205, 207-213, 219-230, 233-238, 254, 255, 258
排放交易体系(ETS),10 - 12,14,15,18,19,35,41,183 - 200,204,205,207 - 213,219 - 230,233 - 238,254,255,258
Employment, 269, 270
就业,269,270
Energy, 7, 9, 12, 13, 17-19, 21-24, 27, 28, 35, 36, 39-43, 45, 48-52, 68-70, 74, 78, 81, 82, 84, 85, 87, 89, 110, 111, 114-116, 120, 125-127, 130, 131, 133-136, 143, 152, 174, 196, 228, 232, 252, 254,
能源,7,9,12,13,17 - 19,21 - 24,27,28,35,36,39 - 43,45,48 - 52,68 - 70,74,78,81,82,84,85,87,89,110,111,114 - 116,120,125 - 127,130,131,133 - 136,143,152,174,196,228,232,252,254,
256, 257, 259, 261, 262, 264, 265, 267, 269-272
Energy combustion, 259, 264
能源燃烧,259,264
Energy conservation, 9, 12-14, 42, 43, 48, 119, 120
节能,9,12 - 14,42,43,48,119,120
Energy consumption, 4, 7, 8, 12-15, 18, 39, 42-45, 68, 71, 72, 80, 89, 120, 122, 125, 127, 128, 157, 158, 164, 165, 199, 223, 224, 256, 266, 270
能源消耗,4,7,8,12 - 15,18,39,42 - 45,68,71,72,80,89,120,122,125,127,128,157,158,164,165,199,223,224,256,266,270
Energy efficiency, 7, 13, 19, 22, 36, 40-42, 44, 48, 220, 255, 256, 261, 262, 264, 265, 267-271
能源效率,7,13,19,22,36,40 - 42,44,48,220,255,256,261,262,264,265,267 - 271
Energy efficiency enhancement, 256, 260
提高能源效率,256,260
Energy intensity, 13, 39, 40, 42-44, 256, 257, 261
能源强度,13, 39, 40, 42 - 44, 256, 257, 261
Energy intensity targets, 256
能源强度目标,256
Energy-saving, 6
节能,6
Energy structure, 4, 10, 25, 26, 30, 49, 250, 252, 254, 268, 271
能源结构,4, 10, 25, 26, 30, 49, 250, 252, 254, 268, 271
Enhanced Coal Bed Methane (ECBM), 96
强化煤层气(ECBM),96
Enhanced coal bed methane recovery, ix
强化煤层气开采,ix
Enhanced Oil Recovery (EOR), 17, 18, 21, 28, 52, 61, 73, 84, 87, 96, 98, 99, 230,254
提高采收率(EOR),17, 18, 21, 28, 52, 61, 73, 84, 87, 96, 98, 99, 230,254
Environmental Impact Assessment (EIA), 26, 45
环境影响评估(EIA),26, 45
Environmental resource tax, 256
环境资源税,256
EOR technology, 23, 73
EOR技术,23, 73
Emission Reduction Units (ERUs), 243
减排单位(ERUs),243
EU ETS, 18, 20
欧盟排放交易体系(EU ETS),18, 20
EU GHG Emission Trading System (EU-ETS), 185, 186, 197, 212, 213, 221, 222, 228, 229, 233, 234, 237
欧盟温室气体排放交易体系(EU - ETS),185, 186, 197, 212, 213, 221, 222, 228, 229, 233, 234, 237
European Commission (EC), 19, 20, 185, 186, 228-230, 233
欧盟委员会(EC),19, 20, 185, 186, 228 - 230, 233
European Investment Bank (EIB), 233
欧洲投资银行(EIB),233
European Union (EU), 18, 19, 24, 25, 37, 38, 185, 210, 220, 230, 233, 251, 252, 258, 271, 273
欧盟,18, 19, 24, 25, 37, 38, 185, 210, 220, 230, 233, 251, 252, 258, 271, 273
Europe Green Deal, 251
欧洲绿色协议,251
Eventually, 5, 15, 20, 184, 185, 187, 213, 258, 264
最终,5, 15, 20, 184, 185, 187, 213, 258, 264
Excess capacity, 41, 42
产能过剩,41,42
F
Ferroalloy production, 80
铁合金生产,80
Five Year Plan (FYP), 14, 25, 186
五年计划(FYP),14,25,186
Fluorinated Gases, 250
氟化气体,250
Fossil, 256, 259, 264, 266, 269-271
化石,256,259,264,266,269 - 271
Fossil fuel-intensive, 61
化石燃料密集型,61
Fossil fuels, 7, 21, 44, 120, 171, 229, 240, 252, 255, 256, 259, 271
化石燃料,7,21,44,120,171,229,240,252,255,256,259,271
France, 213, 251
法国,213,251
Free allocation, 221, 238
免费分配,221,238
Fujian, 188, 202, 222, 223, 225, 226
福建,188,202,222,223,225,226
Fujian Froestry Certified Emission Reduction (FFCER), 227
福建林业核证减排量(FFCER),227
Full-chain, 53, 109
全链,53,109
G
Gas-fired power plant, 20
燃气发电厂,20
Gas hydrate-based capture technology, 70
基于天然气水合物的捕获技术,70
Gas reservoirs, 93, 94
气藏,93,94
Geological sequestration, 17, 20
地质封存,17,20
Germany, 251, 257
德国,251,257
GHG accounting, 228, 231, 232, 240
温室气体核算,228,231,232,240
GHG emission, 3, 10, 12, 16, 18, 24, 29, 185, 186, 220, 228, 229, 232, 251
温室气体排放,3,10,12,16,18,24,29,185,186,220,228,229,232,251
Global Carbon Capture and Storage Institute (GCCSI), 22, 23, 26, 84, 85, 98, 111, 112
全球碳捕集与封存研究所(GCCSI),22,23,26,84,85,98,111,112
Global CCS Institute, 4, 17, 19, 112
全球碳捕集与封存研究所,4,17,19,112
Gradual approach, 186, 213
渐进式方法,186,213
Grandfather, 188, 193, 207, 212, 221-225, 229
祖父条款,188,193,207,212,221 - 225,229
Green, 11
绿色,11
Green assets, xiii
绿色资产,xiii
Green bond market, 255
绿色债券市场,255
Green bonds, 254, 255, 260, 271
绿色债券,254,255,260,271
Green economy, 4, 9, 11, 36, 219
绿色经济,4,9,11,36,219
Green financing, 271, 272
绿色融资,271,272
Green growth, 4, 9, 12, 25, 28, 29, 41, 237
绿色增长,4,9,12,25,28,29,41,237
Greenhouse effect, 61
温室效应,61
Greenhouse Gas (GHG), 3, 27, 48, 185, 228, 250
温室气体(GHG),3,27,48,185,228,250
Green insurance, 255, 271
绿色保险,255,271
Green loans, 255, 271, 272
绿色贷款,255,271,272
Green procurement, 12
绿色采购,12
Green projects, 255
绿色项目,255
Green revolution, 271
绿色革命,271
Gross Domestic Product (GDP), 4, 5, 10, 13, 14, 25, 26, 36, 38, 41, 45, 49, 50, 186, 187, 201, 212, 222, 225, 252, 257, 259, 260, 262, 268, 270
国内生产总值(GDP),4,5,10,13,14,25,26,36,38,41,45,49,50,186,187,201,212,222,225, 252, 257, 259, 260, 262, 268, 270
Growth strategy, 15
增长战略,15
Guangdong, 11, 183, 186-188, 190, 192-195, 200, 204-206, 211, 212, 221-223, 225-227, 233, 254, 258
广东,11,183,186 - 188,190,192 - 195,200,204 - 206,211,212,221 - 223,225 - 227,233,254,258
H
Hawaii, 251
夏威夷,251
Heavy industry, 5, 22
重工业,5,22
HIsarna process, 72
希萨尔纳法,72
Hot Blast Furnace Gas (HBFG), 158, 173-175
热风炉煤气(HBFG),158,173 - 175
Huaneng group, 97
华能集团,97
Hubei, 11, 183, 186-188, 193-196, 200, 204, 205, 208, 209, 211, 212, 222, 224, 226, 227, 254, 258
湖北,11,183,186 - 188,193 - 196,200,204,205,208,209,211,212,222,224,226,227,254,258
Hub-spoke cluster, ix
轴辐式集群,ix
Hydraulic, 194
液压的,194
Hydrodynamic trapping, 90, 92
水动力捕获,90,92
Hydrogen, 20, 22, 41, 64, 68, 69, 75, 79, 80, 98, 99, 113, 123, 149, 163, 220
氢,20,22,41,64,68,69,75,79,80,98,99,113,123,149,163,220
I
International Emission Trading (IET), 243
国际排放交易(IET),243
India, 23, 37, 257, 258
印度,23,37,257,258
Industrial guidelines, 13
产业指南,13
Industrialization, 3, 4, 251
工业化,3,4,251
Industrial policy, 5
产业政策,5
Industrial processes, 82, 260, 273
工业流程,82,260,273
Industrial products, 5, 72
工业产品,5,72
Industrial standards, 14
工业标准,14
Industrial structure, 5, 13, 15, 45, 184, 187, 211, 213, 222, 272
产业结构,5,13,15,45,184,187,211,213,222,272
Industrial transformation, 271
产业转型,271
Industry thresholds, 12
行业门槛,12
Information, 13, 40, 86, 88, 90, 190, 191, 193, 194, 212, 229, 255
信息,13,40,86,88,90,190,191,193,194,212,229,255
Information disclosure, 190, 191, 210, 255
信息披露,190,191,210,255
Infrastructural outlays, 220
基础设施支出,220
Innovation policies, 256
创新政策,256
Integration, 53, 131-137, 140, 144, 145, 150-156, 159-170, 172, 173, 175
整合,53,131 - 137,140,144,145,150 - 156,159 - 170,172,173,175
Inter-agency coordination, 9
跨部门协调,9
Intergovernmental Panel on Climate Change (IPCC), 15, 86, 88, 89, 219, 250, 251,259
政府间气候变化专门委员会(IPCC),15,86,88,89,219,250,251,259
International commitments, 4, 10
国际承诺,4,10
International Energy Agency (IEA), 8, 12, 16, 20, 21, 23, 29, 35, 50, 51, 61, 97, 121, 220, 259, 261, 262
国际能源署(IEA),8,12,16,20,21,23,29,35,50,51,61,97,121,220,259,261,262
International Union for the Conservation of Nature (IUCN), 253
国际自然保护联盟(IUCN),253
Investment, 16, 20-23, 53, 86, 97, 109, 117, 128, 132, 137-148, 152, 155, 156, 158, 161, 162, 164, 165, 171-173, 196, 210, 212, 232, 234, 254, 255, 258, 259, 269, 270
投资,16,20 - 23,53,86,97,109,117,128,132,137 - 148,152,155,156,158,161,162,164,165,171 - 173,196,210,212,232,234,254,255,258,259,269,270
IPCC Special Report, 15, 219
IPCC特别报告,15,219
Iron/steel, 6, 7, 13, 27, 29, 38, 42, 52, 53, 61, 110, 115, 119, 120, 130, 148, 149, 174-176, 220, 226-228, 230-238, 240
钢铁,6,7,13,27,29,38,42,52,53,61,110,115,119,120,130,148,149,174 - 176,220,226 - 228,230 - 238,240
Ironmaking, 47, 62-64
炼铁,47,62 - 64
J
Japan, 16, 22, 37, 38, 122, 257, 271
日本,16,22,37,38,122,257,271
Jiangsu, 188, 202, 222
江苏,188,202,222
Joint Implementation (JI), 243
联合履行(JI),243
K
Key Performance Indicators (KPI), 189
关键绩效指标(KPI),189
Kyoto Protocol, 185, 222, 250
《京都议定书》,185,222,250
L
Large-Scale Integrated Projects (LSIP), 26, 28
大规模综合项目(LSIP),26,28
Laws, 10, 11, 26
法律,10,11,26
Leapfrogging, xiii
跨越发展,第十三页
Legal framework, 22, 23, 231
法律框架,22, 23, 231
Levels, 3-5, 9-14, 17, 18, 25, 26, 29, 40, 41, 44, 49-51, 53, 77, 93, 120, 129-131, 149, 155, 163, 164,
级别,3 - 5,9 - 14,17,18,25,26,29,40,41,44,49 - 51,53,77,93,120,129 - 131,149,155,163,164,
173, 185-187, 193, 198-200, 204, 205, 207-212, 222, 231, 233, 236, 240, 250-253, 255, 258, 261, 269
Linz-Donawitz Gas (LDG), 115-117, 119, 121, 163-166, 168-175
林茨-多纳维茨气体(LDG),115 - 117,119,121,163 - 166,168 - 175
Long-process, 6, 41
长流程,6,41
Low-carbon, 4, 7, 9, 11-13, 15, 16, 18, 19, 22,23,25,27,28,36,38,41,43, 48, 53, 71, 187, 210, 233, 256, 271
低碳,4,7,9,11 - 13,15,16,18,19,22,23,25,27,28,36,38,41,43,48,53,71,187,210,233,256,271
Low-carbon scenario, 48, 49
低碳情景,48,49
Low-carbon strategy, 51
低碳战略,51
M
Mandatory tasks, 13
强制性任务,13
Market, 10-12, 14, 15, 18, 19, 35, 38, 41, 72, 81, 82, 131, 148, 183-188, 193, 195-197, 207, 210-213, 219-222, 225, 227, 230, 234-238, 249, 253-256, 258, 260, 261, 266, 270, 272
市场,10 - 12,14,15,18,19,35,38,41,72,81,82,131,148,183 - 188,193,195 - 197,207,210 - 213,219 - 222,225,227,230,234 - 238,249,253 - 256,258,260,261,266,270,272
Market-Based Approach (MBA), 249, 253-255, 270, 271
基于市场的方法(MBA),249,253 - 255,270,271
Market inclusion, 256, 261, 266
市场纳入,256,261,266
Market principles, 213, 255
市场原则,213,255
Mean Square Percent Error (MSPE), 209
均方百分比误差(MSPE),209
Membranes capture technology, 68
膜捕获技术,68
Mergers and acquisitions, 13, 14
并购,13, 14
Methane, 3, 85, 98, 228, 250, 251
甲烷,3, 85, 98, 228, 250, 251
Methanol, 28, 81
甲醇,28, 81
Mexico, 18
墨西哥,18
Microalgae cultivation, 81
微藻养殖,81
Microalgae technology, 81
微藻技术,81
Middle East, 21
中东,21
Million Tons of Coal Equivalent (MTCE), 243
百万吨煤当量(MTCE),243
Mineral carbonation capture technology, 71, 120
矿物碳酸化捕获技术,71, 120
Mineral process, 62
矿物加工,62
Mineral trapping, 91, 92
矿物捕集,91, 92
Ministry of Ecology and Environment (MEE), 9, 25, 27, 225, 227, 230
生态环境部(MEE),9, 25, 27, 225, 227, 230
Ministry of Economy, Trade, and Industry (METI), 22
经济产业省(METI),22
Ministry of environment, 55, 252
环境部,55, 252
Ministry of Finance (MOF), 13-15
财政部(MOF),13 - 15
Ministry of Industry and Information Technology (MIIT), 9, 13, 42, 43
工业和信息化部,9, 13, 42, 43
Ministry of Information Technology, 40
信息技术部,40
Ministry of Natural Resources (MNR), 9
自然资源部,9
Ministry of Science and Technology (MOST), 9, 28, 45, 143, 152, 237
科学技术部,9, 28, 45, 143, 152, 237
Ministry of Transport (MOT), 12
交通运输部,12
Minsitry of Environmental Protection (MEP), 45
环境保护部,45
Mitigation, 4, 9, 16, 22, 25, 29, 35, 61, 227, 250, 252, 253, 268
减缓,4, 9, 16, 22, 25, 29, 35, 61, 227, 250, 252, 253, 268
Model, 36, 45, 47, 69, 72, 73, 85, 87, 94, 199, 213, 214, 250, 252, 259-261, 270, 272
模型,36, 45, 47, 69, 72, 73, 85, 87, 94, 199, 213, 214, 250, 252, 259 - 261, 270, 272
Model parameters, 260
模型参数,260
Molten iron pretreatment, 64
铁水预处理,64
Monitoring, 18, 35, 45, 73, 84, 86, 87, 96, 189, 193, 212, 216, 225, 233, 235
监测,18, 35, 45, 73, 84, 86, 87, 96, 189, 193, 212, 216, 225, 233, 235
Monitoring, Reporting and Verification (MRV), 35, 189, 193, 212, 225, 228, 233, 235-238
监测、报告与核查(MRV),35, 189, 193, 212, 225, 228, 233, 235 - 238
Monoethanolamine (MEA), 68, 121, 122
单乙醇胺(MEA),68, 121, 122
MRV system, 212, 233
MRV系统,212, 233
N
${\mathrm{N}}_{2}\mathrm{O},3,{188},{250}$
National Allocation Plans (NAP), 243
国家分配计划(NAP),243
Naature-Based Solutions (NBS), 249, 253
基于自然的解决方案(NBS),249, 253
National Basic Research Program of China, 253
中国国家基础研究计划,253
National Bureau of Statistics (NBS), 5, 253, 260, 271, 272
国家统计局(NBS),5,253,260,271,272
National Center for Climate Change Strategy and International Cooperation (NCSC), 45, 47, 51
国家应对气候变化战略研究和国际合作中心(NCSC),45,47,51
National Development and Reform Commission (NDRC), 9-13, 27, 42, 43, 45, 186, 188, 191, 194, 225, 227, 229, 230, 236, 237, 240
国家发展和改革委员会(NDRC),9 - 13,27,42,43,45,186,188,191,194,225,227,229,230,236,237,240
National ETS, 10, 14, 15, 53, 184, 187, 205, 212, 213, 219, 225-228, 230, 231, 233, 236, 238, 254, 273
国家碳排放交易体系,10,14,15,53,184,187,205,212,213,219,225 - 228,230,231,233,236,238,254,273
Nationally Determined Contributions (NDC), 27, 251
国家自主贡献(NDC),27,251
National People’s Congress (NPC), 11, 227
全国人民代表大会(NPC),11,227
National Railway Administration (NRA), 12
国家铁路局(NRA),12
National Technical Committee on Carbon Management (NTCC), 12
全国碳管理标准化技术委员会(NTCC),12
National Trust of Australia (NSW), 185, 216
澳大利亚国家信托(新南威尔士州),185,216
Nature gas, 125
天然气,125
Near net-zero carbon scenario, 48
近零碳排放情景,48
Negative carbon, 11, 254
负碳,11,254
Negative externalities, vi
负外部性,vi
Netherlands, 3, 19, 71
荷兰,3,19,71
New Entrant Reserve (NER), 233, 234
新进入者储备(NER),233,234
New Normal, 5, 6
新常态,5,6
New York, 251
纽约,251
New Zealand, 251
新西兰,251
Nitrous Oxide, 3, 228, 250
一氧化二氮,3,228,250
Nonferrous metals, 13, 204, 223, 224, 226, 235
有色金属,13,204,223,224,226,235
Non-fossil fuels, 4, 10, 25, 26, 45, 271
非化石燃料,4,10,25,26,45,271
Non-fossil targets, 255
非化石目标,255
Nordhaus, 250
诺德豪斯,250
North Africa, 21
北非,21
Norway, 16, 20, 21, 98, 213
挪威,16,20,21,98,213
Nuclear energy, 267
核能,267
O
Offshore sequestration, viii
海上封存,viii
Offshore wind power, 261
海上风力发电,261
Oil, 18, 20, 21, 26, 30, 48, 73, 91-94, 96, 97, 111, 114, 120, 148, 224, 254, 267
石油,18,20,21,26,30,48,73,91 - 94,96,97,111,114,120,148,224,254,267
Oil reservoirs, 89
油藏,89
Onshore, 20, 83, 89, 99, 230, 258
陆上,20,83,89,99,230,258
Onshore saline aquifer, 28
陆上咸水层,28
Onshore wind power, 261
陆上风力发电,261
Overcapacity, 7, 13-15, 38, 41, 42
产能过剩,7,13 - 15,38,41,42
P
Paper-making, 13, 15, 185
造纸,13,15,185
Paris Agreement, 3, 22, 25, 29, 43, 51, 61, 97, 219, 250, 251
《巴黎协定》,3,22,25,29,43,51,61,97,219,250,251
Paris Climate Change Conference, 4, 10
巴黎气候变化大会,4,10
Pathways, 13, 23, 109, 220
路径,13,23,109,220
Pelletizing, 47, 63
造粒,47,63
People’s Bank of China (PBOC), 255, 272
中国人民银行(PBOC),255,272
Performance threshold, 12
性能阈值,12
Petrochemical, 5, 7, 13, 185, 223-225, 235
石化,5,7,13,185,223 - 225,235
Phase-in periods, 213
逐步实施期,213
Photovoltaic, 258, 261
光伏,258,261
Photovoltaic solar panels, 258
光伏太阳能板,258
Physical absorption, 66, 68, 120, 122, 126, 129
物理吸收,66,68,120,122,126,129
Pilots, 9-11, 14, 15, 18, 21, 22, 27, 28, 45, 51, 53, 71, 82, 121-123, 183, 184, 186-202, 204, 205, 207, 208, 210-213, 219-230, 233, 235, 237, 254, 255, 258, 260, 271
试点,9 - 11,14,15,18,21,22,27,28,45,51,53,71,82,121 - 123,183,184,186 - 202,204,205,207,208,210 - 213,219 - 230,233,235,237,254,255,258,260,271
Pipeline, 18, 26, 28, 83-90, 114, 129, 130, 152, 154, 157, 160, 164, 165, 167-170, 230, 259
管道,18, 26, 28, 83 - 90, 114, 129, 130, 152, 154, 157, 160, 164, 165, 167 - 170, 230, 259
PMCN, 250, 259, 260
PMCN,250, 259, 260
Policy
政策
instrument, 12, 13, 36, 191, 219, 255, 256, 267, 270
工具,12, 13, 36, 191, 219, 255, 256, 267, 270
portfolios, 260, 267-269
投资组合,260, 267 - 269
Power sector, 10, 14, 15, 29, 30, 35, 40, 41, 221, 225, 228, 234, 235, 237, 238, 254, 258, 273
电力部门,10, 14, 15, 29, 30, 35, 40, 41, 221, 225, 228, 234, 235, 237, 238, 254, 258, 273
Pre-industrial, 3, 29
工业化前,3, 29
Pressure Swing Adsorption (PSA), 66, 123, 126, 127, 131-137, 138, 140-173, 175
变压吸附(PSA),66, 123, 126, 127, 131 - 137, 138, 140 - 173, 175
Primary market, 221
一级市场,221
Production capacity, 6, 12, 14, 15, 38, 42, 49, 77
生产能力,6, 12, 14, 15, 38, 42, 49, 77
Product structure, 6
产品结构,6
Projection, 45, 222, 250, 264
预测,45, 222, 250, 264
Proximity study, 90
邻近性研究,90
Public Policy Approach (PPA), 249, 250, 253, 255, 256, 260-264, 266, 267, 269-271
公共政策方法(PPA),249, 250, 253, 255, 256, 260 - 264, 266, 267, 269 - 271
Pu Hui Certified Emission Reduction (PHCERs), 194
普惠核证减排量(PHCERs),194
R
Reality check, 25, 29
现实检验,25, 29
Refining outside the furnace process, 65
炉外精炼工艺,65
Regional diversity, 15
区域多样性,15
Regulation, 9-11, 24, 26, 118, 187, 226, 227, 230
监管,9 - 11,24,26,118,187,226,227,230
Regulatory framework, 4, 16, 23, 24, 193, 237, 256
监管框架,4,16,23,24,193,237,256
Renewable energy, 21-24, 233, 234, 255, 257, 258, 260-262, 264, 265, 267, 268, 270, 273
可再生能源,21 - 24,233,234,255,257,258,260 - 262,264,265,267,268,270,273
Reporting, 10, 12, 35, 43, 188, 189, 193, 212, 216, 225, 228, 233, 235, 240, 242
报告,10,12,35,43,188,189,193,212,216,225,228,233,235,240,242
Research and Development Program of China, 254
中国研发计划,254
Resource allocation, 271
资源分配,271
Resource-intensive, 7
资源密集型,7
Risk assessment, xiii
风险评估,xiii
Risk management, 271
风险管理,271
Ronald Coarse, 184, 207
罗纳德·科斯,184,207
S
SACC-CCUS model of simulation, 48
SACC - CCUS模拟模型,48
SACC model, 46, 48
SACC模型,46,48
Safety standards, 12, 26
安全标准,12,26
Saline aquifers, 89, 90, 92-95, 97
盐含水层,89,90,92 - 95,97
Saudi Arabia, 21, 99
沙特阿拉伯,21,99
Scenarios, 19, 45, 48, 250, 254, 260-270
情景,19,45,48,250,254,260 - 270
Scotland, 20, 251
苏格兰,20,251
Scrap steel recycling, 49
废钢回收利用,49
Sea transport, 28
海上运输,28
Secondary refining process, 78
二次精炼工艺,78
Seepage emissions, 232
渗流排放,232
Sensor technology, 271
传感器技术,271
Shanghai, 11, 72, 74, 75, 183, 186-188, 192-196
上海,11,72,74,75,183,186 - 188,192 - 196
Shenhua Group, 97
神华集团,97
Shenzhen, 11, 183, 186-188, 192-196, 200, 205, 211, 212, 222, 224-226, 254,258
深圳,11,183,186 - 188,192 - 196,200,205,211,212,222,224 - 226,254,258
Shifting, 21, 196
转移,21,196
Shipbuilding, xii
造船,十二
Short-process, 6
短流程,6
Short-process steel production, 6
短流程钢铁生产,6
Simulation, 36, 45, 48, 52, 94, 205, 272
模拟,36,45,48,52,94,205,272
Sink-source matching, 53
源汇匹配,53
Sinopec, 97
中国石油化工集团公司,97
Sinopec Zhongyuan Oilfield, 28
中国石油化工股份有限公司中原油田分公司,28
Sintering, 47, 62, 63, 110, 228
烧结,47, 62, 63, 110, 228
Smart-cities, 271
智慧城市,271
${\mathrm{{SO}}}_{2},{68},{113},{185}$
Solar, 26, 265
太阳能,26, 265
Solar energy, 81, 257
太阳能,81, 257
Solubility trapping, 92
溶解捕集,92
Source-sink clusters, ix
源汇簇,ix
Source-sink matching, ix
源汇匹配,ix
Source-sink optimization, 23
源汇优化,23
South Africa, 231
南非,231
South America, 17
南美洲,17
South Korea, 6, 38, 83, 251
韩国,6, 38, 83, 251
Standard coal, 13, 225, 267
标准煤,13, 225, 267
Standardization Administration of China (SAC), 12, 13
中国国家标准化管理委员会(SAC),12, 13
State Council, 11, 13, 15, 27, 38, 42-44, 225, 237
国务院,11, 13, 15, 27, 38, 42 - 44, 225, 237
State Forestry Administration (SFA), 12
国家林业局(SFA),12
Steel, 6, 7, 12, 13, 15, 22, 27, 35-44, 48, 53, 61, 62, 64, 65, 71, 74, 75, 77-80, 82, 85, 89, 99, 109-112, 115, 116, 119, 152, 176, 185, 188, 220, 223-225, 227-229, 232, 235, 238, 241, 258, 261, 273
钢铁,6, 7, 12, 13, 15, 22, 27, 35 - 44, 48, 53, 61, 62, 64, 65, 71, 74, 75, 77 - 80, 82, 85, 89, 99, 109 - 112, 115, 116, 119, 152, 176, 185, 188, 220, 223 - 225, 227 - 229, 232, 235, 238, 241, 258, 261, 273
Steel consumption, 38
钢铁消费量,38
Steelmaking, 6, 40, 41, 47, 49, 50, 53, 55, 61-64, 75, 76
炼钢,6, 40, 41, 47, 49, 50, 53, 55, 61 - 64, 75, 76
Steel making process, 74, 225
炼钢工艺,74, 225
Steel production, 6, 14, 21, 36-40, 42, 43, 62, 76-79, 82, 99, 110, 129, 229
钢铁生产,6, 14, 21, 36 - 40, 42, 43, 62, 76 - 79, 82, 99, 110, 129, 229
Steel rolling, 62, 63, 65, 110
轧钢,62, 63, 65, 110
Steel sector, 4, 6-9, 13-15, 27-29, 35-45, 47-54, 110, 220, 223-225, 227-229, 233-235, 238
钢铁行业,4, 6 - 9, 13 - 15, 27 - 29, 35 - 45, 47 - 54, 110, 220, 223 - 225, 227 - 229, 233 - 235, 238
Stern Report, 19
斯特恩报告,19
Sticks, 9, 10, 12, 15
棍棒,9, 10, 12, 15
Storage, 18-26, 28, 53, 61, 72, 73, 83, 85, 87, 88, 90, 92-99, 113, 116-118, 125, 129-132, 135-137, 146, 149, 153-156, 158, 160-164, 168, 169, 171-173, 228, 230, 232, 235
储存,18 - 26, 28, 53, 61, 72, 73, 83, 85, 87, 88, 90, 92 - 99, 113, 116 - 118, 125, 129 - 132, 135 - 137, 146, 149, 153 - 156, 158, 160 - 164, 168, 169, 171 - 173, 228, 230, 232, 235
Storage capacity, 23, 90, 93, 95
储存容量,23, 90, 93, 95
Strategic path, 260
战略路径,260
Strategic pathway, 9, 29
战略途径,9, 29
Strategic reserve technology, 26
战略储备技术,26
Strategic roadmap, 51, 52
战略路线图,51,52
Strategy Analysis of Climate in China (SACC), 45
中国气候战略分析(SACC),45
Structural adjustment, 12, 13, 220
结构调整,12,13,220
Structural trapping, 90-92
结构陷阱,90 - 92
Substitution elasticity, 259
替代弹性,259
Supply-side reform, 15, 41
供给侧改革,15,41
Sustainable growth, 9, 11, 17, 237
可持续增长,9,11,17,237
Sweden, 77, 251
瑞典,77,251
Synthetic control, 184, 197-200, 208
合成控制,184,197 - 200,208
System design, 84, 87
系统设计,84,87
T
Takeaways, 184, 210, 250, 270
要点,184,210,250,270
Tanker, 28, 83, 84, 87, 129, 134, 136
油轮,28,83,84,87,129,134,136
Technology, 4, 6, 13, 16, 18, 19, 21-24, 27-29, 35, 41, 43-45, 48, 50-53, 62, 66-71, 73, 75, 78, 80-82, 84, 92, 94, 97, 110, 120-122, 125-128, 131-147, 150-156, 158-162, 165-172, 174, 175, 196, 237, 254, 255, 270-273
技术,4,6,13,16,18,19,21 - 24,27 - 29,35,41,43 - 45,48,50 - 53,62,66 - 71,73,75,78,80 - 82,84,92,94,97,110,120 - 122,125 - 128,131 - 147,150 - 156,158 - 162,165 - 172,174,175,196,237,254,255,270 - 273
Technology Center Mongstad (TCM), 21
蒙斯塔德技术中心(TCM),21
Temperature Swing Adsorption (TSA), 66, 67, 123, 127, 129
变温吸附(TSA),66,67,123,127,129
Terrestrial ecosystem, 272
陆地生态系统,272
TGR-BF, 53
三峡-葛洲坝水利枢纽,53
Tianjin, 11, 183, 186-188, 192-196, 200, 205, 206, 209, 211, 212, 222, 224, 226, 254, 258
天津,11, 183, 186 - 188, 192 - 196, 200, 205, 206, 209, 211, 212, 222, 224, 226, 254, 258
Top-Pressure Recovery Turbine Plant (TRT), 64, 114, 115, 119, 130-144, 146, 147, 173
顶压回收透平装置(TRT),64, 114, 115, 119, 130 - 144, 146, 147, 173
Tragedy of the commons, 250
公地悲剧,250
Trans border carbon taxes, 20, 273
跨境碳税,20, 273
Transparency, 193, 210, 212, 255
透明度,193, 210, 212, 255
Transport, 12, 18, 19, 23, 26, 28, 31, 51, 53, 61, 70, 83-90, 95, 125, 230, 232, 259
交通运输,12, 18, 19, 23, 26, 28, 31, 51, 53, 61, 70, 83 - 90, 95, 125, 230, 232, 259
Transport technology, 84, 87
运输技术,84, 87
Trapping mechanisms of ${\mathrm{{CO}}}_{2},{90}$
${\mathrm{{CO}}}_{2},{90}$的捕获机制
Two-track system, 15
双轨制,15
U
UK Emissions Trading Group, 185
英国排放交易集团,185
Ultra Low CO2 Steelmaking (ULCOS), 53, 126
超低碳炼钢(ULCOS),53, 126
UN Framework Convention for Climate Change (UNFCCC), 10, 13, 185, 186, 231, 250, 251
联合国气候变化框架公约(UNFCCC),10, 13, 185, 186, 231, 250, 251
UN General Assembly, 4, 249
联合国大会,4, 249
United Arab Emirates (UAE), 21
阿拉伯联合酋长国(阿联酋),21
United Nations, 38, 271
联合国,38, 271
United States, The, 6, 17, 27, 73, 252, 271
美国,第6、17、27、73、252、271页
Urbanization, 5, 38, 45, 251, 271
城市化,第5、38、45、251、271页
US Carbon Capture and Storage Early Deployment Act, 16
《美国碳捕获与封存早期部署法案》,第16页
V
Vacuum Pressure Swing Adsorption (VPSA), 66, 123
变压吸附(VPSA),第66、123页
Verification, 35, 190, 193, 194, 225
核查,第35、190、193、194、225页
W
Welsh, 251
威尔士人,第251页
William Nordhaus, 214, 250
威廉·诺德豪斯,第214、250页
Wind, 26, 118, 257, 261, 265, 270
风,第26、118、257、261、265、270页
Wind energy, 257, 258
风能,第257、258页
World financial crisis, 5
全球金融危机,第5页
World Steel Association, 6, 36, 40
世界钢铁协会,第6、36、40页
World Trade Organisation (WTO), 37
世界贸易组织(WTO),第37页
X
Xi Jinping, 4, 5, 41, 249, 271
习近平,第4、5、41、249、271页
Xinjiang, 28, 188, 203, 222
新疆,第28、188、203、222页
Xinjiang Dunhua Petroleum, 28
新疆敦华石油,第28页
Z
Zero carbon, 11, 20, 49, 81, 251, 260, 270
零碳,第11、20、49、81、251、260、270页
Zhejiang, 188, 203, 222
浙江,188, 203, 222